Quantum Computing Inc's $42.5 Million Backlog Faces Its First Real Conversion Test
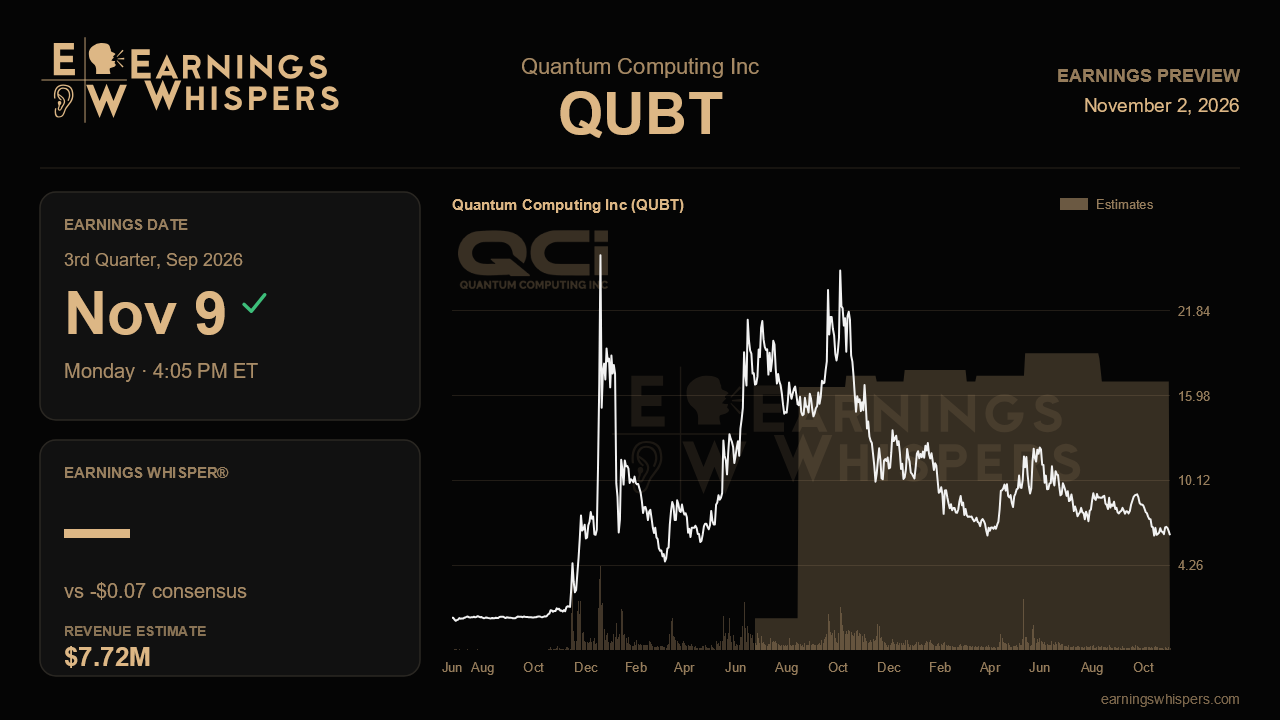
Three months ago, Quantum Computing Inc told investors its technology and manufacturing had reached an inflection point. The stock market has spent the time since betting otherwise. Shares have fallen 28% since the last report, while the S&P 500 slipped only 2.4%. So the third-quarter release, due after the close on November 9, arrives with a sharp question. Can a record $42.5 million backlog start turning into revenue fast enough to justify management's newfound confidence?
The Street is looking for revenue of about $7.7 million. That would be roughly 1,900% above the $0.4 million booked a year ago, a comparison that mostly reflects how small the business was before its acquisitions. The more useful yardstick is sequential. Revenue went from $3.7 million in the first quarter to $5.6 million in the second, so $7.7 million implies about 37% quarter-over-quarter growth. That is a solid step, but not a heroic one. The loss, however, is expected to widen to $0.07 per share from $0.05 in both the prior quarter and the year-ago period. In other words, analysts expect spending to grow faster than sales for now. That fits a company absorbing the Enhanced Semiconductors deal, standing up a second fab and building out a sales organization under a new chief revenue officer.
Management has offered no formal guidance, so there is no range to measure consensus against. It did, however, tell analysts to weight their models toward the back half of the year, warning that the timing of technical completion and deliveries is hard to predict. That advice cuts both ways. A third quarter near or modestly above $7.7 million would be consistent with a ramp building toward a stronger fourth quarter. A shortfall would be easier to explain away than at most companies. Still, it would raise doubts about how much of the backlog lands in 2026 rather than 2027. The Enhanced business is the swing factor. Management sized its 2026 contribution anywhere from $7 million to $16 million, noted that its pro forma revenue had been declining, and said a Navy contract had slipped into 2027. Any update that narrows that range, especially toward the upper half, would do more for credibility than the headline revenue figure itself.
The newer commercial catalysts deserve scrutiny too. NeuraWave reached commercial readiness in April, and Planck Dynamics placed an initial order for five systems under a framework agreement that could be worth more than $10 million. Evidence that those units shipped, or that follow-on orders arrived, would show that photonic products can broaden a revenue base that still leans 70% to 80% on government subcontracting. The same goes for any traction from the Dirac-3 install at a global consulting firm and the promised enhancements that let the machine handle more variables. Gross margin is a quieter but important test. Underutilization weighed on profitability earlier in the year, and management never quantified an improvement. Better absorption as volumes rise would suggest the fab strategy can eventually pay for itself, especially with roughly $75 million of Fab2 capital spending still ahead.
The mood has clearly soured. Sentiment has swung from moderately bullish heading into the last report to mildly bearish now. The stock trades at $6.60, well below its 200-day moving average of $8.76. It sits near the bottom of its post-earnings range of $6.08 to $9.76, a range that is itself well below the prior quarter's band of $7.30 to $14.45. That lower bar gives a credible print some room to surprise. It also means the market is not inclined to give much benefit of the doubt.
Ultimately, this report is about conversion. Management made the case last quarter with backlog, new orders and a new factory. The inflection story holds up if revenue keeps climbing sequentially, Enhanced shows stabilization, and new commercial wins start appearing in reported sales. If the backlog keeps growing while revenue stalls, investors will likely read the inflection point as further away than promised.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-28 | |
| Oct-26 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-06 | |
| Oct-01 | |
| Sep-23 | |
| Sep-22 | |
| Sep-18 | |
| Sep-18 | |
| Sep-15 | |
| Sep-14 |
