Quantum Computing Inc Tops Estimates On Acquired Revenue, But 4.5% Gross Margin, Rising Costs And Slipping Backlog Cloud The Beat
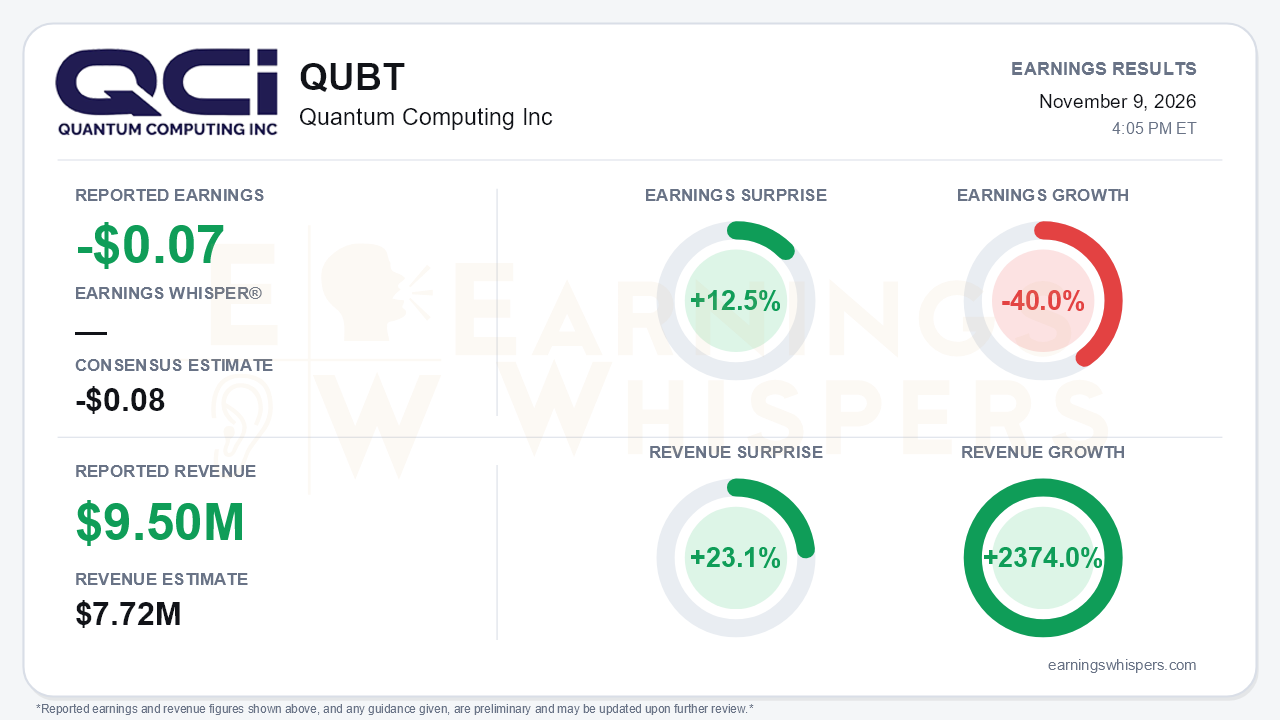
Quantum Computing Inc (NASDAQ: QUBT) delivered the kind of headline beat that looks better than it is. The company reported a loss of $0.07 per share, beating the -$0.08 consensus by 12.5%. Revenue of $9.5 million topped the $7.72 million estimate by 23.1%. Year-over-year revenue growth of 2374.0% reflects how small the business was a year ago, when it reported just $384 thousand. Earnings fell 40.0% from the prior year, a swing from a $0.01 profit to a loss. That prior-year profit, however, leaned on a $9.2 million derivative gain rather than operations. The central tension is that QCi has become a real revenue company through acquisitions, but it has not yet shown it can make money on that revenue.
The quality of the beat deserves scrutiny. Sequential growth was steep: revenue rose from $198 thousand in the fourth quarter of 2025 to $3.7 million, $5.6 million and now $9.5 million, and the third quarter alone exceeded the entire first half. Nearly all of that growth came from the LSI, NuCrypt and NHanced businesses acquired earlier in 2026, which sell photonic components, quantum communications products and advanced packaging services. Gross profit was only $428 thousand, a 4.5% margin, against cost of revenue of $9.1 million. That is an improvement from the gross loss implied for the first half; nine-month gross profit was still negative at -$1.5 million. Still, it sits far below the 20%-30% level the CFO described in the first quarter as achievable with volume. Operating expenses jumped to $29.0 million from $21.8 million in the second quarter, producing a $28.6 million operating loss. The bottom line was cushioned by $13.0 million of interest and other income on the company's roughly $1.3 billion in cash and investments. Without that interest income, the loss would look considerably worse.
The call reinforced that the improvement is top-line led. Net loss widened each quarter this year, from $4.1 million to $11.8 million to $15.1 million. Headcount has climbed to more than 330 from about 200 in the first quarter, and the CFO called the $29 million expense level a reasonable run rate with hiring continuing. Backlog slipped to $39.1 million from $42.5 million despite a sales-force build-out, as third-quarter revenue drew down prior orders. About 70% of revenue still comes from government and aerospace subcontracts. Management again offered no formal guidance, only an expectation of a "strong finish to this year." It described quarterly revenue as lumpy and noted that a Navy contract at NHanced had been pushed out. The tone also shifted: the second quarter's "inflection point" and "move aggressively" language gave way to an emphasis on execution, discipline and realism.
The catalyst list is not empty, and the call preserved a credible technology narrative. The new Dirac-3S optimization machine handles up to 9,980 variables, roughly 10 times its predecessor. Management cited published benchmarks claiming wins over a leading classical solver on most test problems, and first customer shipment is expected in the fourth quarter. The INmune Bio agreement gives QCi its first pharmaceutical customer. Hamad Bin Khalifa University in Qatar adds an international academic user, and management floated data-center compute utilization as a potential market. Fab2 has been pulled forward, with the capex estimate narrowed to $70-80 million, equipment already being ordered and spending expected through roughly mid-2027. Bears have legitimate ammunition as well. Management flagged export-control limits on international sales and political uncertainty around government funding after the midterms. It also signaled continued appetite for M&A. Each acquisition and each capex dollar trims the interest income that currently props up reported results.
The market had already turned skeptical before the report. Shares fell 30.9% from the $9.16 open after the August report to $6.33. The stock sat 26.5% below its 200-day moving average of $8.61 and had touched a 52-week low of $5.39 on November 5, just days before earnings. Investor sentiment swung from modestly positive (0.21) to modestly negative (-0.12), a meaningful deterioration in expectations over the quarter. Earnings Whispers trend signals lean negative on price and AVWAP, though momentum has turned positive off the lows.
The bottom line is that QCi beat a low bar on both lines, but the quarter mainly showed acquired revenue arriving at near-zero margins while costs and losses keep climbing. The balance sheet buys time, and Dirac-3S shipments, backlog rebuilding and visible gross-margin progress toward management's earlier targets are what would change the setup. Until those appear, the stock's slide toward its lows suggests investors are discounting the roadmap rather than paying for it.
Read our earnings preview for Quantum Computing Inc: https://www.earningswhispers.com/article/QUBT/22666
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-28 | |
| Oct-26 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-06 | |
| Oct-01 | |
| Sep-23 | |
| Sep-22 | |
| Sep-18 | |
| Sep-18 |
