WEBTOON's Q3 Test: Can Korea And Ads Offset Japan Ahead Of A Promised Q4 Acceleration?
WEBTOON Entertainment heads into its third-quarter report with a story that sounds better than its numbers. Last quarter, management described a business turning the corner: constant-currency growth rebounded to 5.2%, gross margin kept climbing, advertising snapped back to double-digit growth, and the company laid out a more ambitious plan to own a slice of the adaptations built on its stories rather than simply licensing them. Yet the near-term outlook it attached to that optimism was modest, and this report is where investors find out whether the recovery is building toward the double-digit growth management promised by the end of the year or stalling in the middle.
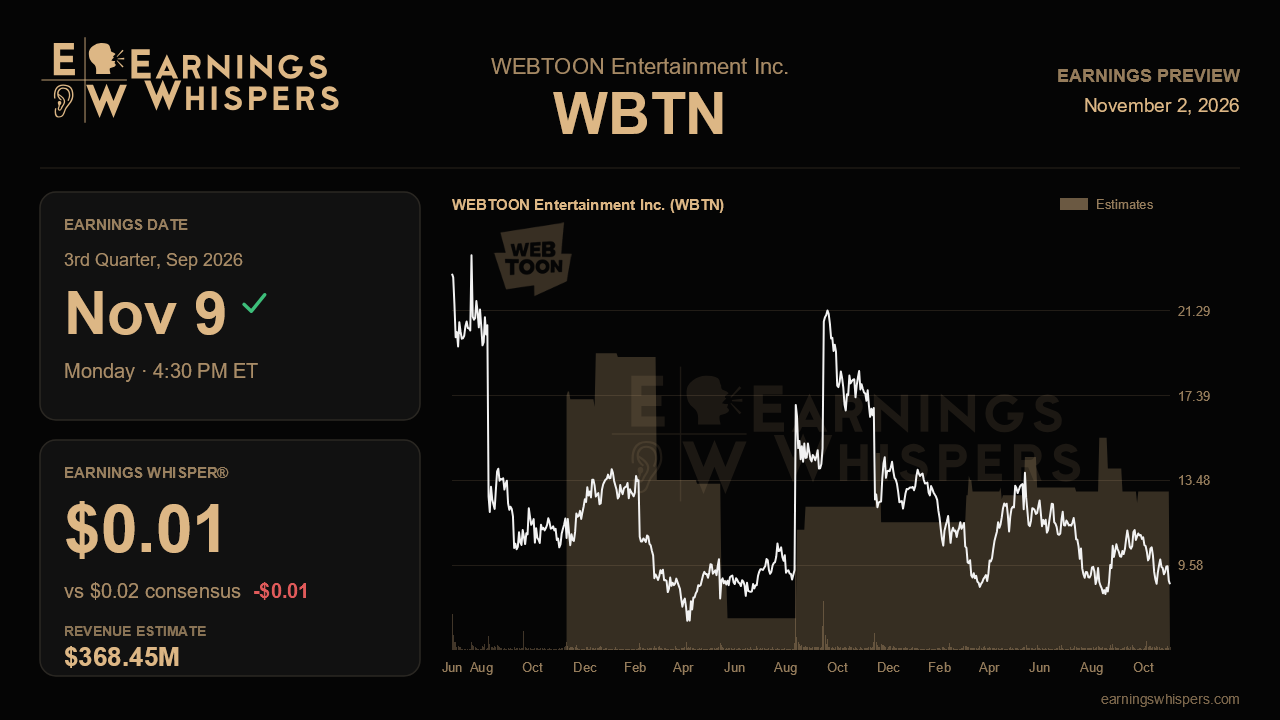
Wall Street expects a profit of $0.02 per share on revenue of roughly $368.5 million, which would be about 2.5% below the $378.0 million reported a year ago. That contraction in dollar terms sits alongside management's call for constant-currency growth of roughly 1% to 3%, implying currency is still a drag on reported results. More telling is where the Street sits relative to the company's own range of $358 million to $368 million: consensus is parked right at the top, even slightly above it. Analysts have trimmed estimates from earlier levels near $373 million, but they are still effectively assuming WEBTOON delivers its best case. The Earnings Whisper of $0.01 sits a penny below consensus, a small gap but one that hints at some skepticism about profitability after management guided adjusted EBITDA to just $0 to $5 million.
The operating checklist flows directly from last quarter's call. Korea was the engine, with revenue up about 20% in constant currency on gains in both paying users and spending per user, and it needs to keep carrying that weight. Advertising, which swung from steep declines a year ago to 11.5% growth, must show that its rebound, especially the better than 20% growth outside the core markets, is durable rather than a one-quarter bounce. Gross margin, which has risen every quarter from about 22% to 26%, should hold or improve if the mix story is real. Japan is the clearest risk. Revenue there fell 6.7% in constant currency last quarter and paying users dropped nearly 10%, the third straight period of deterioration despite a completed infrastructure overhaul. Any sign of stabilization would be meaningful; another step down would make the Q4 acceleration target far harder to believe, because management tied that goal partly to Japan finding a floor.
IP adaptation is the wild card. The segment has been extremely lumpy, and the year-ago quarter included a massive surge, so the comparison is unforgiving even with three adaptations reaching Netflix's global top 10 in the spring. Investors should also look for early detail on the RI Games investment and the $100 million adaptation fund with Naver, which shift WEBTOON toward a more capital-intensive model. Early signs of AI features such as the Cuts Make animation tool gaining traction would support the engagement story, particularly with total app monthly users still down 8% from a year ago. Marketing spend, which rose about 11% last quarter, remains the swing factor for the bottom line.
Sentiment has flipped noticeably, moving from clearly bearish before the last report to mildly bullish now, and the stock has gained about 8% since then while the S&P 500 slipped roughly 3%. That outperformance looks less impressive up close. At $8.70, shares sit much closer to the post-earnings low of $7.85 than the $11.41 high, having surrendered most of the initial enthusiasm, and the whole range sits below last quarter's.
The central question is whether WEBTOON can land at or near the top of its revenue range while showing Japan is no longer getting worse. Do that, and the promise of double-digit growth exiting the year gains credibility. Fall toward the low end with Japan still sliding, and the improving narrative from last quarter starts to look like a single good quarter rather than a turn.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-27 | |
| Oct-19 | |
| Oct-09 | |
| Aug-17 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jun-05 | |
| May-12 | |
| May-12 | |
| May-11 |
