WEBTOON Beats A Low Earnings Bar And Promises Double-Digit Growth, But Japan And Paying Users Weaken Underneath
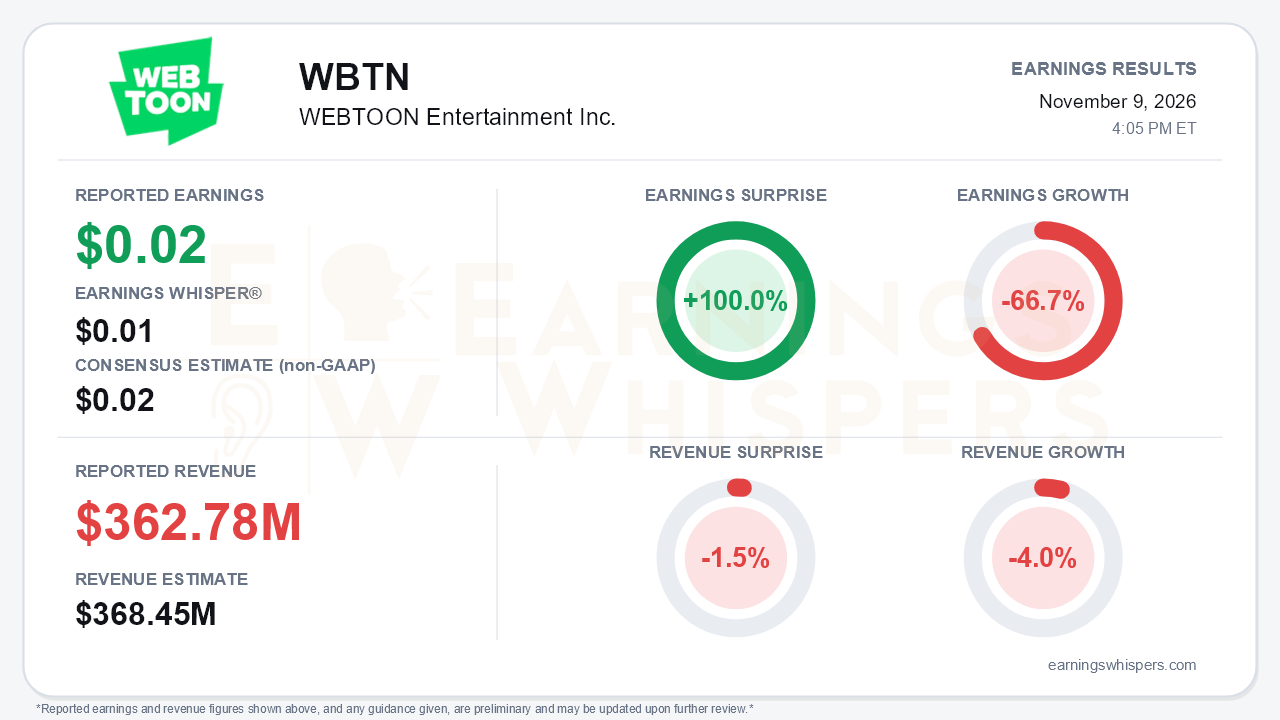
WEBTOON Entertainment (NASDAQ: WBTN) posted third-quarter adjusted earnings of $0.02 per share. That matched consensus and beat the $0.01 Earnings Whisper number by 100.0%. Revenue of $362.78 million missed the $368.45 million consensus by 1.5%. Year over year, earnings fell 66.7% and revenue declined 4.0%. On those numbers alone, the quarter was a modest disappointment. The story investors will focus on is the fourth-quarter outlook. Management guided to 9% to 12% constant-currency growth, or $371 million to $381 million, which tops estimates and implies a sharp turn from Q3's 0.2% constant-currency growth. That is the central tension: a soft quarter paired with the most confident forward guide of the year.
The quality of the quarter deserves scrutiny. Reported revenue landed within the dollar guidance range. Constant-currency growth of 0.2%, however, fell short of the 0.7% to 3.3% range management had guided to, and it decelerated from 5.2% in Q2. On the GAAP side, the net loss narrowed to $7.5 million, or $0.06 per share, from $11.1 million, or $0.09. Some of that improvement was genuine. Gross margin expanded 3.6 points year over year to 25.5%, and the operating loss shrank to $9.2 million from $14.9 million. Part of the bottom-line gain, though, came from swinging to a small income tax benefit. Adjusted EBITDA fell to $2.2 million from $5.1 million a year ago, and from $5.5 million in Q2 and $9.5 million in Q1. Management blamed foreign-currency losses tied to a stronger won. Operating cash flow dropped to $6.2 million from $16.5 million, and the nine-month figure is now negative.
Beneath the consolidated figures, the business is splitting in two. Advertising is the clear bright spot, up 30.1% in constant currency after 11.5% in Q2, 0.8% in Q1, and a decline in Q4 FY25. Korea grew 13.5% in constant currency, with paying users up 5.2% and ARPPU up 21%, although that growth slowed from about 20% in Q2. Japan continues to deteriorate:
- Constant-currency revenue fell 11.4%, worse than the 6.7% decline in Q2 and the 3.4% drop in Q1.
- Monthly active users fell 12.1%.
- Paying users fell 12.9%.
Global paying users turned negative at -3.1% after three quarters of modest growth. Rest of World paying users were down 8%. IP Adaptations revenue fell 27% in constant currency. Global MAU did rise 2.7% to 159.6 million, so the audience is growing, but monetization of that audience is not keeping pace outside Korea.
The Q4 guide is therefore the crux of the bull case, and bears have legitimate ammunition. The CFO framed the 10.5% midpoint as growth for the full quarter rather than an exit rate, a firmer commitment than the Q2 "exiting the year" language. Management also described the growth as primarily organic, calling the RI Games contribution de minimis. Even so, part of the step-up rests on IP Adaptations revenue that slipped out of Q3 and into Q4, which flatters the comparison. Profitability is not expected to improve: adjusted EBITDA guidance was held at $0 to $5 million, a 0% to 1.3% margin.
The catalyst slate is long, if still unproven:
- The Overgeared MMORPG launches through Nexon, timed with its anime release.
- A Hayate/Crunchyroll anime co-production deal covers roughly 15 titles.
- A Marvel Comics app built with Disney launches November 16.
- A JPY 10 billion, three-year plan funds local content in Japan.
- Early AI metrics are encouraging: BIOS has reached 28 million conversations, and auto-translation lifted non-English Canvas reads about 40%.
Against that, Japan's leadership has changed again, with Hiroshi Mori appointed CBO after Yuki Chae was elevated in Q1. The recovery management has pointed to since the Q4 FY25 call has yet to show up. Cash also slipped to $548.4 million from $583 million at the end of Q2 amid investment and M&A activity, though the company still carries no debt.
Investor sentiment improved meaningfully heading into the report, rising from -0.31 to roughly neutral at -0.02. The price action is more complicated. Shares hit a 52-week low of $7.85 the day after the August report and rallied to $11.41 by mid-September. They have since given back much of that move. At $9.67 just before the release, the stock was up 20.3% from the post-Q2 open but sat 15.2% below its quarter high and 9.5% below its 200-day moving average of $10.68. The Earnings Whispers price and AVWAP trend readings remain negative.
The bottom line is that WEBTOON delivered a quarter that looks weaker underneath than its EPS beat suggests. Japan is getting worse, paying users are shrinking, cash generation softened, and constant-currency growth fell short of guidance. Management offset this with a credible-sounding but timing-assisted double-digit Q4 guide, surging advertising, and a crowded catalyst calendar. With margins guided flat and the stock still below its long-term average, the burden now falls on Q4 execution and on clear evidence that Japan has bottomed.
Read our earnings preview for WEBTOON Entertainment Inc.: https://www.earningswhispers.com/article/WBTN/22677
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| Nov-02 | |
| Oct-27 | |
| Oct-19 | |
| Oct-09 | |
| Aug-17 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jun-05 |
