Sanmina's Margin Gains Face A Test As Investors Look Past Q4 To The AI Ramp
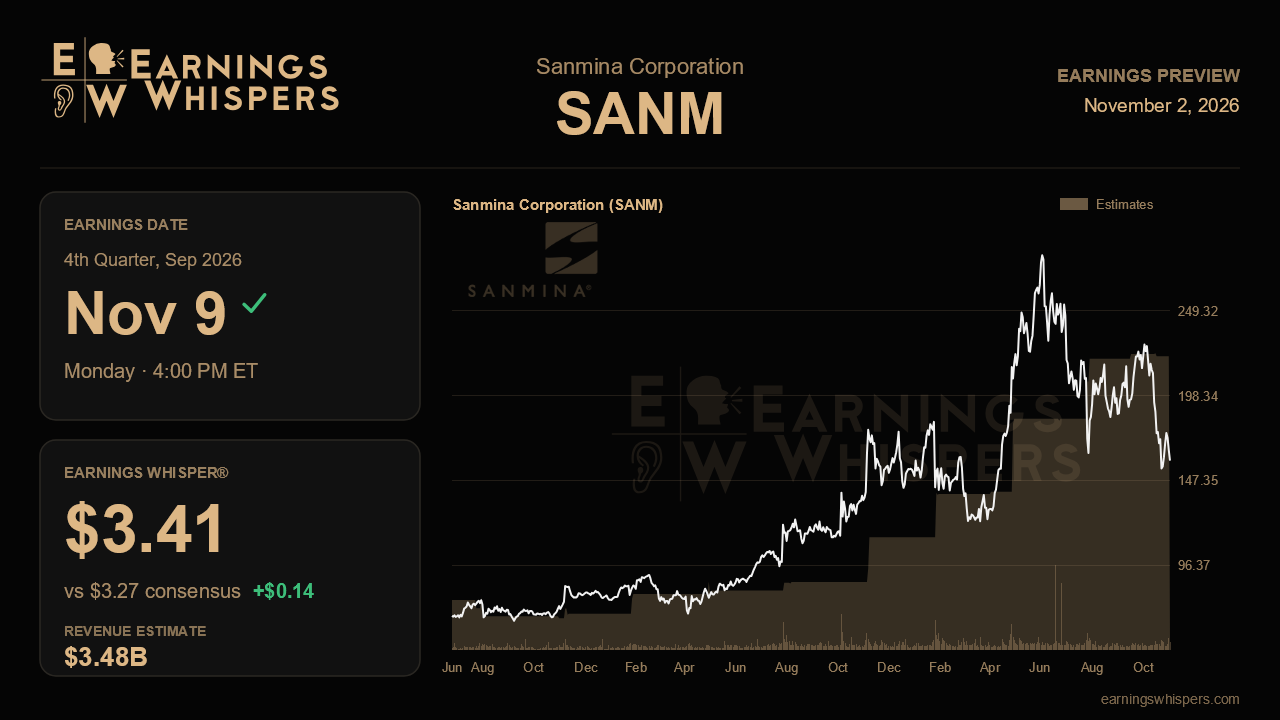
Sanmina enters its fiscal fourth-quarter report with an unusual disconnect. Management sounded more confident three months ago than at any point this year, raising its core revenue and profit outlook and reaffirming a target of more than $16 billion in fiscal 2027 sales. Yet the stock has fallen about 10% since that call while the S&P 500 gained roughly 2%. The quarter itself may matter less than whether Sanmina can convince the market that its next leg of AI growth is still on schedule.
The Street is looking for non-GAAP earnings of $3.27 a share on revenue of about $3.48 billion when results arrive after the close on November 9. That revenue figure would be roughly 66% above the $2.10 billion reported a year ago, and the earnings estimate is more than double the $1.40 earned in the same quarter last year, a reflection of the ZT Systems acquisition and a much richer margin profile. Management guided to $3.05 to $3.35 a share on revenue of $3.30 billion to $3.60 billion, so consensus sits in the upper half of the earnings range and just above the revenue midpoint. The Earnings Whisper of $3.41 is above both consensus and the top of guidance, which means the informal bar is a clean beat rather than a mere in-line print.
The composition of the quarter is what makes that bar interesting. Management said ZT would contribute only $0.8 billion to $1.0 billion, below what it had previously implied, because a few legacy storage and general-purpose compute programs shifted in timing. Holding total revenue near last quarter's $3.46 billion therefore requires the core business to keep carrying more weight. That core segment has been the real story: guidance for the year climbed to $9.1 billion to $9.2 billion, about 12.6% growth, well above the high single digits management talked about earlier, and communications, cloud and AI revenue outside ZT accelerated to 33% growth on new customers such as Cerebras. Another quarter of that kind of momentum would validate the idea that ZT-related wins are flowing into Sanmina's own factories.
Margins are the bigger swing factor. Non-GAAP operating margin jumped to 8.0% last quarter from 6.4% in the prior period, helped by favorable mix and engineering fees tied to pre-production work on the new AMD-based accelerated compute program. Some of that engineering revenue may not repeat at the same level, so a margin that holds near 8% would be a strong signal that the improvement is structural. A slide back toward the mid-6% range would suggest last quarter was flattered by one-time help. Cash flow also deserves scrutiny, since operating cash fell to about $125 million from $399 million and inventory turns slipped as Sanmina built working capital ahead of the ramp.
Sentiment has cooled noticeably. Readings have swung from solidly bullish before last quarter's report to slightly bearish now, and the shares at $165.57 sit well below the 200-day moving average near $192 and in the lower part of the post-earnings range between $151 and $232.50. Every price in the current range is below the prior quarter's low of $187.50, so the market has clearly reset expectations lower.
That reset may give Sanmina some room, but the verdict will likely hinge on the outlook. The next-gen accelerated compute program was deliberately left out of fourth-quarter guidance because of revenue recognition timing, with the ramp slated to begin in the first quarter of fiscal 2027. A first-quarter forecast showing that program arriving on time, alongside a firm reaffirmation of the $16 billion goal despite memory and custom ASIC shortages, would keep the improving narrative intact. Any slip in customer production schedules would turn ZT's recent lumpiness into a more lasting concern.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-19 | |
| Oct-12 | |
| Oct-02 | |
| Sep-18 | |
| Sep-14 | |
| Sep-11 | |
| Sep-09 | |
| Aug-27 | |
| Aug-26 | |
| Aug-22 | |
| Aug-12 | |
| Aug-06 | |
| Jul-28 | |
| Jul-28 |
