Sanmina Crushes Estimates And Guides Above The Street, But A Back-Half-Loaded FY27 Meets A Badly Bruised Stock
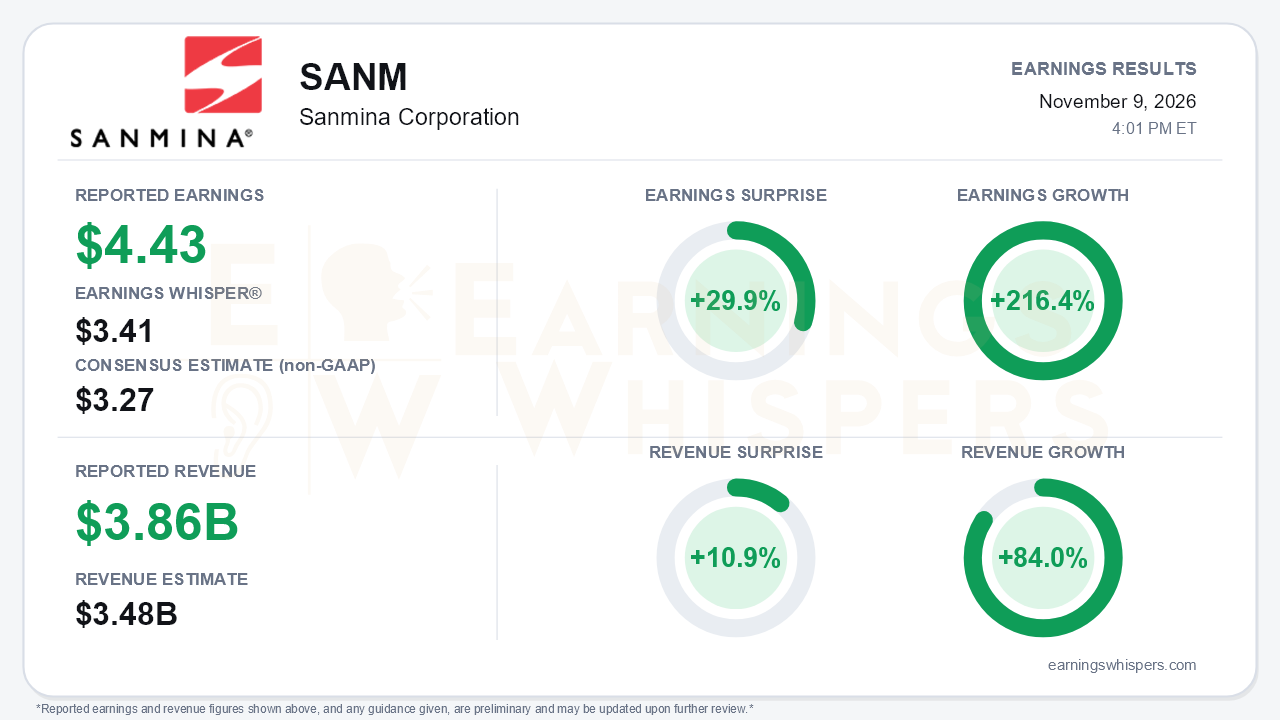
Sanmina delivered the kind of quarter that usually resets a narrative. Fiscal fourth-quarter non-GAAP earnings of $4.43 per share beat the $3.27 consensus by 29.9% and cleared the $3.41 Earnings Whisper number. Revenue of $3.858 billion topped estimates by 10.9%. Earnings grew 216.4% year over year on 84.0% revenue growth, and management issued a first formal fiscal 2027 outlook of $17.5 billion to $19.5 billion in revenue and $15.50 to $17.50 in non-GAAP EPS. That outlook sits comfortably above the "$16 billion-plus" framing it had repeated all year. The central tension is that this report arrived after the stock had already lost roughly a quarter of its value. The debate has shifted from whether Sanmina can grow to how cleanly, and how evenly, it can convert the ZT Systems-fueled opportunity into earnings and cash.
The quality of the beat deserves scrutiny, though it largely holds up. Non-GAAP operating margin reached 9.0%, up from 6.0% a year ago and well above the 7.5% to 8.0% guide. However, roughly $30 million of one-time tariff recoveries, worth about 75 basis points and about $0.42 per share, flattered the quarter and will not recur. Even after stripping that out, the result would still have cleared consensus by a wide margin. The GAAP picture is noisier. GAAP EPS of $2.14 compared with $0.88 a year ago, burdened by $84 million of acquisition and integration costs that include a $78 million fair-value increase in ZT contingent consideration, plus a heavier tax provision. Interest expense climbed to $33 million from $5 million, reflecting the acquisition debt. Cash conversion was the weak link. Free cash flow fell to just $83 million, against $224 million in the third quarter and $342 million in the second, as capital spending jumped to $159 million and working capital absorbed $116 million.
Beneath the headline, the mix shifted in a way bulls should appreciate. Core Sanmina revenue of $2.97 billion grew 42% and beat its own $2.5 billion to $2.6 billion guide, extending an acceleration from 7.3% growth in the second quarter and 17% in the third. Industrial, energy, medical, defense and auto revenue swung from flat in the second quarter to 19% growth. Meanwhile, ZT Systems revenue slid to $884 million from $1.1 billion in the third quarter and $1.88 billion in the second as legacy programs rolled off ahead of the next platform transition. In other words, the legacy business carried the quarter while the acquired AI business sat in a trough. Book-to-bill improved to roughly 1.22 from above 1.1. One crack showed in the core business, however: gross margin in Sanmina's CPS business slipped to 12.0% from 12.8% on mix and depreciation tied to growth investment.
The forward catalysts are substantial. AMD's Helios program has begun shipping in small quantities, with wins spanning hyperscalers, a frontier AI lab and OEMs, plus unexpected vertical-integration content. A second non-AMD platform (Cerebras) is in the guide, while a third platform under discussion is not, which leaves potential upside. The new Cloud and AI Systems line is guided to $7.5 billion to $9.0 billion. Medium-voltage transformer production starts in January 2027. A post-quarter refinancing pushed maturities to 2031 and trimmed spreads by about 25 basis points. Bears have legitimate ammunition, however. The fiscal 2027 guide is heavily back-half loaded, and $1.5 billion of its unusually wide $2 billion range sits in Cloud and AI Systems. Management again flagged shortages of memory and custom ASICs. Core growth is expected to moderate to low double digits, and the first-quarter margin guide of 7.0% to 7.5% steps down sharply from 9.0%. A coming working-capital build is also expected to lift net leverage into the 1.0x to 2.0x range.
The market setup is more complicated than the surprise implies. Shares closed at $134.68 ahead of the report, 26.9% below the open following the July release and 29.5% below the 200-day moving average. They were also 42.1% off the September 25 inter-earnings high of $232.50, and just 6.6% above the November 5 low. Investor sentiment fell from 0.37 to essentially neutral at 0.003, so expectations had cooled considerably even as the business was outperforming. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
That divergence frames the post-report question. The stock had already priced in substantial doubt about the ZT transition, and the guide addresses much of it on paper. Delivery, however, hinges on a second-half ramp with supply constraints and still-unsettled consignment accounting with some Helios customers.
The bottom line is that Sanmina beat decisively and guided well above prior framing, with a core business accelerating faster than anyone planned. Yet the quarter's peak margin was partly one-time, cash flow thinned, and fiscal 2027 depends on a back-loaded AI ramp. With sentiment reset to neutral and shares near their lows, the report gives skeptics less to argue about on demand, but execution and cash conversion now carry the burden of proof.
Read our earnings preview for Sanmina Corporation: https://www.earningswhispers.com/article/SANM/22671
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 59 min | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-06 | |
| Nov-02 | |
| Oct-19 | |
| Oct-12 | |
| Oct-02 | |
| Sep-18 | |
| Sep-14 | |
| Sep-11 | |
| Sep-09 | |
| Aug-27 |
