Brightstar Lottery Faces Powerball Comparison As Investors Test Its Second-Half Inflection Story
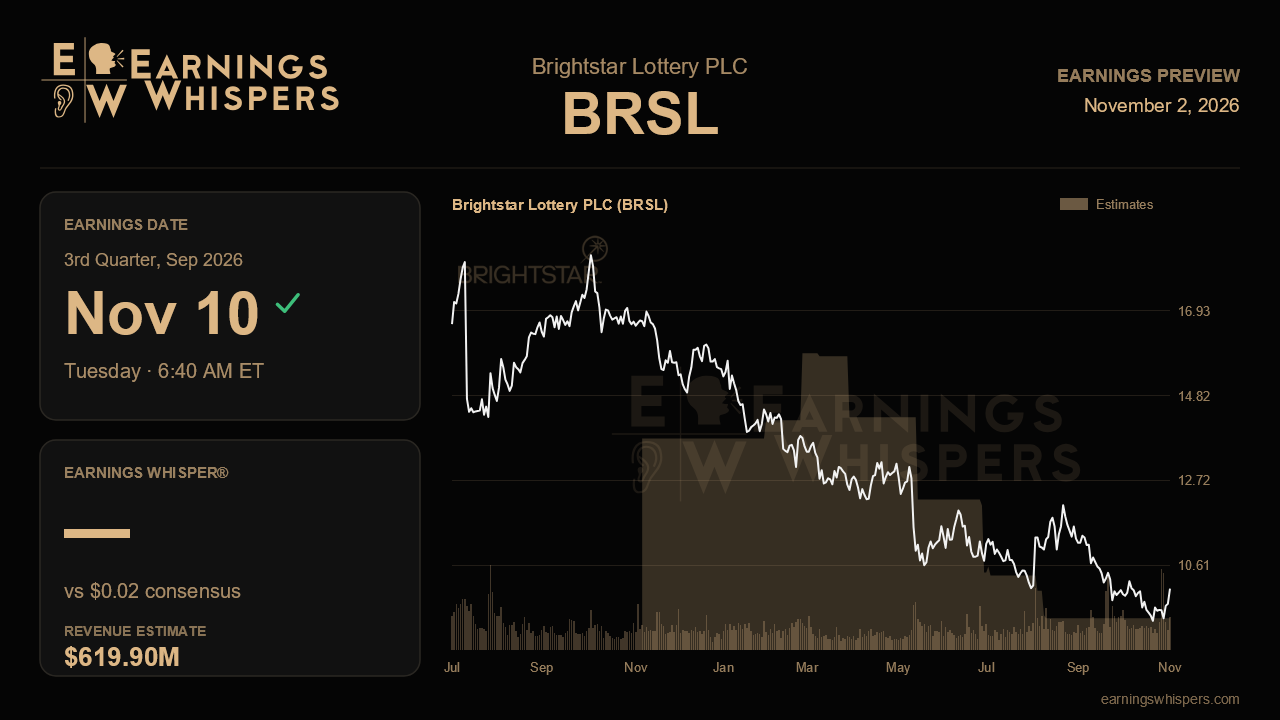
Three months ago Brightstar Lottery told investors that its heavy build phase was ending and that growth would pick up in the back half of the year. Its third-quarter report, due before the market opens on November 10, is the first real test of that promise. It is also the quarter management itself flagged as the hardest one on the calendar. That makes this release less about whether Brightstar can post a flashy number and more about whether the inflection argument survives a deliberately soft patch.
The Street has set a very low bar. Consensus calls for earnings of about $0.02 per share, down roughly 94% from $0.36 a year ago, on revenue of $619.9 million, a 1.5% decline from $629.0 million. That revenue figure would be up from the $584.0 million reported last quarter, but the year-over-year picture is one of mild contraction. Management has reaffirmed full-year revenue guidance of $2.50 billion to $2.55 billion. The consensus of $2.51 billion sits near the bottom of that range, so analysts are giving the company little credit for upside. A third quarter that tracks only flat would keep that conservative view intact. A clear beat on revenue would start to pull estimates toward the middle of the range.
The operating setup explains the caution. Management guided third-quarter same-store sales to roughly flat with last year. Italy is expected to be neutral because of calendar timing. In the US, the company is lapping a $1.8 billion Powerball jackpot from the year-ago quarter. Mega Millions remains a sore spot, with weekly sales still running below historical levels at the $5 price point and the consortium yet to decide on changes. Flat same-store sales would validate management's forecasting discipline. A negative print would challenge the claim that the first half's acceleration, from 1% growth in the first quarter to 1.5% in the second, reflects real underlying demand rather than favorable jackpot luck.
Margins are the second swing factor. Brightstar earned about 42% adjusted EBITDA margins last quarter, excluding upfront-fee amortization, and warned that second-half margins would dip below that level. The reasons were ramp costs in its consumer-facing digital business and a heavier mix of lower-margin product sales. The question is how far they slip. The Optima cost program, whose savings target has been raised from $50 million to $80 million and now to $100 million, should cushion the decline. A shallow dip would suggest cost savings are offsetting investment spending. A steep one would raise doubts about how much of those savings reach the bottom line. iLottery, where first-half wagers rose 22%, is the clearest growth engine and needs to keep compounding.
The newer catalysts deserve progress reports rather than profits. These include the timing of the Sao Paulo retail launch following the digital go-live, early activation from the roughly 23,000 retailers recruited for the MyLotteries Play app, and the planned shift of Italy's Finestre game to five-minute draws. Investors should also look for confirmation that leverage, at 3.24x last quarter, keeps moving down and that the normalized free cash flow target above $400 million still stands.
The market has grown more skeptical despite the upbeat tone of the last call. Sentiment has weakened to 25.5% bearish from 9.5% a quarter ago. The shares are down 4% since the last report, trailing the S&P 500 by about three points. At $10.03, the stock sits well below its 200-day moving average of $11.74 and in the lower part of its post-earnings range of $9.10 to $12.23. That range dipped beneath the prior quarter's low of $9.90, a sign of fading conviction. If Brightstar delivers flat comparable sales, contained margin erosion and visible progress on Brazil and digital, the inflection story remains intact heading into easier comparisons. If the soft quarter turns out softer than promised, the reaffirmed guidance starts to look like a ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-13 | |
| Sep-16 | |
| Sep-16 | |
| Sep-09 | |
| Sep-08 | |
| Aug-04 | |
| Jul-28 | |
| Jul-15 |
