Brightstar Lottery Clears A Low EPS Bar, But The First Guidance Cut Of 2026 Overshadows Its Operational Acceleration
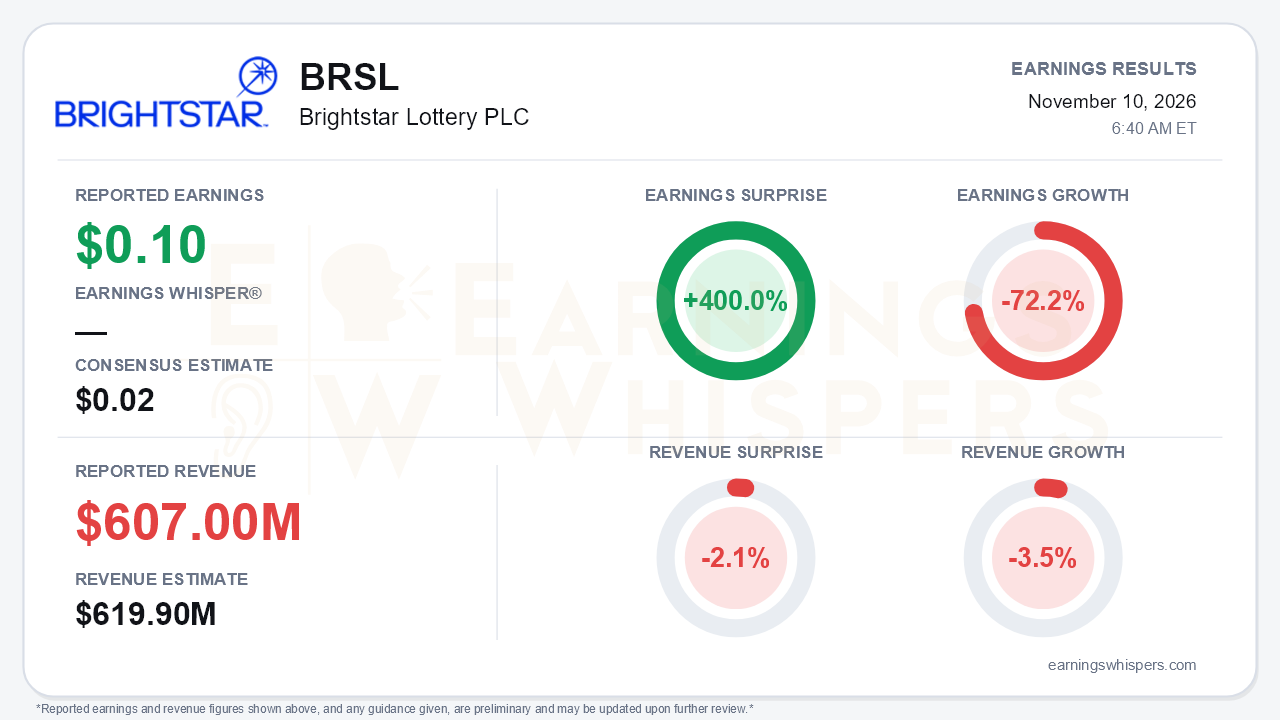
Brightstar Lottery reported third-quarter adjusted earnings of $0.10 per share, well above the $0.02 consensus estimate, a 400.0% surprise. That is the only headline figure that looks clean. Revenue of $607.0 million missed the $619.9 million consensus by 2.1% and fell 3.5% from a year ago. Earnings fell 72.2% year over year. Management also cut full-year revenue and adjusted EBITDA guidance for the first time this year. That is the central tension: the operational acceleration management promised on the second-quarter call arrived on schedule, while the outlook for the year moved lower.
The EPS beat needs context. Consensus was set very low because the new Italy Lotto license is driving non-cash service revenue amortization sharply higher. Upfront license fee amortization reduced revenue by $99 million, compared with $53 million a year ago. Net of tax, it cost Brightstar's shareholders $0.23 per share, versus $0.12 last year. Most of the year-over-year EPS decline therefore traces to an accounting charge rather than to cash erosion. Strip out amortization, and the picture is steadier. Adjusted EBITDA slipped only to $289 million from $294 million, and the adjusted EBITDA margin widened to 47.5% from 46.7% on better product mix and cost efficiencies. Not every pressure was non-cash, however. Adjusted EBIT fell to $130 million from $185 million. Net interest expense rose to $50 million from $36 million. The adjusted effective tax rate climbed to 39.1% from 26.7%. On a GAAP basis, diluted EPS from continuing operations fell to $0.12 from $0.29.
Beneath the headline, the business is shifting in mix. Operational revenue growth rose to 4% from roughly 1% in the first half, matching what management guided on the prior call, and Q4 is expected to grow at a similar mid-single-digit pace. Product sales more than doubled to $60 million, driven by Portugal terminals, North Carolina vending machines and instant-ticket printing. Other service revenue grew 11%, up from 5% in Q2. Rest-of-world revenue jumped 42%. The core wagering engine, however, weakened:
- Global same-store sales fell 3.9%, against 7.9% growth a year ago.
- U.S. multi-state jackpot wager revenue dropped 30%.
- U.S. instant and draw same-store sales fell 1.4%, compared with roughly flat in the first half. Management cited a selective, pressured lower-income consumer squeezed by inflation and fuel prices.
- Italy revenue fell 19%, hurt by amortization, a record summer heat wave and, after quarter-end, an October trucker strike that delayed instant-ticket deliveries.
The revised outlook makes that weakness concrete. Revenue guidance fell to $2.435-$2.455 billion from $2.50-$2.55 billion, a range that had been reaffirmed twice. Adjusted EBITDA guidance fell to $1.14-$1.16 billion from $1.16-$1.19 billion, which management attributed primarily to a weaker euro. The revenue cut reflects softer second-half same-store sales, slower Italy B2C phasing and FX. A near-$1 billion Powerball jackpot in November removes the chance to lap last December's $1.8 billion run. Management also guided Q4 margin below recent quarters on product mix. More importantly, management now says its medium-term 5% growth target will lean more on Italy B2C and iLottery, which require heavy upfront investment and carry lower near-term margins. Retail is expected to contribute less. Management's tone shifted from the second quarter's "inflection point" language to "remain vigilant."
Bulls still have catalysts to point to:
- Italy's draft budget law would extend the scratch-and-win concession 15 months, to December 2029, for roughly €188 million, shared pro rata with partners. It would also add a weekly Wednesday Lotto draw.
- The Dual Play hybrid instant game drove record e-instant wagers in September.
- Otto self-service terminals and Sani proximity services add new recurring revenue streams.
- Three new iLottery platforms are planned over the next year, and Brightstar has bids pending in Texas and New York.
Cash guidance was maintained at about $750 million excluding the license payment. Year-to-date shareholder returns now exceed $200 million. On the other side, net debt rose to $3.8 billion after the final Italy Lotto payment, and leverage edged up to 3.30x from 3.24x.
Investors were already leaning skeptical heading into the report. Earnings Whispers sentiment became more negative, moving from -0.10 to -0.27. Shares closed at $10.01 on the day before the release, down 4.2% from the opening price after the August report. That leaves the stock 14% below its 200-day moving average and 18% below the August 13 quarter high of $12.23. The stock hit a 52-week low of $9.10 on October 22 and has since rebounded about 10%. Momentum readings are neutral, while AVWAP remains negative.
The bottom line is that Brightstar delivered the operational acceleration it promised, but against a depressed EPS bar, a revenue miss and a lower full-year outlook. The longer-term question is whether growth initiatives can carry the medium-term target as same-store sales soften and the growth mix shifts toward investment-heavy channels. Until the core wagering trends stabilize, bears have legitimate ammunition despite the headline beat.
Read our earnings preview for Brightstar Lottery PLC: https://www.earningswhispers.com/article/BRSL/22687
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-13 | |
| Sep-16 | |
| Sep-16 | |
| Sep-09 |
