Hesai Must Prove Its Back-Half LiDAR Ramp And Robotics Pivot As Shares Sink
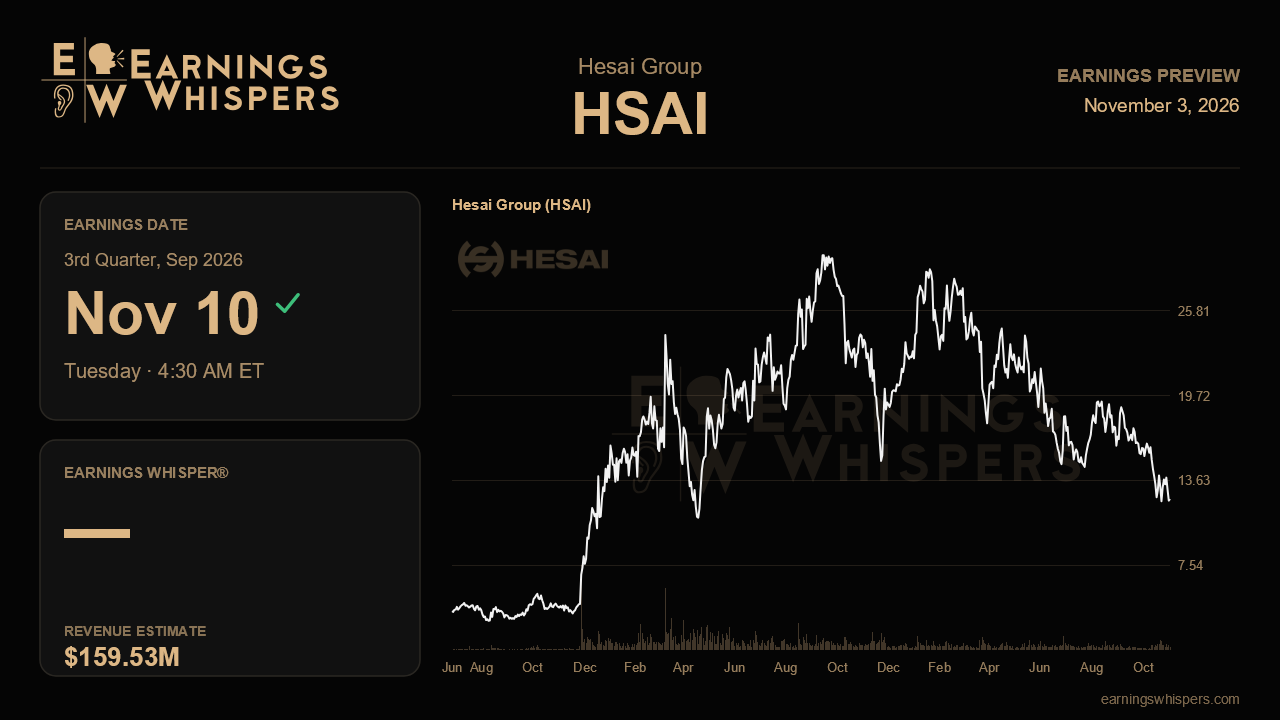
Hesai Group heads into its third-quarter report with an unusual disconnect. Management spent the last call recasting the company from a LiDAR supplier into a broader physical-AI platform, raising targets for its new robotics-focused SGI segment along the way. Since then the stock has fallen 22%, trailing the S&P 500 by nearly 20 percentage points. The report due before the open on November 10 needs to show that the expansive story told in August is turning into shipments, revenue and margins on schedule.
The revenue bar looks modest relative to what the company promised. Consensus calls for about $159.5 million, up roughly 43% from $111.7 million a year ago and well above the $126.9 million reported last quarter. Management, however, guided to $162 million to $169 million, or RMB1.1 billion to RMB1.15 billion. That puts the Street below the bottom of the company's own range. When guidance was issued, analysts were looking for about $176.5 million, so expectations swung from too high to cautious. A result inside the guided range would technically beat consensus. A result below $162 million would raise doubts about management's ability to forecast its own ramp. A clean earnings comparison is not available, so revenue and margins will carry the weight.
The core LiDAR business is the first test. Hesai shipped about 1.1 million units in the first half against a full-year target of 3 million to 3.5 million, and it has held that target unchanged on every call this year. That leaves a heavy second-half load. Third-quarter guidance of 800,000 to 850,000 units, up from 628,000 in the second quarter, is the first step. Hitting that range would make the remaining Q4 requirement look achievable. Falling short would suggest the full-year number is at risk. Look as well for robotics LiDAR keeping pace with its target of more than 500,000 units for the year, and for further progress on the Great Wall, Volkswagen China and GAC Toyota programs that management cited as new wins.
The second test is SGI, the newer business. It booked its first revenue, RMB45 million, in the second quarter from actuation modules, while operating losses widened to RMB64 million. Full-year SGI guidance was doubled-plus to RMB200 million to RMB300 million, which implies at least RMB155 million in the back half. This quarter should therefore show a clear sequential jump, early revenue from Cosmo, and evidence that actuation volumes are moving toward roughly 10,000 modules a month. How that revenue is earned matters as much as how much. Much of the near-term actuation business runs through Sharpa, a related party co-founded by Hesai's CEO, with a proposed supply cap tripled to RMB300 million pending shareholder approval. A broader customer list would ease that governance concern. Heavier reliance on Sharpa would sharpen it.
Margins tie the two tests together. Gross margin held near 40% last quarter despite steady pricing pressure, and Xiaomi's decision to add RoboSense as a supplier is a reminder that multi-sourcing can erode share and pricing. If blended margins stay near 40% while SGI losses stabilize, the company can extend its run of profitable quarters and make its 2027 SGI breakeven target look credible.
The market is plainly skeptical. Shares trade at $12.30, near the $12.00 post-earnings low and far below the 200-day average of $19.81. Sentiment has cooled to 12.1% bullish from 16.4% heading into the last report. That lowers the hurdle somewhat, but it also suggests investors want proof rather than another round of new product teases. The central question is whether Hesai can deliver the LiDAR volume step-up and a credible SGI ramp at the same time without sacrificing margins. If it can, the platform narrative holds. If either leg slips, the recent selloff will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-29 | |
| Oct-20 | |
| Oct-14 | |
| Sep-25 | |
| Aug-21 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Jul-31 | |
| Jul-27 | |
| Jun-11 | |
| May-26 | |
| May-20 | |
| May-19 |
