Hesai's Physical AI Bet Outruns Plan As Core Lidar Misses Its Own Guide And Drops Its Shipment Target
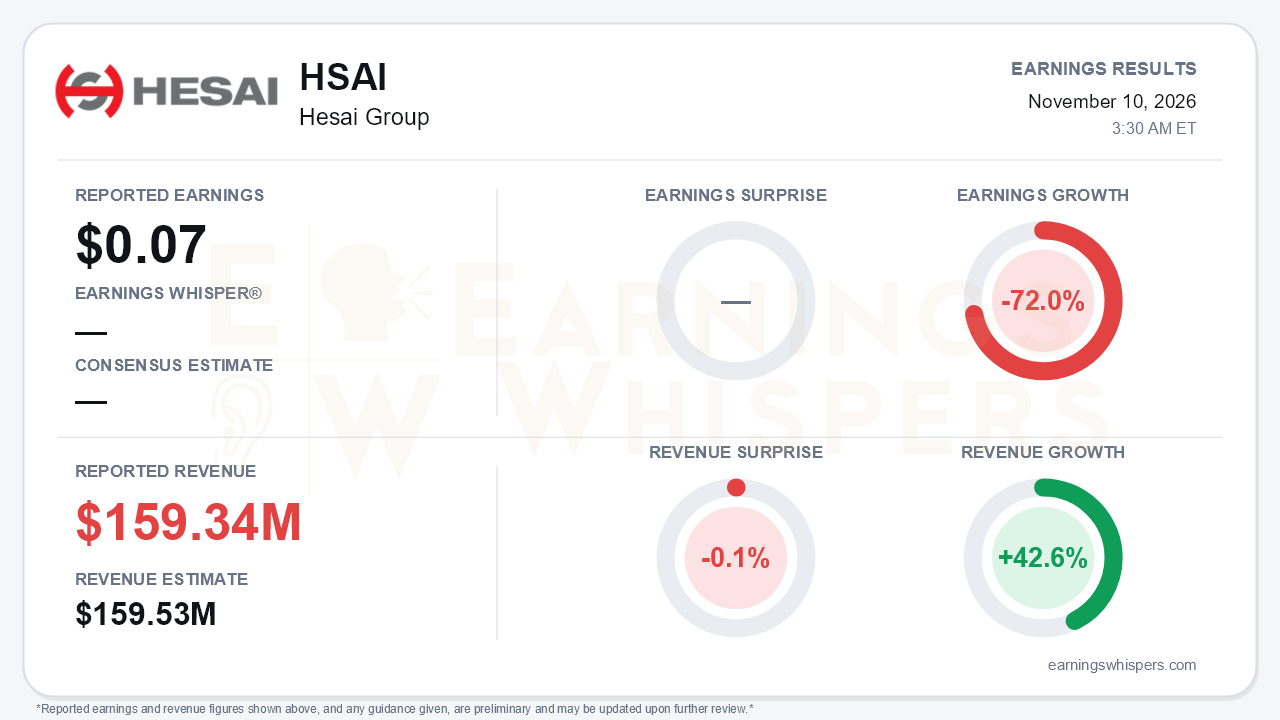
Hesai Group delivered a two-speed quarter. Its newer robotics and spatial-data businesses are running well ahead of plan, while the lidar franchise that funds them fell short of management's own forecasts. Third-quarter revenue was $159.34 million, essentially in line with the $159.53 million consensus, a 0.1% miss. Revenue grew 42.6% year over year on a dollar basis, though growth was a more modest 34.3% in the company's reported RMB figures, with the gap reflecting currency translation. Earnings were $0.07 per share, down 72.0% from a year ago. No consensus EPS was available for comparison. The more important number was RMB1,068 million in revenue against the RMB1.10 billion to RMB1.15 billion management had guided on the August call. That is the central tension: the growth story is broadening, but the core engine is decelerating at the margin.
The steep earnings decline looks worse than the underlying business. GAAP net income fell 68.5% to RMB80.8 million, mainly because the year-ago quarter included RMB185.1 million of one-time income from an equity-investment disposal and an IP transfer. The cleaner signal is at the segment level. Lidar operating income rose 88% year over year to RMB145.5 million, more than double the RMB66 million posted in Q2. Gross margin improved sequentially for a third straight quarter, to 41% from 40% in Q2 and 39% in Q1, though it remained below last year's 42.1% because of mix.
Consolidated operating income still fell 19.1% to RMB62.6 million, for three main reasons:
- the Strategic Growth Initiatives (SGI) operating loss widened to RMB82.9 million from RMB64 million;
- other operating income fell by more than half;
- an RMB18.9 million foreign-exchange loss hit the bottom line.
SGI is where the upside lives. Segment revenue roughly doubled sequentially to RMB90.5 million, and nine-month SGI revenue of RMB135 million has already cleared the original full-year target of RMB100 million. Management reaffirmed 2026 SGI guidance of RMB200 million to RMB300 million and held its 2027 goal of roughly $100 million in revenue at breakeven. Robotic actuation module shipments rose 97% sequentially to 23,405 units, monthly capacity hit the 10,000-unit target, and full-body modules entered mass production. The Kosmo spatial-data platform launched globally and booked first revenue, with partnerships spanning Pixar's RenderMan, Alibaba's Amap and JD.com.
The quality of that SGI revenue deserves scrutiny. The income statement shows RMB90.3 million of third-quarter revenue from a related party, almost exactly matching SGI segment revenue. The call flagged heavy actuation concentration on Sharpa, which management describes as its anchor customer. Amounts due from related parties now stand at RMB164 million, up from zero at year-end.
On the lidar side, bears have legitimate ammunition:
- Shipments of roughly 730,000 units missed the 800,000 to 850,000 guide, even though they rose 65% year over year.
- Management blamed automakers cutting 2026 sales targets, along with company-specific problems at a robotic lawnmower customer.
- The full-year target of 3 million to 3.5 million lidar units, reiterated on three prior calls, was not repeated. With about 1.83 million shipped through September, it appears out of reach.
- Fourth-quarter revenue guidance of RMB1.10 billion to RMB1.15 billion is essentially the range previously set for Q3, which implies a deferred ramp rather than an acceleration, and it came in below estimates.
- Hesai's share of China's long-range ADAS lidar market has slipped from 55% in March to 43% in September, though it still ranks first.
- An analyst noted that Mercedes-Benz's new Level 2 system for Germany launches without lidar.
The counterweights are real. Hesai has more than 1 million units in ET-series orders across five OEMs, including Cadillac and a top European automaker. It also has new design wins with Wuling and Leapmotor, export programs with seven Chinese OEMs, and management's view that ATX pricing under signed 2027 contracts should stay relatively stable. Full-year opex is now guided up about 20%, so the company is leaning into SGI investment just as lidar growth softens. A RMB7 billion cash reserve gives it room to do so.
The market had already priced in plenty of doubt. Shares closed at $14.31 ahead of the report, down 9.2% since the post-August open and 26.3% below the 200-day moving average of $19.43. They have given back a spike to $19.40 in late August and remain about 19% above the 52-week low of $12.00 set on October 22. Investor sentiment stayed mildly positive but softened slightly, to 0.13 from 0.16. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive while price and AVWAP remain negative.
The bottom line is that Hesai's Physical AI pivot is gaining traction faster than promised. The lidar business that funds it, however, missed its own guide and abandoned a long-held shipment target in a softer auto market. Until lidar volumes reaccelerate and SGI revenue diversifies beyond a related-party anchor customer, the better story is unlikely to translate cleanly into a better stock.
Read our earnings preview for Hesai Group: https://www.earningswhispers.com/article/HSAI/22695
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-03 | |
| Oct-29 | |
| Oct-20 | |
| Oct-14 | |
| Sep-25 | |
| Aug-21 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Jul-31 | |
| Jul-27 | |
| Jun-11 |
