Consolidated Water's First Quarter Under New Cayman License Tests Its Bridge To 2027
Consolidated Water heads into its third-quarter report with a story that is easier to like for 2027 than for the quarter at hand. The company finally secured its long-negotiated Cayman retail license last quarter and pushed its Hawaii desalination project closer to construction. But the new license took effect August 1 with base rates roughly 6.5% lower per gallon, so this report offers the first look at what that settlement costs, landing on top of a manufacturing slump and shrinking margins.
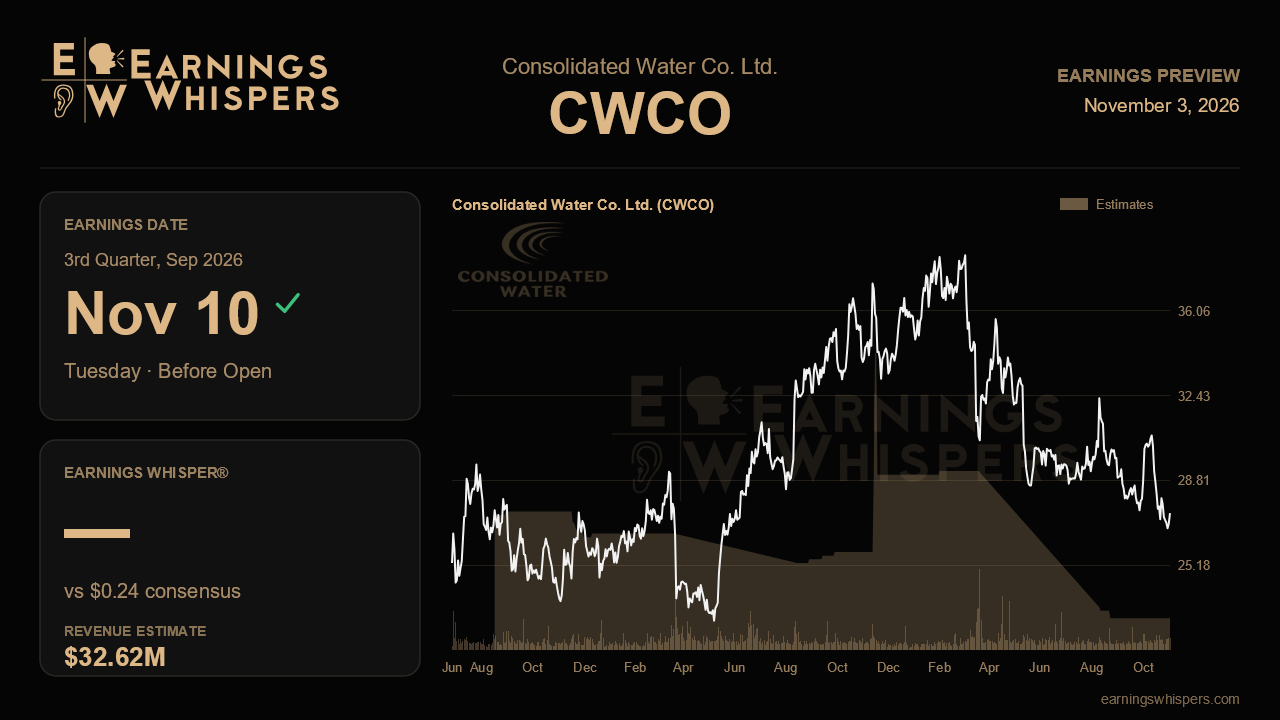
Wall Street is braced for contraction. Consensus calls for earnings of $0.24 per share on revenue of $32.6 million, down about 29% and 7%, respectively, from the $0.34 and $35.1 million reported a year ago. Against last quarter's $0.25 and $32.9 million, though, the estimates are essentially flat. Analysts are effectively betting that the second quarter marked the floor for 2026. Management has not offered a fresh numeric outlook, but it did reaffirm that manufacturing revenue will fall short of 2025's record $18.7 million, which sets a low bar for that segment.
The retail line deserves the closest reading. Two months of the lower license rates will flow through this quarter, and the question is how much strong demand can cushion them. Cayman stayover arrivals ran 11% ahead of last year in the first half and above pre-pandemic levels, management flagged a high probability of drier-than-normal weather that tends to lift water sales, and a major non-potable customer moved to a higher rate after a concession lapsed in May. If retail revenue holds up despite the rate cut, the license looks like a fair trade for 25 years of visibility. A sharp drop would suggest the structural headwind is larger than volume can offset.
Margins are the second test. Gross margin slid to 33% last quarter from 38% a year earlier as manufacturing volume collapsed and services shifted toward lower-margin construction work after two operating contracts expired. Manufacturing revenue fell 76% in the first quarter and 49% in the second, so even modest sequential improvement would help absorption. Bulk, up 20% last quarter with both Cat Island plants in the Bahamas now running, should remain the steadiest contributor, though pass-through energy costs flatter revenue more than profit. Investors should also check whether Bahamas receivables, which have swung between roughly $17 million and $24 million, continue to normalize, and whether the debt-free balance sheet keeps building from $132.6 million in cash.
The forward catalysts matter as much as the reported figures. Management framed Hawaii construction as likely to begin later in 2026 following a July limited notice to proceed covering about $6 million of long-lead equipment, but an archaeological permit was still outstanding. Confirmation that permitting is on track would support the 2027 thesis; a slip would weaken it. Additional municipal orders on the heels of the record $10.1 million Florida purchase, and progress on California operating contracts despite tougher competition, would reinforce the idea that manufacturing and services are rebuilding backlog.
The market has not been patient. Shares have fallen 11.5% since the last report, trailing the S&P 500 by nearly nine points, and at $27.41 they sit well below the 200-day average of $31.55 and only about 3% above the post-earnings low of $26.60. Sentiment, oddly, has turned modestly bullish from mildly bearish a quarter ago, suggesting some investors see the selloff as already pricing in the trough. The central issue is whether this quarter shows retail resilience under the new license and stabilizing margins. If it does, the bridge to a stronger 2027 looks intact. If margins slip again, the wait may feel longer than the market is willing to tolerate.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 23 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-12 | |
| Oct-01 | |
| Aug-20 | |
| Aug-12 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 | |
| Jul-22 | |
| Jun-24 | |
| Jun-08 | |
| Jun-05 |
