Consolidated Water Posts Its Weakest Quarter Of 2026 As Hawaii Slips Again, Leaving The Case Resting On A 2027 Backlog Ramp
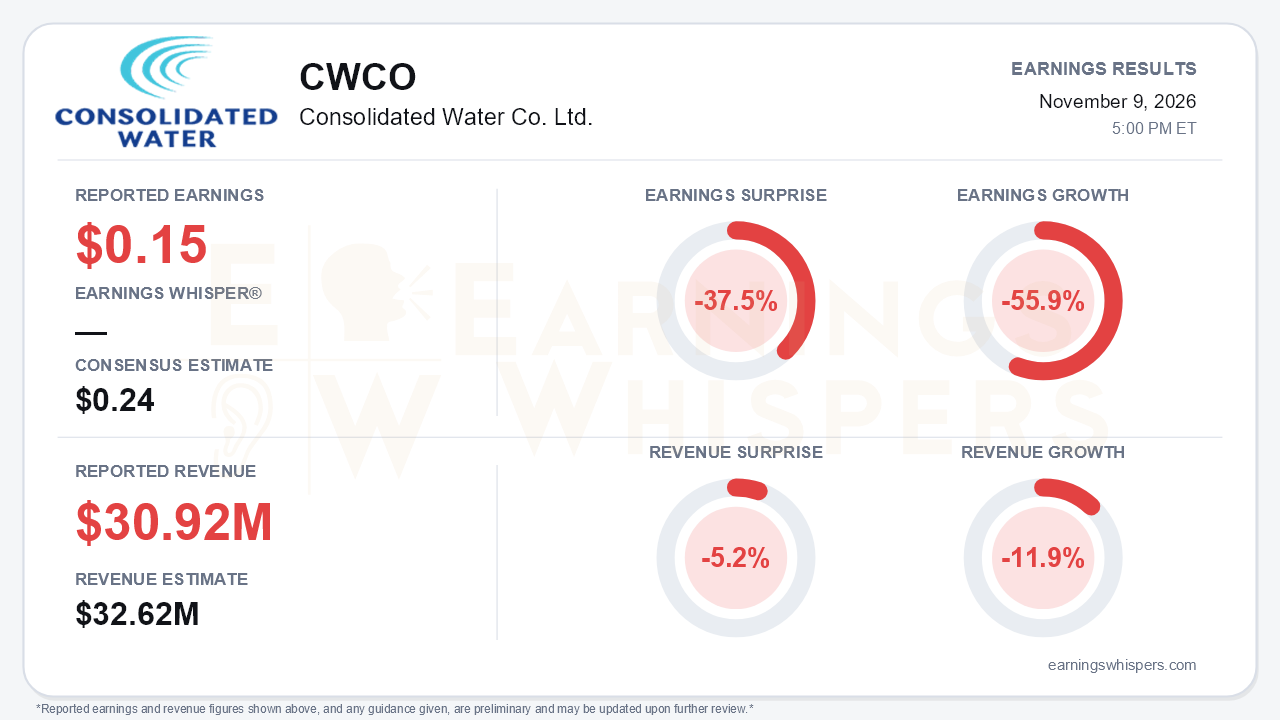
Consolidated Water delivered a clear miss in the third quarter. Earnings from continuing operations were $0.15 per share, against a $0.24 consensus. That is a 37.5% shortfall, and earnings fell 55.9% from a year ago. Revenue of $30.92 million missed the $32.62 million estimate by 5.2% and declined 11.9% year over year. The deterioration also accelerated. Revenue had fallen only about 2% in the second quarter, and EPS dropped to the lowest level of the year after $0.24 in Q1 and $0.25 in Q2. The central tension is straightforward. The utility side of the business is holding up, but the project-driven segments are in a trough. The catalysts meant to fill that trough, chiefly the Hawaii desalination build, keep moving further out.
The segment detail shows where the earnings went. Services gross profit collapsed to $1.3 million from $3.8 million, and the segment swung to a $258,000 operating loss from $1.9 million of operating income. Construction revenue fell to $3.5 million from $6.4 million as the Colorado and California projects wound down with nothing yet to replace them. O&M revenue dropped to $6.1 million from $7.7 million after three California contracts expired. Manufacturing revenue fell 39.7% to $2.8 million, cutting segment operating income to $309,000 from $1.4 million. Consolidated gross margin slid to 31.8% from 36.9%, extending a steady decline from roughly 36% in Q1 and 33% in Q2. Corporate G&A also rose to $4.1 million from $3.6 million. The quality of the quarter deserves scrutiny in one more respect. The tax provision fell to $127,000 from $827,000, which cushioned the decline. Without that help, the bottom line would have looked even weaker.
The regulated businesses offered the only real offset. Retail revenue rose 5.7% to $8.2 million despite the new Cayman license. That license cuts average rates by roughly 6.5% and took effect August 1. Volume turned positive at +1%, compared with -2% in Q2 and -10.2% in Q1, helped by Cayman stayover tourism running 11.3% higher year to date. Still, retail gross profit slipped to $4.18 million from $4.32 million. The top-line gain leaned on energy pass-throughs, and the rate cut will be a full-quarter drag going forward. Bulk revenue climbed 20.8% to $10.1 million on pass-through charges and the new Cat Island plants. Bulk gross profit rose, but higher diesel and maintenance costs compressed the margin percentage.
The forward story is credible but increasingly back-end loaded. Pismo Beach awarded a $39.8 million design-build contract after quarter-end, moving the company into advanced water purification. That project's construction does not begin until spring 2027. In Hawaii, the long-awaited State Historic Preservation Division and Department of Health approvals arrived, and a Limited Notice to Proceed released about $6 million for long-lead equipment. Management also quantified more than $150 million of unrecognized design and construction backlog, plus a 20-year O&M term. However, the construction start was guided to 'later this year' on three consecutive calls and has now slipped to the first half of 2027. It also remains contingent on the remaining permits. Bears have legitimate ammunition on execution timing. Manufacturing shows a similar pattern. The record $10.1 million Florida orders deliver in November 2027. About $10 million of bids are due in Q4, and roughly $45 million of Florida projects should go to bid within six months, but full-year 2026 manufacturing revenue is still expected to fall below 2025. Management explicitly framed all of this as setting up 2027, not the current year.
The balance sheet buys patience. Cash stands at $129.2 million with no debt, and contract liabilities rose to $14.2 million from $11.5 million at year-end. The CEO also firmed up M&A language, saying he hopes to announce an acquisition or expansion within the next year.
Investor sentiment has moved in the opposite direction from the reported numbers. It improved from slightly negative (-0.09) at the prior report to modestly positive (+0.20). That is a meaningful shift, and it suggests investors are leaning on the backlog narrative rather than the current run-rate. Price action has been less forgiving. Shares at $27.65 are down 10.7% since the open after the August report and sit about 11.7% below the 200-day moving average of $31.30. The Earnings Whispers price and AVWAP trend readings remain negative, consistent with a stock that has drifted lower through the year's erosion.
The bottom line is that this was a genuinely weak quarter. It featured an earnings and revenue miss, accelerating top-line decline, and a fourth straight quarter of margin compression, with the next leg of the story pushed into 2027 once again. The pipeline is real and arguably stronger than at any point this year, with Pismo, Florida, and a de-risked but still unstarted Hawaii project. The utility segments plus a debt-free balance sheet provide a floor. Until Hawaii construction actually begins and backlog converts into revenue, however, improving sentiment is running ahead of fundamentals that are still moving the wrong way.
Read our earnings preview for Consolidated Water Co. Ltd.: https://www.earningswhispers.com/article/CWCO/22691
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-12 | |
| Oct-01 | |
| Aug-20 | |
| Aug-12 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 | |
| Jul-22 |
