Lithium Argentina's Cash Machine Faces A Skeptical Market As Stage 2 Study Deadline Arrives
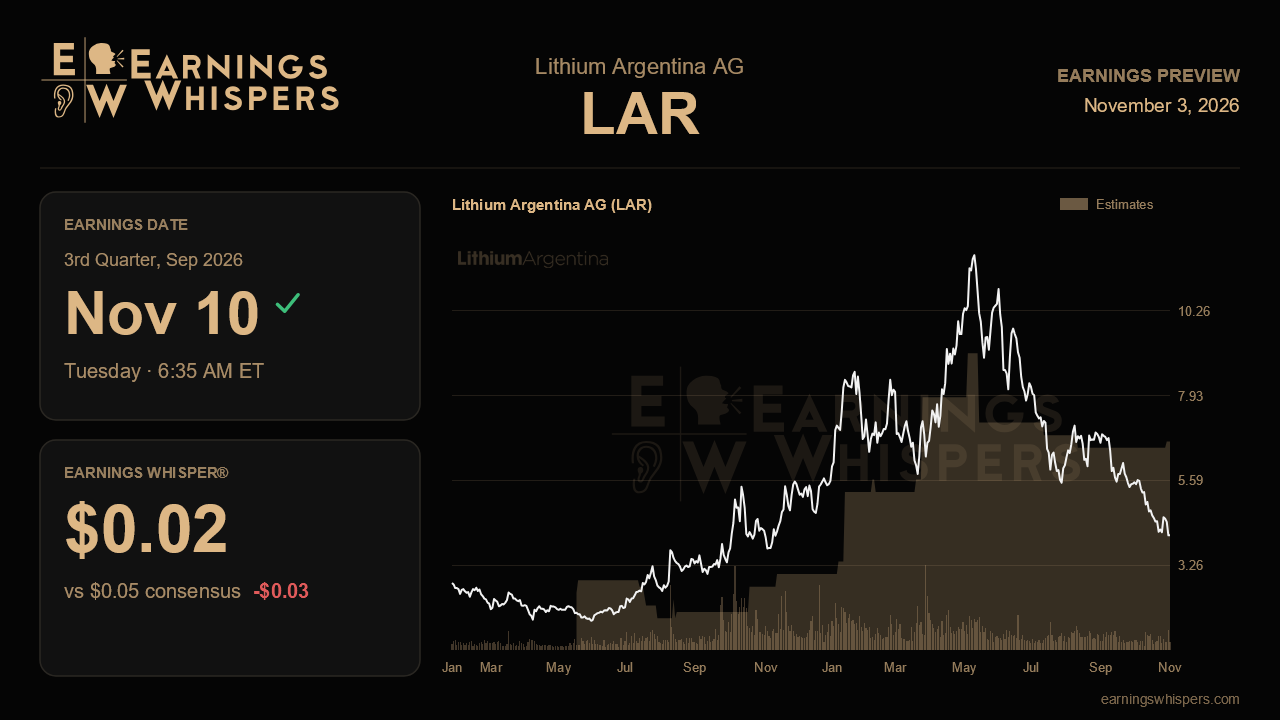
Few lithium stories looked better on paper last quarter than Lithium Argentina's. Realized prices at Cauchari-Olaroz had more than doubled in two quarters, cash operating margins hit 70%, joint venture debt fell by more than $100 million in a single quarter, and distributions to the company kept growing. The stock has dropped 38.6% since that report anyway, badly trailing a roughly flat S&P 500. The September-quarter results, due before the open on November 10, need to show whether the market is pricing in a turn that the operating numbers have not yet revealed.
The Street expects earnings of $0.05 per share. That compares with a loss of $0.02 a year ago and $0.01 last quarter, which makes this a sharp swing into profitability on paper. The whisper number sits at $0.02, below consensus. At these small per-share figures the gap is only a few cents, but it suggests that some traders expect a softer print than the published estimate. That lowers the bar slightly. Management has not issued new guidance since the last report, so the main reference points remain the reaffirmed 2026 production target of 35,000 to 40,000 tonnes and a long-term cost goal in the mid-$5,000s per tonne.
Pricing is the first test. Realized prices climbed from about $9,000 per tonne to roughly $17,000 and then to about $19,500 last quarter, and that rise drove adjusted EBITDA from $30 million to around $110 million. EBITDA grew only 4% sequentially even as prices kept rising, so operating leverage is already flattening. If realized prices merely hold, earnings should stay steady. Any slippage would show up quickly in margins. Costs matter here as well. Last quarter's increase was blamed on a planned shutdown, higher energy costs and a stronger peso. A return toward the sub-$5,400 level seen in the first quarter would support the idea that the increase was temporary. Another rise would point to inflation becoming structural.
Cash returns are the second leg of the bull case. Management indicated that second-half distributions should match or exceed the $160 million paid in the first half, of which the company's share was $75 million. With $220 million of new unsecured joint venture facilities closed at rates below 5%, further deleveraging and steady payouts would confirm that the balance sheet is no longer a constraint. Last quarter's $141 million of free cash flow was flattered by a working-capital drawdown, so a lower figure this time would not be alarming. A sharp drop in distributions would be.
The growth story faces an even more pointed check. Management pushed the Stage 2 scoping study from mid-year to around the end of the third quarter and described the delay as a matter of partner alignment. That deadline has now passed, and investors should expect either the study itself or a clear explanation. The modular approach to direct lithium extraction, starting with a 10,000-tonne first phase, along with the de-bottlenecking work meant to push Stage 1 past its 40,000-tonne nameplate, should show tangible progress. The pending RIGI approval for the PPG project, which management expected by year-end and which governs outside financing, is the other open item.
The tape is unforgiving. At $4.08, the shares sit far below their 200-day moving average of $7.32 and just above the post-earnings low of $3.94. The prior quarter's trading range topped out near $12. Sentiment has moved from bearish to moderately bullish, so some investors appear to see value in the selloff. Whether the narrative holds comes down to one question: can Cauchari-Olaroz keep turning high prices into growing cash distributions while Stage 2 finally moves from promise to plan? Steady pricing, contained costs and a delivered scoping study would challenge the market's skepticism. Another timeline slip would give the bears fresh ammunition.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-26 | |
| Oct-08 | |
| Sep-30 | |
| Sep-15 | |
| Aug-25 | |
| Aug-24 | |
| Aug-11 | |
| Aug-05 | |
| Jul-09 | |
| Jun-22 | |
| May-14 | |
| May-12 | |
| May-12 | |
| Apr-24 |
