Lithium Argentina Beats On Paper, But Falling Lithium Prices And A Defensive Stage 2 Reset The Story
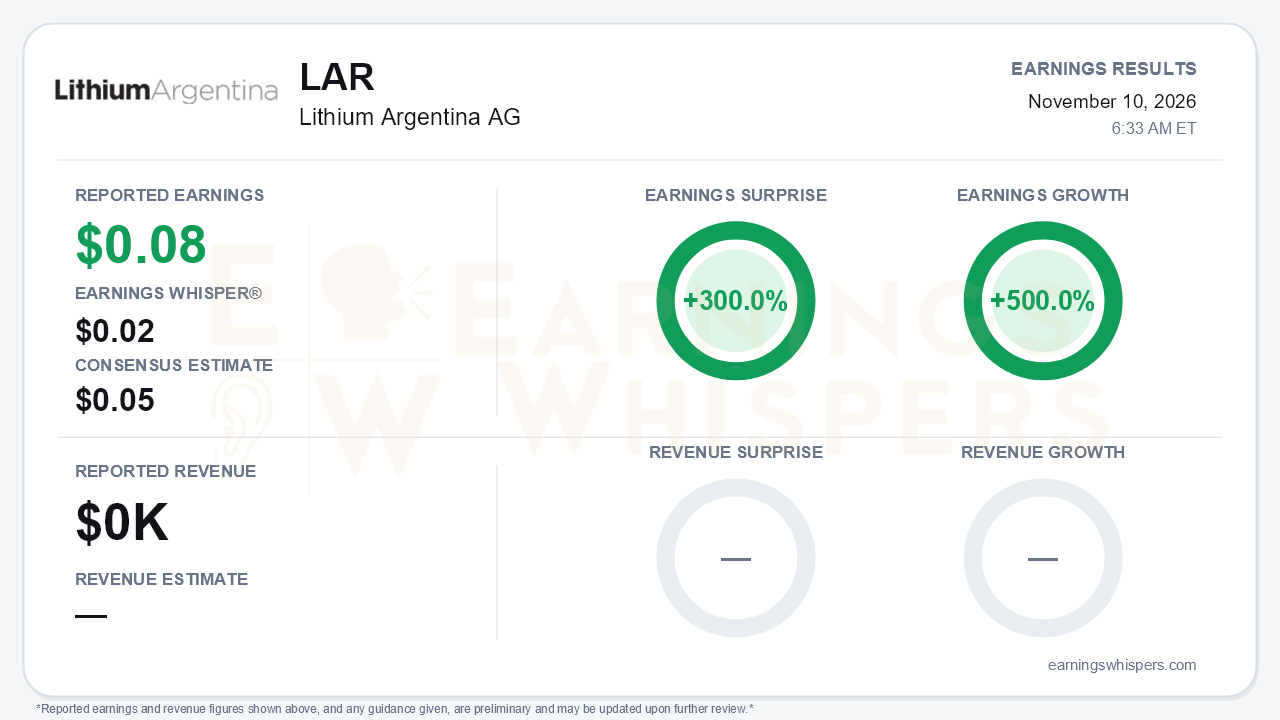
Lithium Argentina (NYSE: LAR) delivered a clean headline beat for the third quarter. It earned $0.08 per share against a $0.05 consensus and a far more skeptical $0.02 Earnings Whisper number, a 300.0% surprise. Earnings grew 500.0% from the prior-year quarter, when the company lost $0.40 per share, so the result marks a full swing from a $64.5 million loss to $13.0 million of net income. The company reports no consolidated revenue because it accounts for its 44.8% stake in Cauchari-Olaroz under the equity method. The operating story therefore sits at the joint-venture level, and there the message is less celebratory. Cauchari-Olaroz is running well, but the lithium price beneath it is moving the wrong way, and management's tone has shifted accordingly. That is the central tension.
The quality of the beat deserves scrutiny. The company's share of Cauchari-Olaroz income was $16.8 million. A $7.3 million fair-value gain on its convertible instruments added to net income and accounted for more than half of the bottom line. That gain is a non-operating item, and the company itself excludes it from adjusted measures. Underneath it, the corporate cost base worsened. Corporate Adjusted EBITDA was a loss of $6.1 million, compared with a $4.8 million loss a year ago. Corporate operating cash flow was negative $11.3 million. The prior-year comparison is also unusually soft, because it included $26.0 million of previously unrecognized 2024 losses and a $9.3 million charge on the JEMSE receivable.
At the asset level, the operation kept doing its job:
- **Volume:** Production rose 3% sequentially to 9,550 tonnes, about 95% of design capacity. Shipments jumped 18% to 10,488 tonnes, which lifted 100%-basis revenue 6% to $184 million.
- **Earnings:** Exar Adjusted EBITDA edged up to $113 million from $110 million.
- **Costs:** C1 cash costs eased slightly to $5,801 per tonne from $5,897 in Q2. They remain above the roughly $5,400 level of Q1 because of higher energy costs and a stronger peso.
Higher volume is masking weaker unit economics. The realized price fell about 10% to $17,580 per tonne, and the cash operating margin slipped to 67% from 70%. Free cash flow from operations dropped to $92 million from $141 million in Q2, and joint-venture net debt rose to $171 million from $142 million. Management expects Q4 pricing to be lower still.
The tone shift on the call matters more than any single metric. In Q1, management described an "extremely tight market," and in Q2 it spoke of "healthy growth." This quarter, the stance became cautious and data-dependent. Management cited a divided outlook for recovery and pressure on Chinese energy-storage demand from grid-connection fee policy. It also pointed to roughly 30% EBITDA margins at $10,000 per tonne, a stress-case framing that bulls would not have heard two quarters ago.
Stage 2 shows the same caution. The scoping study is attractive on paper: a $3.1 billion after-tax NPV, a 28.5% IRR at $18,000 per tonne, and capacity of about 85,000 tonnes per annum. In practice, management is starting with only a 10,000-tonne modular DLE first phase targeting 2028. It explicitly noted that the market may not support the full 45,000-tonne build. That first phase also depends on a Chinese technology export permit and on Ganfeng's approval.
There is one small conflict between the two sources. The release says ASX listing plans are still advancing, but the listing reportedly went unmentioned on the call.
The balance sheet, by contrast, was meaningfully de-risked:
- Ganfeng's $180 million, 4% six-year convertible debenture funded an October repurchase of $200 million of the January 2027 notes for about $198 million. Roughly $59 million remains, to be repaid from more than $100 million of cash.
- Joint-venture distributions reached $230 million year to date.
- The PPG joint venture closed, with RIGI approval expected by year-end and talks on a minority-stake sale or offtake described as advanced.
- Full-year production guidance of 35,000 to 40,000 tonnes was held. Q4 output is expected above 9,000 tonnes, which keeps the company on track for at least the midpoint.
The trade-off is deeper reliance on Ganfeng. Its debenture converts at $12.50, nearly triple the current share price.
The market setup is more complicated than the surprise implies. Investor sentiment swung sharply, from -0.31 before the prior report to +0.39, a genuine shift toward optimism. Price action tells a harsher story. As of the pre-report snapshot, shares sat at $4.44, down 33.1% since the open following the August report. That leaves them 38.5% below the $7.21 200-day moving average and nearly 39% below the late-August high of $7.27. The stock is only about 13% above the $3.92 inter-earnings low set on November 5. The Earnings Whispers trend signals remain mostly negative, with only momentum reading positive.
The bottom line is that Lithium Argentina owns a low-cost, cash-generative asset and has cleaned up its near-term debt profile. However, this quarter's beat leaned on a non-cash gain, and the operating trend is being carried by volume against a falling price. Management's own retreat from tight-market rhetoric, along with its scaled-back Stage 2 plan, signals that pricing, not execution, now drives the outlook. Bears have legitimate ammunition until realized prices stabilize.
Read our earnings preview for Lithium Argentina AG: https://www.earningswhispers.com/article/LAR/22699
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 9 hours | |
| Nov-03 | |
| Oct-26 | |
| Oct-08 | |
| Sep-30 | |
| Sep-15 | |
| Aug-25 | |
| Aug-24 | |
| Aug-11 | |
| Aug-05 | |
| Jul-09 | |
| Jun-22 | |
| May-14 | |
| May-12 |
