Venture Global's Q3 Test: Can Record EBITDA Hold Through Summer After Three Guidance Raises?
Venture Global heads into its third-quarter report with a problem most companies would envy: management has raised its 2026 EBITDA outlook three times in a row, and the stock has done little to reflect it. The quarter now has to show that the record second quarter was a new baseline rather than a peak. Investors also need to see whether a business that is 91% contracted for the year can keep delivering through the hot summer months, when liquefaction output typically softens.
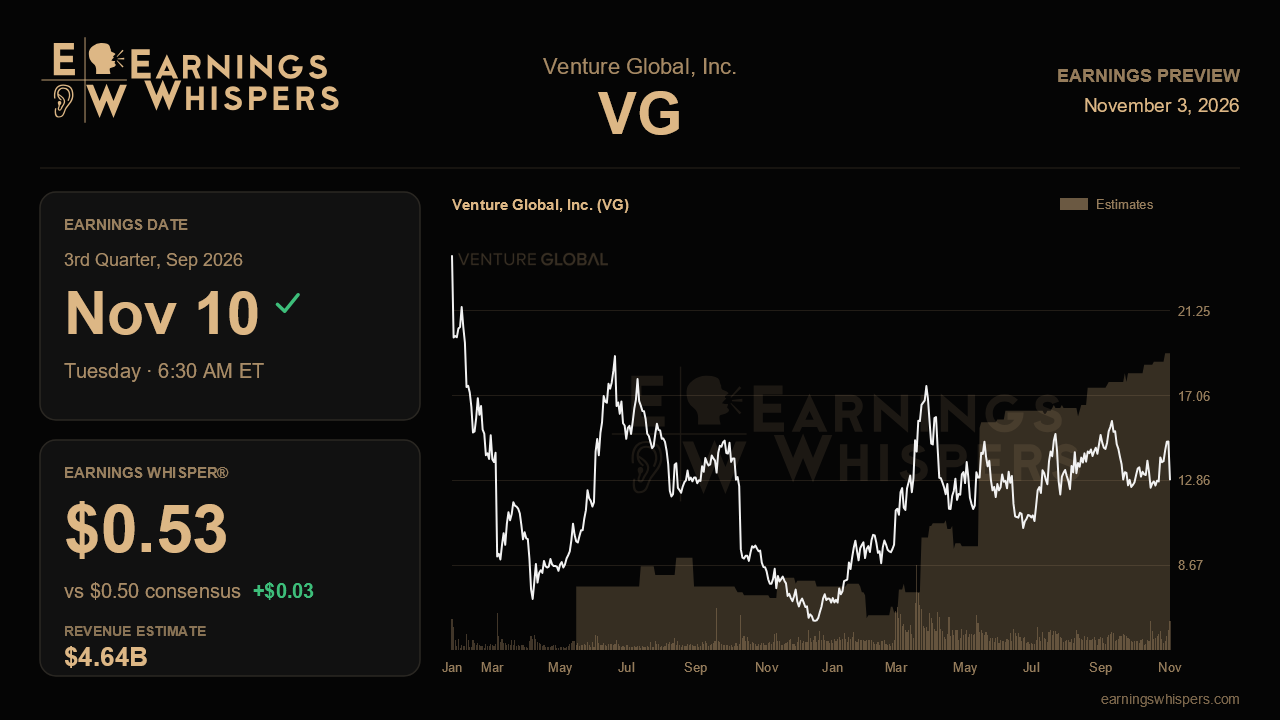
Wall Street expects earnings of $0.50 per share on revenue of about $4.64 billion when the company reports before the open on November 10. That would more than triple the $0.16 earned a year ago and lift revenue roughly 39% from $3.33 billion, which is strong growth by any measure. Sequentially, though, the bar is essentially flat against the $0.51 and $4.58 billion posted last quarter. The Earnings Whisper of $0.53 sits a few cents above consensus. That points to a modestly higher informal bar, but not one that demands a blowout.
The guidance math frames the quarter well. After $1.4 billion of adjusted EBITDA in the first quarter and a record $2.5 billion in the second, the full-year range of $8.7 billion to $9.1 billion implies roughly $4.8 billion to $5.2 billion over the back half. That works out to about $2.4 billion to $2.6 billion per quarter, or roughly a repeat of the second quarter. A third-quarter EBITDA print near $2.5 billion, with margins holding in the vicinity of the 54% reached last quarter, would validate the raised outlook. A meaningful shortfall would put pressure on the fourth quarter, which carries its own swing factors, including the expected commercial operation of Plaquemines. Management deliberately kept the range wider than usual because of Middle East-driven LNG price volatility. Because only about 9% of the year remains exposed and the sensitivity to a $1 move in liquefaction fees has shrunk to $180 million to $210 million, volatility should matter less than execution and cargo volumes.
Beyond the numbers, several threads from the last call deserve follow-up. Interest savings of more than $100 million a year from over $5.3 billion of refinancing should begin flowing through below the EBITDA line, and that helps explain the steep EPS growth. Any progress toward the anticipated credit-rating upgrades, an update on Plaquemines COD timing, and confirmation that the Plaquemines Phase 1 bolt-on and the 10 MTPA CP2 expansion remain on track for 2027 decisions would reinforce the growth narrative. The newly signaled buyback deserves attention too. A concrete authorization would mark the shift from capital consumer to capital returner. The Calcasieu Pass arbitrations, with the BP hearing set for late November, remain the main overhang, though the reserve runs only about $14 million to $15 million a quarter. Watch also whether the uptick in shorter-term contracting interest management mentioned has grown into a lasting change in customer behavior.
The market's mood has cooled. Sentiment registers 19% bullish, down from 31.1% ahead of the last report, and the shares have slipped 2.1% since then, only slightly better than the S&P 500. At $12.87, the stock sits just above its 200-day average of $12.70 and in the lower third of its post-earnings range of $11.76 to $16.30. Investors appear to have faded the late-summer enthusiasm despite the improving fundamentals.
That gap between momentum and price defines the setup. The question is simple. Can Venture Global show in a seasonally tougher quarter that its second-quarter earnings power is repeatable, with EBITDA tracking toward the guided range and Plaquemines on course for its fourth-quarter milestone? If so, the raised outlook looks conservative, and the subdued sentiment could leave room for a rerating. If not, three straight raises may start to look like a ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Nov-01 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-06 | |
| Oct-06 |
