Venture Global Beats And Raises 2026 EBITDA Again, But A 2027 Margin Reset And An Unproven AI Pivot Keep Shares Near Their Lows
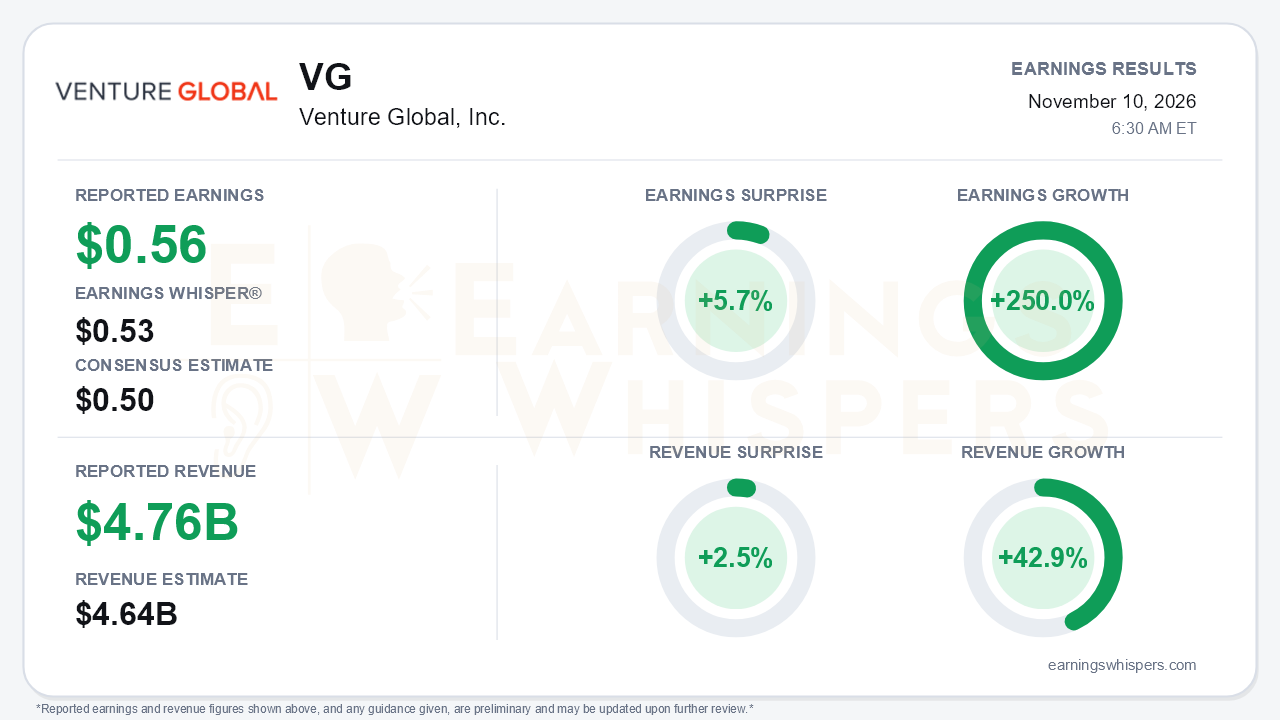
Venture Global delivered another quarter in which execution outran expectations. Earnings came in at $0.56 per share against a $0.50 consensus and a $0.53 Earnings Whisper number, a 5.7% beat. Revenue of $4.756 billion topped the $4.64 billion consensus by 2.5%. Earnings grew 250.0% year over year and revenue rose 42.9%, with Consolidated Adjusted EBITDA reaching a record $2.6 billion, up 69%. Management raised full-year 2026 EBITDA guidance for the fourth straight quarter, to $10.0-$10.3 billion from $8.7-$9.1 billion. That nearly doubles the $5.2-$5.8 billion midpoint the company started the year with. The central tension is that 2026 increasingly looks like a peak-pricing year. The stock is trading as if investors care more about what comes after it.
The quality of the quarter needs some unpacking. GAAP diluted EPS was $0.96, and net income attributable to common stockholders jumped 493% to $2.5 billion. However, $1.37 billion of that came from a non-cash gain on interest rate swaps, which flattered the bottom line well beyond operations. The operating picture was still strong on its own terms. Income from operations rose 74% to $2.3 billion, and cost of sales grew only 26% against 43% revenue growth. Exported cargos rose to 124 from 100, and realized pricing improved to $10.16/MMBtu from $8.92 a year earlier. Much of the volume came from Plaquemines commissioning cargos sold into elevated spot markets tied to Middle East supply disruption. That supports the headline, but it is not a recurring earnings base.
On the call, the operating narrative stayed firmly positive:
- Plaquemines Phase 1 reached commercial operations on October 31, roughly 53 months after FID, and six SPA cargos have already loaded.
- CP2 first LNG was pulled forward to mid-2027, or July per the call, about 24 months from FID. The previous language was simply "second half 2027."
- 2026 volumes are now more than 99% contracted, up from 69% at the start of the year, and the low end of the cargo range rose by nine.
- Commercial momentum continued with a new 1 MTPA ConocoPhillips SPA, 0.5 MTPA with China Gas, and a 0.5 MTPA upsizing from an existing customer. Management described long-term contracting demand as stronger than ever, with Asia leading.
The forward-looking caveats matter more for the stock. Management did not raise the 2027 cargo outlook of 575-625 and framed CP2's 2027 contribution at only 10-20 cargos. The CFO warned of 2027 margin dilution as Plaquemines Phase 1 cargos roll from commissioning sales onto long-term SPAs at a weighted liquefaction fee of about $6.46/MMBtu. That compares with the $21-$22/MMBtu assumed for the few remaining unsold 2026 cargos. Plaquemines gas basis constraints, CP2 startup costs and AI development spending add to that pressure. The CEO's claim that cumulative 2027-2029 EBITDA will likely exceed $30 billion implies an average roughly in line with this year's raised guidance, not a step-up from it. Meanwhile the balance sheet keeps levering up. Total debt is now about $44.6 billion, and quarterly interest expense rose to $486 million.
The new island-mode AI utility is the quarter's biggest strategic swing. The plan rests on GE Vernova and Baker Hughes frame agreements for up to 16 power islands of 720 MW each. Management targets first compute capacity in late 2028 and about 5 GW by 2031. It leverages real assets: land, pipeline access, existing power and an in-house EPC team. But there are no signed customers, analysts flagged widening financing costs for uncontracted projects, and the venture moves a capital-hungry LNG developer into an unfamiliar business. Bulls see optionality; bears have legitimate ammunition on capital allocation.
The market had already been leaning skeptical. Shares at $11.80 are down 10.3% since the open following the August report and sit 7.7% below the 200-day moving average of $12.78. They are 27.6% below the September high of $16.30 and only 5.2% above the inter-earnings low set the day before the report. Investor sentiment remained positive but weakened noticeably, falling from 0.31 to 0.20. Earnings Whispers trend readings show positive sequential growth and momentum, but the AVWAP trend is negative, consistent with sellers controlling price despite improving reported numbers.
The bottom line is that Venture Global beat expectations, raised guidance again and hit key project milestones ahead of schedule, so execution is not the issue. The issue is durability. Swap gains and spot-driven commissioning cargos inflated 2026, 2027 margins are already flagged to compress, and the AI utility adds a speculative, capital-intensive layer. The stock's slide toward its lows suggests investors want proof that earnings can hold up once the price windfall fades.
Read our earnings preview for Venture Global, Inc.: https://www.earningswhispers.com/article/VG/22713
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 10 hours | |
| 12 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Nov-01 | |
| Oct-19 | |
| Oct-16 |
