TransDigm's Fiscal 2027 Outlook Must Rebuild Trust After Four Raises And A Slide
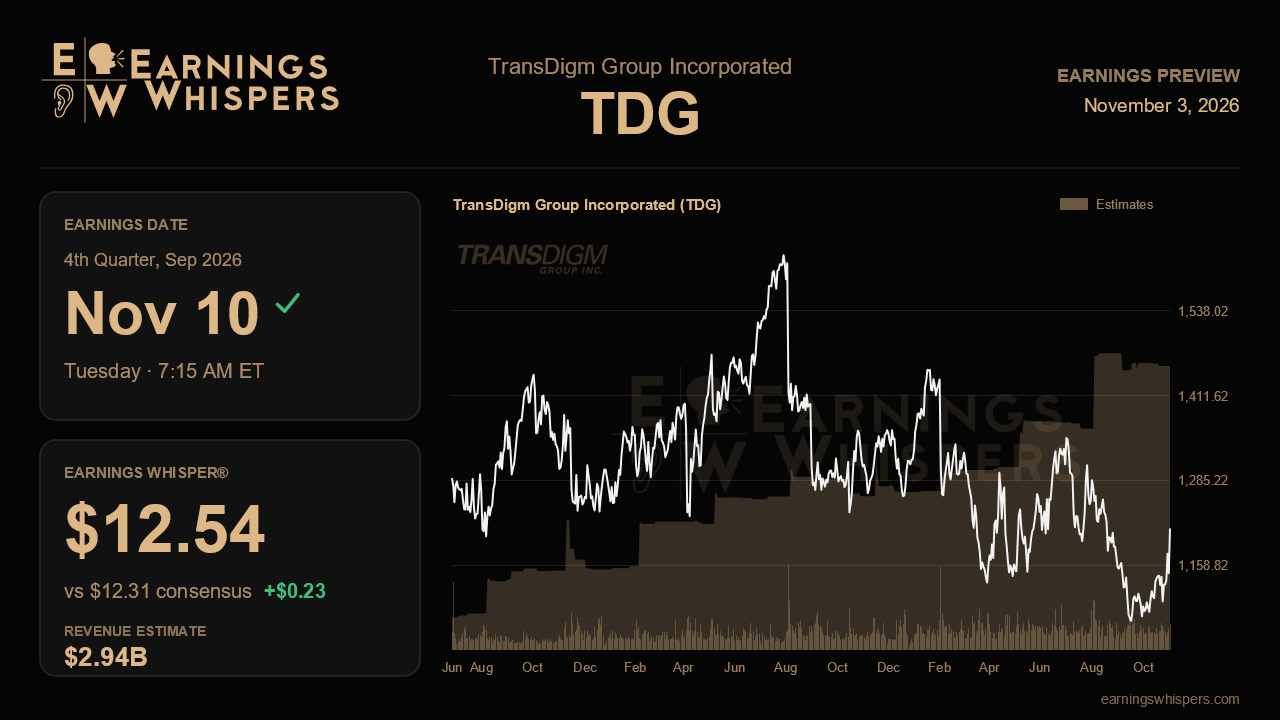
TransDigm heads into its fiscal fourth-quarter report with a split personality. Operationally, the aircraft parts maker has raised its full-year outlook four times running, and every end market it serves accelerated last quarter. The stock, however, has slid 10.5% since that report, trailing the S&P 500 by more than nine percentage points. The November 10 release, due before the open, has to settle which story is right. It also matters for another reason: the November report is where management laid out last year's first look at fiscal 2026, so investors should expect an initial fiscal 2027 framework alongside the quarter.
For the September quarter, analysts are looking for non-GAAP earnings of $12.31 per share on revenue of about $2.94 billion. That revenue figure implies growth of roughly 21% from $2.44 billion a year ago and a healthy step up from the $2.74 billion posted last quarter. Earnings would rise about 18% from $10.47. The Earnings Whisper of $12.54 sits around 2% above consensus. That gap is not huge, but it tells you the informal bar is a clean beat, not a merely in-line print. Management's raised full-year outlook calls for $40.62 to $41.46 in adjusted EPS on revenue of $10.47 billion to $10.55 billion. When that guidance came out, the Street's full-year estimate of $40.04 sat below even the low end of the range, a sign the company had moved ahead of analysts rather than the other way around.
The key test is whether last quarter's acceleration was durable or a peak. Commercial transport aftermarket revenue jumped 18% year over year. Management lifted its aftermarket expectation in steps, from high single digits early in the year to low double digits. Distributor point-of-sale data also grew by double digits, suggesting the destocking drag that hurt fiscal 2025 has faded. Aftermarket is TransDigm's highest-margin business, so sustained double-digit growth here would do more to validate the bull case than anything else. The risk management flagged is the Middle East conflict, which has pushed up jet fuel prices and softened passenger traffic. Executives said they had seen no material aftermarket impact so far. Any sign that traffic pressure is reaching spare-parts orders would undercut the narrative quickly.
The other engines need to keep running too. Commercial OEM revenue grew 25% on Boeing and Airbus rate increases, with bookings outpacing shipments. Defense grew 11% with a building backlog. Continued positive book-to-bill in both would support a confident fiscal 2027 guide. Margins deserve close attention. The EBITDA-defined margin rose each quarter, reaching 52.8%, despite more than two points of dilution from acquisitions, including roughly half a point from JetParts and Victor Sierra. Holding that line would show the pricing and cost discipline TransDigm is known for remains intact as newer, lower-margin businesses are folded in.
Capital deployment adds another layer. The DOJ-forced withdrawal of the Stellent deal was the lone setback last quarter, and management quickly replaced it with the roughly $1.1 billion Princeton IZANT acquisition. Updates on that deal's progress, the outlook for regulatory scrutiny on future purchases, and the evolving defense right-to-repair proposal will all shape how much growth investors credit to M&A. Leverage edged up to 5.8 times net debt to EBITDA, which leaves less room for error if the cycle softens. The company also cited more than $10 billion of acquisition firepower and $1.8 billion in buybacks year to date.
Sentiment has clearly cooled. Bearish readings have roughly doubled from a quarter ago, and the stock sits just below its 200-day moving average, well off its post-earnings low of $1,071 but far from the $1,359 high. That combination of strong fundamentals and a skeptical market creates a real opportunity, but only if management delivers. The report will hinge on whether TransDigm can pair another solid quarter with a fiscal 2027 outlook showing aftermarket strength and margin resilience will outlast the macro worries now weighing on the shares.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-02 | |
| Oct-30 | |
| Sep-29 | |
| Sep-28 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-09 | |
| Aug-19 | |
| Aug-10 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 |
