TransDigm Finishes FY26 At Peak Momentum, But Misses The Whisper And Guides To Slower Organic Growth In Every Channel
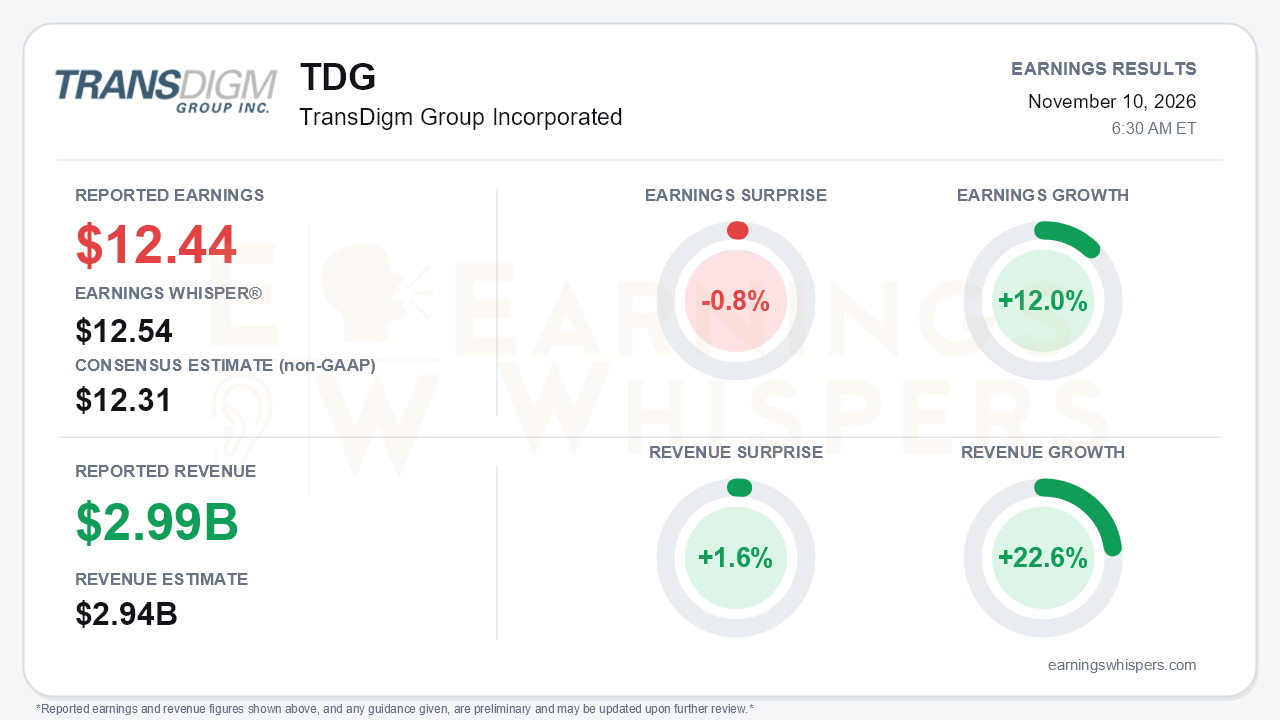
TransDigm closed fiscal 2026 with its strongest quarter of the year, yet the report still fell short of what investors were looking for. Adjusted earnings of $12.44 per share topped the $12.31 consensus but missed the $12.54 Earnings Whisper number by 0.8%. Revenue of $2.988 billion beat the $2.94 billion consensus by 1.6% and grew 22.6% year over year. Earnings Whispers measures earnings growth at 12.0%, in line with the 12% rise in adjusted net income; the company cites 15% growth in adjusted EPS. The central tension is plain. Fiscal 2026 ended with organic growth still accelerating, but the initial fiscal 2027 outlook assumes deceleration across all three end markets. That makes this a story of solid momentum that is no longer building.
The quality of the quarter deserves a closer look. Operationally, the trajectory was clean:
- **Organic growth** reached about 14%, up from 13% in Q3, 11% in Q2 and 7.4% in Q1.
- **EBITDA As Defined margin** reached 53.0%, the year's high, after rising every quarter from 52.4%.
- **Revenue and EBITDA As Defined** cleared the high end of guidance that had already been raised three times.
- **Free cash flow** came in near $2.8 billion against a $2.6 billion target.
Below the operating line, the picture is less flattering. GAAP net income fell 4% to $586 million because net interest expense jumped to $536 million from $420 million and taxes rose. GAAP EPS climbed 33% to $10.33, but that gain mostly reflects last year's $2.75 per share hit from dividend equivalent payments, not underlying improvement. Year over year, margin slipped from 54.2%, with roughly two points of dilution from acquisitions. Adjustments to EBITDA also nearly tripled to $147 million, driven by integration costs, refinancing charges and other items. That widens the gap between adjusted and reported results.
The call showed demand that remains healthy across the business:
- **Commercial aftermarket** grew 17% in the quarter and 14% for the year, up from 7% in Q1.
- **Defense** grew 12%, its third straight double-digit quarter.
- **Bookings** outpaced sales in both commercial aftermarket and OEM.
- **New business** had its best quarter of the year, including GPS anti-jam orders, about $120 million in Calspan engine test cell awards, and NATO aerial delivery contracts.
The fiscal 2027 guide is where the narrative shifts. Management called for:
- Revenue of $11.95 billion to $12.15 billion, up 14% at the midpoint.
- Adjusted EPS of $47.09 to $47.94.
- EBITDA As Defined of about $6.27 billion.
- Free cash flow near $2.9 billion.
The headline growth is respectable, but it leans on acquisitions, including the roughly $1.07 billion Prince & Izant deal. The channel assumptions all step down from fiscal 2026 actuals. Commercial aftermarket is guided to high single digits versus 14%. Commercial OEM is guided to high single to low double digits versus about 15%. Defense is guided to high single digits versus 10%. Management tied part of the aftermarket slowdown to softer passenger traffic (RPKs) amid elevated oil prices and Middle East tension. Fiscal 2026 traffic already came in below the original forecast. The consolidated margin guide of about 52% sits below this year's 52.7%, even as management reiterated 100 to 150 basis points of annual margin expansion in the base business.
The balance sheet is the other pressure point, and bears have legitimate ammunition here:
- Long-term debt rose to $33.7 billion.
- Leverage edged up to 5.9x.
- The company's average interest rate is expected to rise to about 6.5% from 6.1%, lifting fiscal 2027 net interest expense to roughly $2.255 billion.
- The CFO signaled a more conservative stance on capital deployment given debt-market volatility.
On the other side, management expects leverage to fall below 5x by the end of fiscal 2027 and cites M&A capacity above $10 billion. Capital spending rises about $100 million to roughly $380 million to fund automation and AI-driven productivity projects. Management also put a number on its right-to-repair exposure, estimating it at less than 1% of sales. Supply-chain watch items include printed wiring boards and the transition away from Chinese rare earths.
The market setup is more complicated than a revenue beat implies. Investor sentiment, measured before the report, deteriorated meaningfully, from -0.25 to about -0.48. Shares fell 10.1% from the open after the August report and hit a 52-week low of $1,071.25 in mid-September. They have since rebounded about 14% to $1,218.85, essentially at the 200-day moving average of $1,220.33. Management bought back $943 million of stock in the quarter at an average of $1,150, close to current levels, arguing the shares offered at least a 20% internal rate of return. The Earnings Whispers momentum and AVWAP trend readings have turned positive, while the price trend remains neutral, consistent with a stock that has stabilized but not decisively recovered.
The bottom line is that TransDigm delivered an operationally strong finish, with accelerating organic growth, sequential margin gains and cash flow above plan. It narrowly missed the whisper, however, and guided to a year of slower organic growth, thinner consolidated margins and higher interest costs. With sentiment already souring and shares sitting right at their 200-day average, the debate shifts from how fast TransDigm is accelerating to whether acquisitions, buybacks and deleveraging can offset a cooling core growth rate.
Read our earnings preview for TransDigm Group Incorporated: https://www.earningswhispers.com/article/TDG/22711
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Sep-29 | |
| Sep-28 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-09 | |
| Aug-19 |
