Columbus McKinnon Clears A Low Bar And Raises Guidance Again, But Cash Flow And Leverage Keep The Stock On Probation
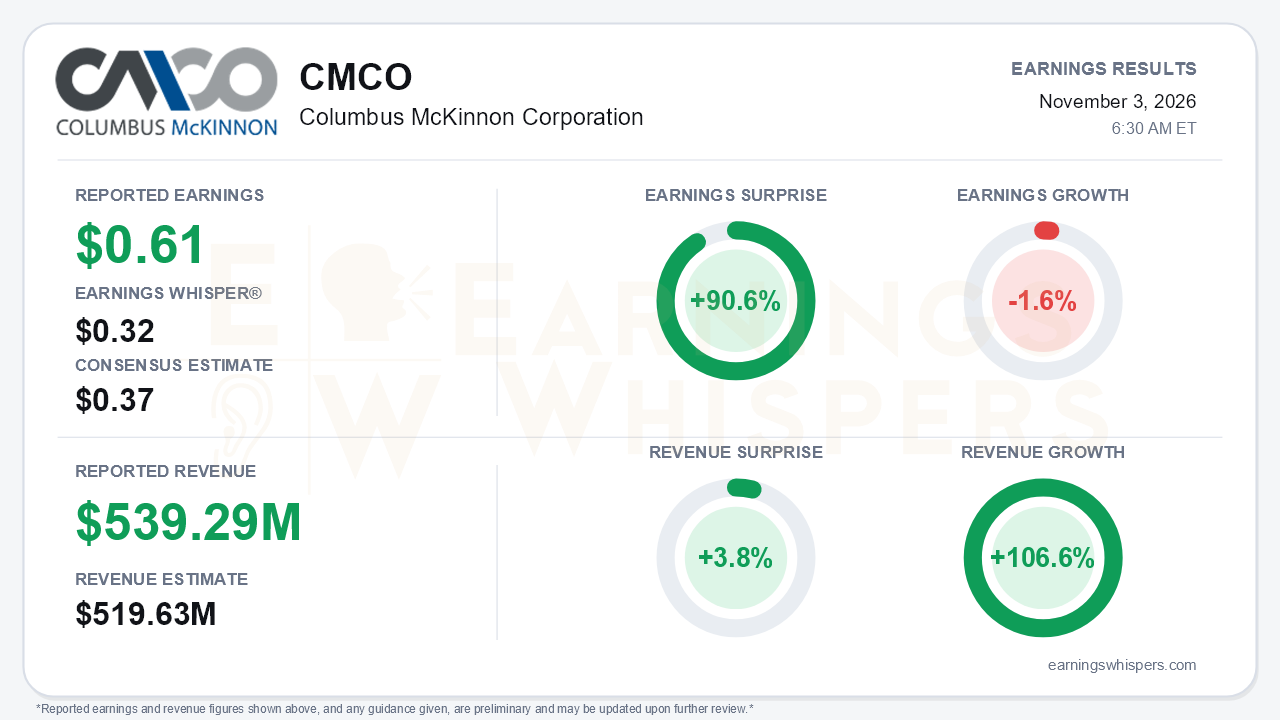
Columbus McKinnon delivered a quarter that looks emphatic against expectations and far more ordinary against its own history. Adjusted EPS of $0.61 beat the $0.37 consensus by 90.6% and cleared the more cautious $0.32 Earnings Whisper number. Revenue of $539.29 million topped the $519.63 million consensus by 3.8% and grew 106.6% year over year, almost entirely because of the Kito Crosby acquisition that closed in February. Yet adjusted EPS fell 1.6% from a year ago. Management had framed Q2 as the low point of the year, and the Street set its bar accordingly. That leaves the central tension: the beat is real, but it was measured against depressed expectations for a company now carrying roughly $2.4 billion of debt.
The quality of the quarter is mixed. Adjusted EBITDA rose to $111.2 million, and the 20.6% margin was up 520 basis points on a reported basis and about 130 basis points pro forma. Adjusted gross margin improved 120 basis points to 36.5%. That margin held up without the tariff-refund benefit that flattered Q1, which is a meaningful positive.
The acquisition's financing cost shows up lower in the income statement. Interest expense jumped to $48.1 million from $8.7 million. Adjusted diluted shares rose to about 51 million from 28.9 million once the convertible preferred is included. On a GAAP basis, the company lost $25.5 million, or $0.76 per share. That loss included $12.5 million of acquisition and integration costs, $30 million of intangible amortization and a $15.3 million tax expense on a pre-tax loss. A roughly $5 million high-margin APAC project pulled into Q2 also helped the margin print.
Beneath the headline, the top-line trajectory softened while orders strengthened. Legacy CMCO sales grew 5.3%, against 8.8% for the first half. Pro forma sales growth slowed to 6.6% from 10% in Q1, and book-to-bill eased to 1.0x from 1.1x. Volume added only 1.0% in the sales bridge, with pricing doing most of the work at roughly 4 points. That is well above the 1-2% full-year price contribution expected at Q1, but it also signals that inflation in materials and diesel persists.
Orders, however, topped $560 million for a second straight quarter, and pro forma order growth accelerated to about 13% from about 9%. Part of that came from a roughly $23 million Saudi energy order that will mostly ship in fiscal 2028. Even excluding that order, EMEA grew at a high-single-digit rate. The region turned modestly positive after being described as soft in prior quarters, helped by energy, defense and infrastructure. APAC orders declined after customers pulled purchases forward ahead of a July price increase.
Guidance moved higher for the second consecutive quarter:
- **Net sales:** now $2.13-$2.17 billion
- **Adjusted EBITDA:** now $425-$440 million
- **Adjusted EPS:** now $2.00-$2.15, versus $1.70-$1.90 at the start of the year
The implied second-half EBITDA margin rose to about 19.7% from about 18.9% implied after Q1. Even so, the raise landed broadly in line with Street estimates rather than above them, so it validates the outlook more than it resets it. Other potential tailwinds sit outside the numbers:
- Data center demand, which management called out explicitly
- Early cross-selling between the CMCO and Kito Crosby portfolios, described as upside not included in guidance
- A credit-facility repricing worth more than $7 million in annual interest savings
Bears still have legitimate ammunition, and most of it is on the balance sheet. Free cash flow was negative $15.4 million in the quarter, leaving just $4.6 million year to date because of a working capital build. Net leverage stands at 4.9x, down from 5.1x at fiscal year-end. Liquidity slipped to $532 million from $567 million. The 4x target by the end of fiscal 2028 depends on second-half cash conversion that has not yet shown up.
The market has treated the stock harshly. Shares are down 21.1% since the open after the July report, at $15.76. That is 29.3% below the August 6 inter-earnings high of $22.29 and 4.6% under the 200-day average. The stock has rebounded 19.3% from its October 23 low of $13.21. Investor sentiment entered the report slightly more negative than after the prior quarter, slipping to -0.21 from -0.18, a modest change. The Earnings Whispers trend readings are mixed, with price and AVWAP trends negative while momentum is positive.
The bottom line is that Columbus McKinnon's operating story improved more than its stock price suggests. Margins held without one-time help, orders accelerated, and guidance rose again. But decelerating pro forma sales, a price-heavy growth mix and weak cash generation keep the deleveraging thesis unproven. Until second-half free cash flow arrives, the large EPS beat will likely matter less to investors than the 4.9x leverage ratio.
Read our earnings preview for Columbus McKinnon Corporation: https://www.earningswhispers.com/article/CMCO/21467
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-20 | |
| Sep-22 | |
| Sep-22 | |
| Sep-14 | |
| Sep-01 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
