Angel Studios Faces Young Washington Test As Street Bets On Near-Doubling Of Revenue
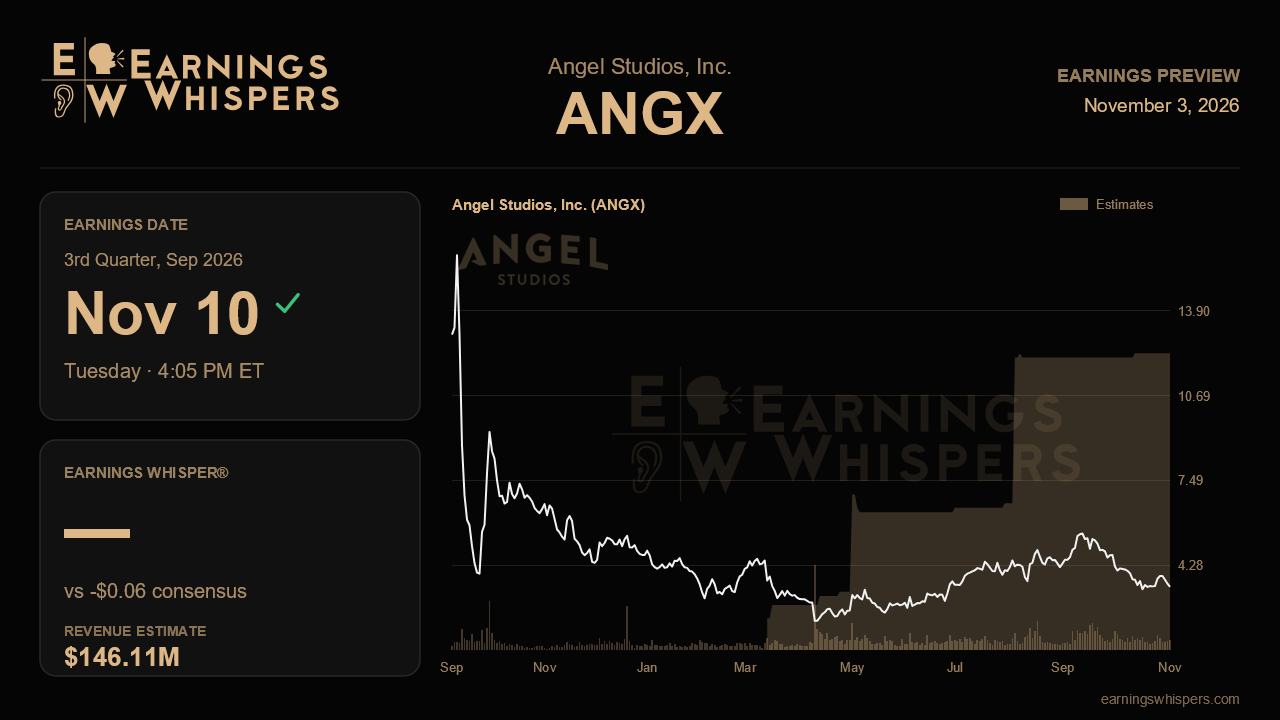
Angel Studios enters its third-quarter report with an unusual combination: Wall Street expects revenue to nearly double, management has drawn a firm line under full-year losses, and the stock has still drifted toward the bottom of its post-earnings range. The quarter that captures the July 4 release of Young Washington, the centerpiece of the company's America 250 push, should show whether last quarter's efficiency story can hold up when the theatrical slate gets busy again.
Consensus calls for a loss of $0.06 per share on revenue of about $146.1 million, after the company reported Monday, November 10, after the close. That compares with a loss of $0.25 and revenue of $76.5 million a year ago, implying roughly 91% top-line growth and a 76% improvement in per-share losses. It is also a sizable sequential step up from the $111.7 million and $0.13 loss posted last quarter. With a film that management pegged at roughly $46 million to $47 million at the box office landing in the period, the revenue bar looks reachable, but it leaves less room for any shortfall in Guild subscriptions.
The more important yardstick is the adjusted EBITDA cap management introduced last quarter: a full-year loss of no more than $25 million. Because the first half came in at a loss of only $7.7 million, the company can technically absorb about $17 million of second-half losses and still hit its target. The catch is that the first half benefited from easier comparisons, while management itself warned that August could be a slower growth month and that six of ten planned theatrical releases still sat in the back half. A third-quarter EBITDA figure that keeps the company comfortably on pace would validate the new, more disciplined posture. A loss that eats most of the remaining cushion would make the fourth quarter a high-wire act.
Mix is the swing factor for margins. Gross margin fell to 54% last quarter from 69% a year earlier largely because theatrical and distribution revenue shrank to 16% of sales from 45% in the King of Kings quarter. Young Washington should push that share back up, so a gross margin recovery is the natural expectation. If margins stay depressed despite a meaningful theatrical contribution, that would suggest the compression is more structural than management described. On the Guild side, membership had reached 2.85 million by July 31, nearly double the prior year, while sales and marketing spending held roughly flat in dollars. The key questions are whether marketing intensity stays near the low-50% range of Guild revenue, whether deferred revenue keeps climbing from $83 million, and whether average revenue per member, which slipped to $13.63 on discounted annual America 250 signups, stabilizes rather than eroding further.
The market has not been generous. Shares have fallen about 15.6% since the last report, trailing the S&P 500 by more than 12 percentage points, and at $3.46 they sit below the 200-day moving average of $3.68 and within about 5% of the post-earnings low of $3.31, far from the $5.75 high. Sentiment has warmed modestly from the prior quarter but remains only mildly positive. Pending dilution of roughly 10 million shares tied to the Toothy Cow and Tuttle Twins acquisitions, along with talk of a possible capital raise in 2027 or later, likely explains some of the caution.
Ultimately, the report comes down to whether Angel can show that its slower-spending growth model survives a big theatrical quarter and a seasonally softer summer. Strong Guild additions, recovering gross margin and an EBITDA loss that leaves ample room under the $25 million cap would reinforce the efficiency inflection. Anything that makes that cap look tight would revive doubts the stock price already seems to reflect.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-29 | |
| Oct-22 | |
| Oct-14 | |
| Sep-15 | |
| Sep-03 | |
| Aug-12 | |
| Aug-04 | |
| Jul-14 | |
| Jul-02 | |
| Jun-23 | |
| Jun-11 | |
| May-11 | |
| May-07 | |
| May-02 |
