Angel Studios Doubles Revenue On A Theatrical Hit, But A Slower Guild Engine And Unraised Guidance Temper The Inflection Story
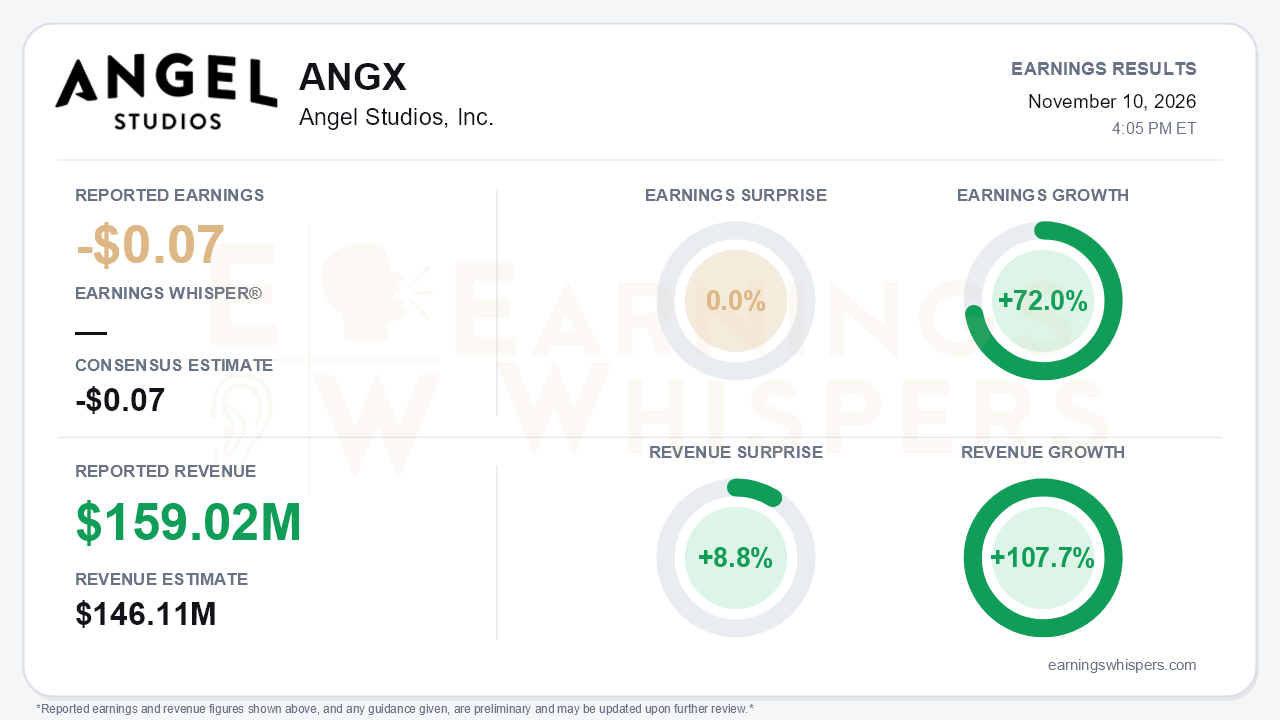
Angel Studios delivered its biggest quarter yet. Revenue more than doubled, up 107.7% to $159.02 million, and beat the $146.11 million consensus by 8.8%. On the bottom line, the company posted a loss of $0.07 per share on Earnings Whispers' normalized basis, exactly matching consensus, which was still a 72.0% year-over-year improvement. Investors should note that the release itself shows a GAAP net loss of just $0.03 per share, or $5.2 million, versus $38.5 million a year ago. That GAAP figure was flattered by a $7.6 million gain on the company's 304 bitcoin. The headline is a top-line blowout with in-line earnings. The central tension is that much of the upside came from a theatrical hit, while the subscription engine that underpins the long-term thesis showed its first real signs of cooling.
The quality of the beat deserves scrutiny. Young Washington grossed $47 million domestically and pushed theatrical release revenue to $29.0 million, up from $5.5 million a year earlier. Non-Guild revenue roughly doubled sequentially to $43.4 million. That richer mix lifted gross margin to 63%, from 54% in Q2 and 55% a year ago. As a result, Guild revenue fell to 72.7% of total, from 81.2% last quarter.
The improvement is real:
- Operating loss narrowed to $10.3 million from $38.0 million.
- The adjusted EBITDA loss shrank to $3.2 million from $32.6 million.
- Operating cash flow was positive $10.3 million, aided by deferred revenue climbing to $98.5 million on prepaid annual memberships.
But a hit-driven margin is less repeatable than a subscription-driven one. Management also signaled that theatrical releases are capped at roughly 12 a year and expected to taper, which implies less of this high-margin mix over time.
The Guild itself was solid but slowing. Guild revenue rose 95.3% to $115.6 million, and paying members reached 2.94 million. The company added roughly 335,000 net members while, citing Antenna, the broader U.S. SVOD industry lost 1.7 million subscribers. Annualized recurring revenue rose to about $484 million from $466 million. Average revenue per member recovered modestly to $13.73 after a promotion-depressed Q2.
The weaker signals are harder to ignore:
- Net additions fell from about 390,000 in Q2.
- Year-over-year member growth decelerated to 86% from 99%.
- Guild selling and marketing expense rose to 55.2% of Guild revenue from 52.8% last quarter. That is still a big improvement from 75% a year ago, but the sequential trend reversed.
- Management acknowledged that acquisition slowed in late September and into October on back-to-school seasonality.
Management's tone shifted toward describing an inflection point, and the catalyst list is genuine:
- Drummer Boy opened top-three with $9.3 million domestically.
- Theatrical campaigns now sell Guild memberships alongside tickets, co-funding marketing.
- An in-house AI ad platform is enabling title-specific targeting.
- The streaming library surpassed 1,500 releases, beating the 2026 goal.
- Four holiday releases fall in the seasonally strongest quarter.
- Spanish-language, UK and Canada tests lay groundwork for international expansion.
The guidance tells a more cautious story. Management only reiterated its full-year adjusted EBITDA loss of less than $25 million. With nine-month losses at $10.9 million, that leaves room for a Q4 loss of up to roughly $14 million, as seasonally higher ad rates pressure marketing efficiency. Bears have legitimate ammunition in that gap.
The balance sheet improved but remains thin:
- Notes payable fell to $75.5 million from $97.2 million at year-end.
- Cash slipped to $45.6 million from $48.0 million in Q2.
- Stockholders' equity is only about $10 million.
- Acquisitions of Tuttle Twins and The Wingfeather Saga added 9.4 million shares, and weighted shares rose to roughly 189 million from 157 million a year ago. That dilution helps explain why per-share progress lags the revenue story.
Investors had already turned cautious. Earnings Whispers sentiment moved from slightly positive (0.05) to modestly negative (-0.14), a meaningful though not dramatic deterioration. Shares at $3.74 are down 8.8% from the $4.10 opening after the August report, despite a quarter in which revenue doubled. The stock sits just 2.3% above its 200-day moving average of $3.66, and the AVWAP trend reading remains negative. The market has not been rewarding the growth with much conviction.
The bottom line is that Angel delivered a standout top line, sharply better margins and continued positive cash flow, keeping its growth story credible. The beat leaned heavily on a box-office hit, however, while Guild growth decelerated, acquisition efficiency slipped sequentially, and management declined to raise guidance despite room to do so. Q4 will test whether the holiday slate and new theatrical-to-Guild marketing can reaccelerate member additions before seasonal costs pressure results.
Read our earnings preview for Angel Studios, Inc.: https://www.earningswhispers.com/article/ANGX/22720
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-10 | |
| Nov-03 | |
| Oct-29 | |
| Oct-22 | |
| Oct-14 | |
| Sep-15 | |
| Sep-03 | |
| Aug-12 | |
| Aug-04 | |
| Jul-14 | |
| Jul-02 | |
| Jun-23 | |
| Jun-11 | |
| May-11 |
