BrightView Must Prove Its Land Maintenance Recovery Can Finally Reach The Bottom Line
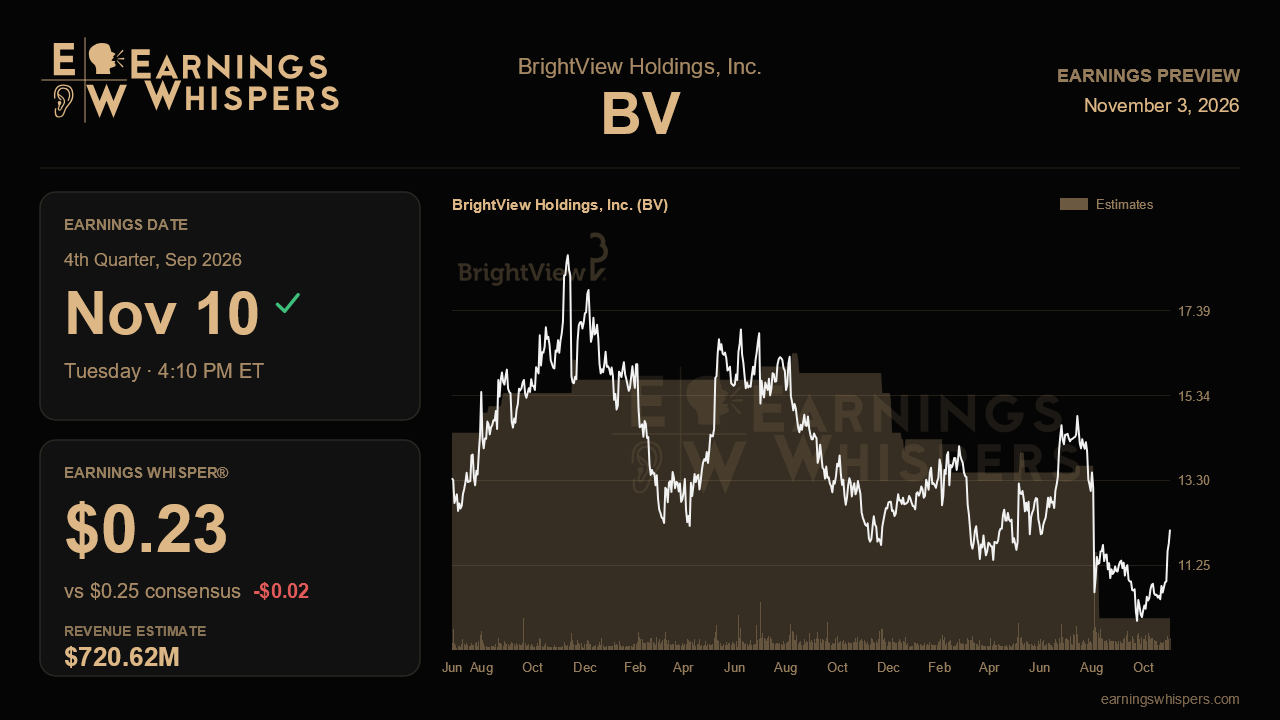
BrightView heads into its fiscal fourth-quarter report with a split personality. The landscaping company's growth engine is clearly turning over, with the land maintenance contract book expanding for five straight quarters and customer retention climbing to roughly 84.6%. Yet last quarter's profit picture was muddied by a $16 million self-insurance charge and stubborn fuel costs, which forced management to trim its EBITDA outlook and cut its free cash flow target from $100 million to $115 million down to $70 million to $80 million. The September quarter is the first real chance to show that those hits were detours rather than a new road.
The Street expects earnings of $0.25 per share on revenue of about $720.6 million, roughly 2.5% above the $702.8 million posted a year ago. That is modest growth, and the EPS target is barely above last year's $0.24, so the bar is not demanding on paper. The Earnings Whisper sits a touch lower at $0.23, a small gap but one suggesting some participants expect fuel and lingering cost pressure to shave a few cents. Management recently narrowed full-year revenue guidance to $2.75 billion to $2.78 billion, and the $2.77 billion consensus sits in the upper half of that range. In other words, analysts are leaning on BrightView to finish the year on solid footing, not merely to scrape into its band.
The most important number may be land maintenance growth. Management's fourth-quarter outlook implies land revenue rising 3% to 6%, a step up from the 2.3% gain in the third quarter. Hitting the middle or upper part of that range would validate the argument that a larger salesforce, now about 200 net sellers above its end-of-2024 level, is translating into sustained contract wins after new sales jumped about 20% year to date. Landing near 3% or below would raise questions, especially because ancillary work has lagged the contract book and snow revenue was already guided lower. Watch, too, whether the contract book holds near its recent 4% growth rate, since that is the leading indicator for fiscal 2027.
Profitability is where the narrative is most vulnerable. Excluding the insurance charge and fuel, third-quarter margins would have been 16.2%, with land flow-through running near 25%, comfortably above the company's 20% to 22% target. A clean fourth quarter should show margins recovering toward that underlying level. Fuel remains a live headwind, roughly a dollar per gallon higher than a year ago, so evidence that hedging, routing technology and fleet upgrades are offsetting more than the roughly 30% they covered last quarter would be encouraging. Any further reserve adjustments on older insurance claims would undercut management's claim that the charge was a one-off, even with more than 85% of 2023-and-prior claims closed. Investors should also look for early signs that renewal repricing in southern markets is capturing higher costs.
The market has given BrightView the benefit of the doubt. Shares are up about 10% since the last report while the S&P 500 fell roughly 3%, a sharp outperformance that suggests investors bought the non-routine explanation. Sentiment is mildly bullish and essentially unchanged from last quarter. At $12.11, the stock is pressing against its post-earnings high of $12.29 and sitting just under its 200-day moving average of $12.31, so a convincing report could push it through both levels. Still, it trades well below the $15 peak from the prior quarter, a reminder of how much confidence was lost.
Ultimately, this report comes down to whether BrightView can deliver accelerating land growth alongside cleaner margins and cash generation. Revenue momentum alone is no longer enough; management needs to show the turnaround produces earnings and free cash flow that hold up without asterisks.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-28 | |
| Oct-01 | |
| Sep-10 | |
| Aug-10 | |
| Aug-04 | |
| Jul-16 | |
| Jun-18 | |
| Jun-11 | |
| May-05 | |
| May-05 | |
| Apr-30 | |
| Apr-15 | |
| Mar-25 | |
| Mar-12 |
