BrightView Misses As Development Slumps, Overshadowing Accelerating Land Maintenance And A Lower FY27 Bar
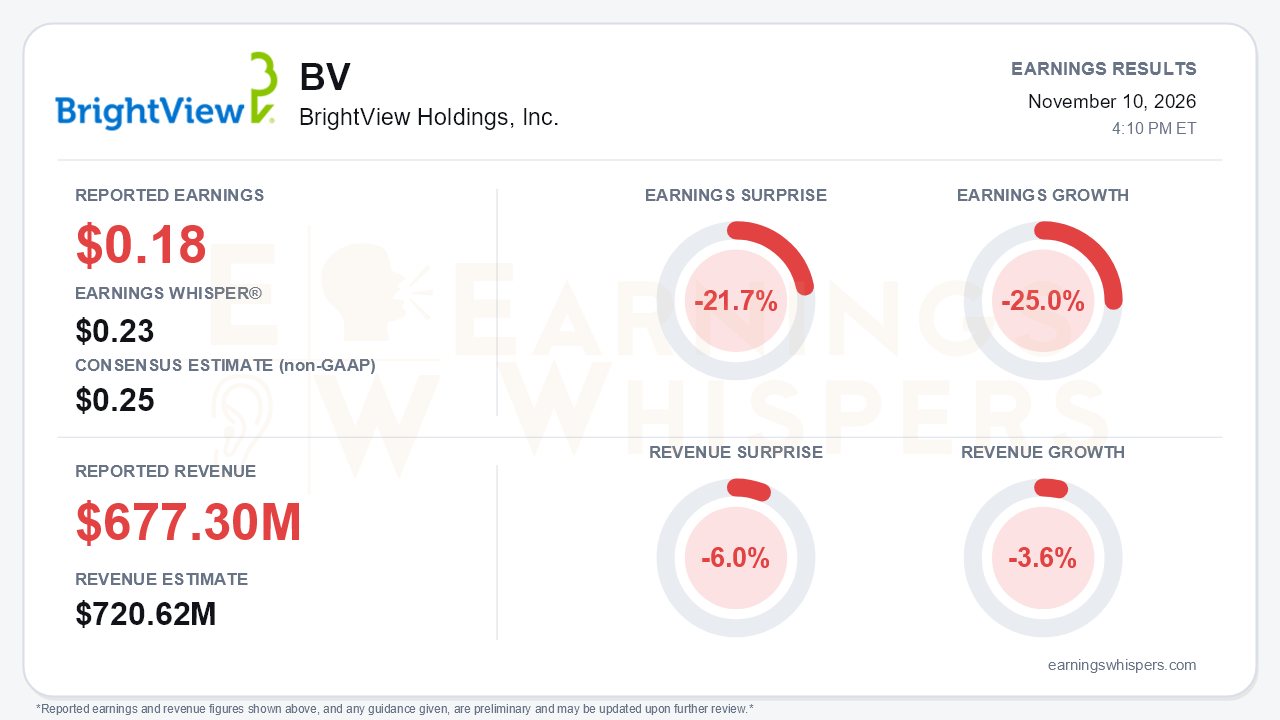
BrightView Holdings (NYSE: BV) closed fiscal 2026 with a clear miss. Adjusted earnings of $0.18 per share fell 21.7% short of the $0.25 consensus and also trailed the $0.23 Earnings Whisper number. Revenue of $677.3 million came in 6.0% below the $720.62 million estimate. On Earnings Whispers' normalized basis, earnings fell 25.0% year over year; the company's own adjusted EPS comparison against $0.27 shows a steeper decline. Revenue fell 3.6%, a deceleration from 1.5% growth for the full year. The central tension is plain. The recurring Land Maintenance business is genuinely improving, but the Development segment collapsed. Guidance for fiscal 2027 now sits well below the trajectory management sketched just one quarter ago.
The quality of the quarter deserves scrutiny below the adjusted line. GAAP net income fell to $8.3 million from $27.7 million. After $9.0 million in preferred dividends, common shareholders absorbed a $0.01 per-share loss. Adjusted EBITDA dropped 11.6% to $100.3 million, and margin contracted 130 basis points to 14.8%. Nearly all of the damage came from Development:
- Segment revenue fell 17.8%.
- Segment EBITDA fell 34.4%.
- Segment margin compressed to 14.5% from 18.2% as labor and material costs absorbed a larger share of a shrinking revenue base.
On the Q3 call, management had set a low end of -3% for Development in the fourth quarter, so this was not a rounding error. Full-year adjusted EBITDA of $328.9 million missed both the original $363–377 million guide and the roughly $340–345 million implied after the Q3 revision.
The call preserved a credible growth story in the core. Land Maintenance has now accelerated through the year:
- roughly -2% in Q1;
- about 2% normalized in Q2;
- 2.3% in Q3;
- 3.3% in Q4.
Management guided fiscal 2027 land growth to 3–4%, above the 2–3% framework used throughout fiscal 2026. The leading indicators support that guide. Net new sales were positive for a sixth straight quarter, and October produced a record $11.6 million, about 1% contract book growth in a single month. Frontline turnover improved roughly 600 basis points, and land flow-through is running above 25%, versus the 20–22% previously targeted. Retention, however, was essentially flat at about 84.5%. Management's tone also shifted from Q2's 'inflection' enthusiasm to a more defensive posture focused on transparency around Development.
The outlook is where bears have legitimate ammunition. Fiscal 2027 revenue guidance of $2.535–2.720 billion is below fiscal 2026 at the midpoint. Snow is expected to normalize to $210–230 million from $293 million. Development is guided between down 20% and flat, and management said the first quarter shows no improvement yet. Q3 had pointed to Development growth into 2027.
Adjusted EBITDA guidance of $335–355 million implies about 110 basis points of margin expansion, but roughly half of that comes from lapping a $16 million self-insurance charge. The range also falls well short of the 'above $365–370 million normalized' bar implied last quarter. Other headwinds include:
- a $4–6 million fuel drag in the first half with no surcharges on existing contracts;
- the need to push 3–4% renewal pricing, about half of which may be given back in scope;
- political uncertainty around data-center work, which together with residential makes up about 15% of the backlog.
On the positive side, Development backlog of roughly $800 million and more than $500 million in pending bids offer some visibility.
The balance sheet has also moved the wrong way. Fiscal 2026 adjusted free cash flow was an outflow of $2.2 million, and cash dwindled to $3.6 million. Net financial debt rose to $1.01 billion, or 3.1x adjusted EBITDA, from 2.3x. Even so, the company repurchased 4.1 million shares, spending $56.9 million, while drawing a net $99.8 million on its receivables facility. The fiscal 2027 free cash flow guide of $110–130 million is the key offset. With the fleet refresh about 85% complete, lower capex should drive deleveraging if management delivers.
Investor sentiment improved modestly into the report, rising to 0.27 from 0.19. That level is mildly positive rather than enthusiastic, and it now meets a miss and a softer outlook. Shares at $11.43 were up 3.9% from the open after the August report but remained 6.8% below the 200-day moving average of $12.27. The market had been treating BV cautiously rather than pricing in a recovery. Positive AVWAP and neutral price-trend readings suggest recent holders were not under heavy pressure entering the print.
The bottom line is that BrightView's recurring land engine is doing what the turnaround thesis requires: accelerating growth, record sales, better flow-through and lower turnover. Those gains, however, are being swamped by a Development downturn, snow normalization and rising leverage. Fiscal 2027 guidance resets expectations below last quarter's framing. Investors now need execution on land growth, a free cash flow rebound and stabilization in Development before the improving core can carry the stock.
Read our earnings preview for BrightView Holdings, Inc.: https://www.earningswhispers.com/article/BV/22728
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 9 hours | |
| 13 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-28 | |
| Oct-01 | |
| Sep-10 | |
| Aug-10 | |
| Aug-04 | |
| Jul-16 | |
| Jun-18 | |
| Jun-11 | |
| May-05 |
