Black Rock Coffee Bar Must Prove July's Traffic Rebound Was Real After A 43% Rally
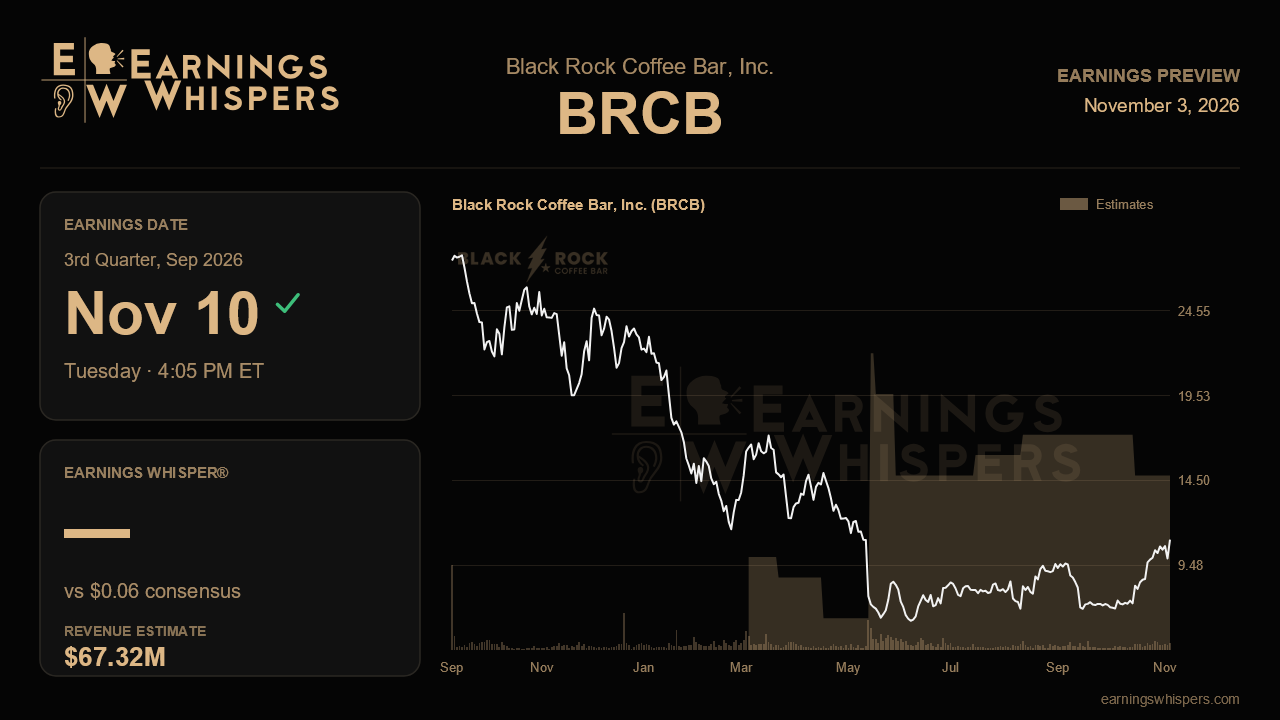
Last quarter, Black Rock Coffee Bar asked investors to look past a soft traffic number. Same-store transactions fell 2% as the chain lapped a loyalty program free-drink and expiration benefit, and management took the unusual step of disclosing that July transactions had already turned positive, up 1.7%. Investors believed it. The stock has climbed nearly 43% since that report while the S&P 500 slipped about 3%. The third-quarter release is where that interim data point either becomes a trend or turns into an awkward footnote.
The Street is looking for earnings of $0.06 a share, matching the second quarter and a sharp swing from a $0.05 loss a year ago. Revenue is projected at $67.3 million, up roughly 31% from $51.5 million and a solid step up from the prior quarter's $63.0 million. Those growth figures are strong, but much of the revenue gain comes from new units rather than existing stores, so the composition of that growth matters as much as the total. One notable detail: management has held full-year revenue guidance at $255 million to $257 million since late last year, while the consensus sits around $253.6 million, below the bottom of that range. In other words, analysts are still treating the company's sales outlook with some caution, which leaves room for upside if the third quarter keeps the company on track for its own numbers.
The more meaningful guidance move came on development and profitability. Black Rock lifted its 2026 new-store target to at least 38 from 36 and nudged adjusted EBITDA guidance up to $34 million to $35 million, its first raise since going public. Store-level margin hit a record 30.2%, helped by beverage, food and packaging costs falling 220 basis points as a share of sales. The key question is whether that margin holds as menu additions like the now-permanent grilled cheese push food to a larger slice of the mix and as a one-hour extended operating test adds labor. Margin stability near 30% would validate the idea that new products are adding traffic without diluting economics.
This quarter is also a tough comparison by design. Management flagged that the third quarter laps the hardest three-year same-store sales stack, roughly 10.8% to 10.9%. Positive transactions against that backdrop would be a powerful confirmation that the loyalty lap was the whole story. Helping the case, the sales transfer from opening stores close to existing ones, which cost 160 basis points in the first quarter, should be mostly lapped. On the cost side, the second quarter saw EBITDA grow just 17% against 25% revenue growth because of public-company expenses. Management's full-year outlook implies second-half EBITDA growth of 28% to 35%, so investors should look for EBITDA growth to outpace revenue for the first time in a while. If it does not, the raised EBITDA guide starts to look stretched.
Development is the longer-term thread. The company pulled forward its California pipeline, with about seven more openings expected this year and 12 to 15 in 2027, and said early California stores were trending toward $1.6 million in first-year volumes. Capital spending was raised to $42 million to $43 million, with roughly 30% aimed at 2027 openings. Updates on opening pace and California productivity will show whether that heavier spending is buying durable returns. Competitive conversions in Phoenix, a core market, are worth a mention as well.
Sentiment has flipped from distinctly bearish before the last report to modestly bullish now, and the stock sits just above its 200-day moving average at $10.62, a few percent shy of its post-earnings high of $11.13. That is a more demanding setup than three months ago. The report ultimately hinges on traffic: if transactions stay positive against the toughest comparison of the year while margins hold, the narrative of a durable growth story stays intact; if July proves to be a one-month blip, the rally leaves little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-29 | |
| Oct-23 | |
| Oct-20 | |
| Oct-09 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-21 | |
| Sep-11 | |
| Sep-11 | |
| Sep-01 | |
| Aug-28 |
