Black Rock Coffee Bar Misses EPS Estimates As Traffic Turns Positive, While Store Margins And Build Costs Move The Wrong Way
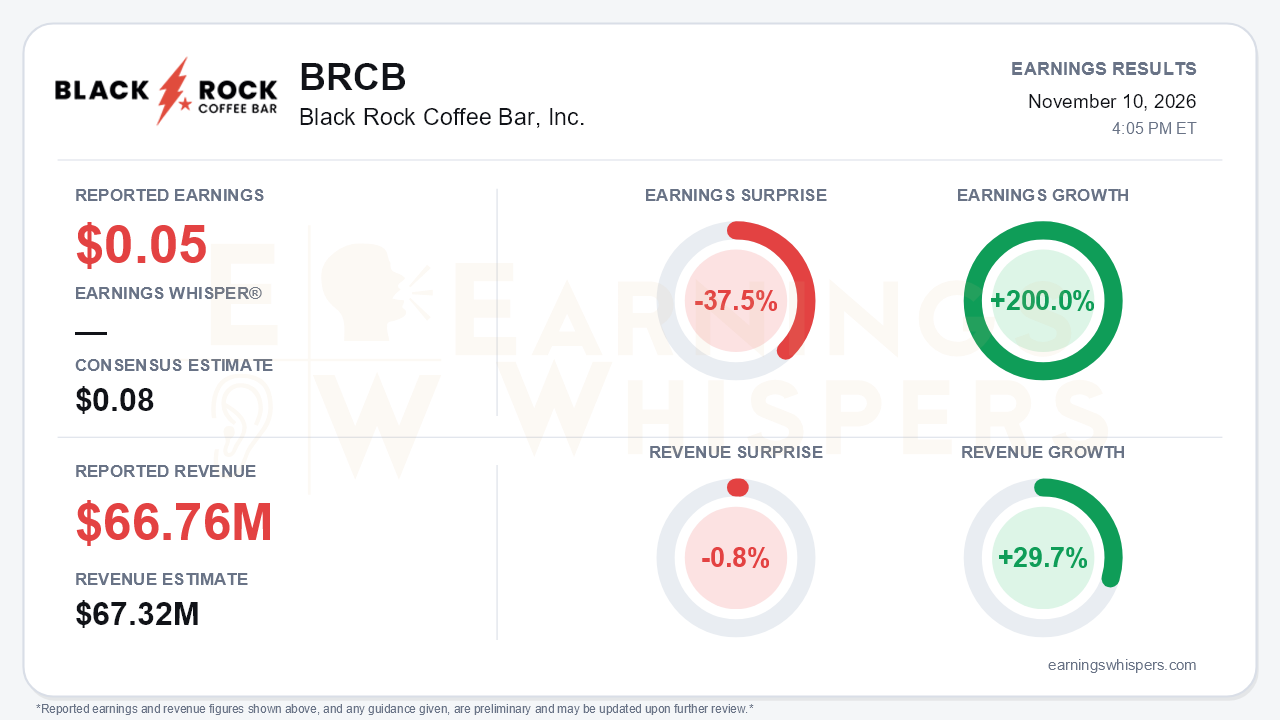
Black Rock Coffee Bar delivered a third quarter that pulled in two directions. The company earned $0.05 per diluted share on revenue of $66.76 million. Earnings missed the $0.08 consensus by 37.5%, and revenue came in 0.8% below the $67.32 million estimate. Underneath those misses, demand improved. Revenue grew 29.7% year over year, faster than 25% in the second quarter and 23.7% in the first. Earnings grew 200.0% from a loss of $0.05 per share a year ago. The central tension is that the top line and traffic strengthened just as store-level profitability and capital intensity deteriorated. Management reaffirmed, rather than raised, its full-year revenue and EBITDA targets.
The quality of the earnings line needs context. The swing to GAAP profitability is real: operating income was $2.8 million versus a $6.4 million operating loss a year ago. Most of that improvement reflects the absence of roughly $9.1 million in IPO transaction costs and $6.9 million in capital restructuring charges from the prior-year quarter, not a step change in operations. A $0.7 million tax benefit also helped. The dilution mechanics of the Up-C structure matter as well. Basic EPS was $0.07, but diluted EPS fell to $0.05 on 50.1 million diluted shares versus 22.5 million basic. Adjusted EBITDA rose 22.1% to $8.5 million, an improvement from 17% growth in the second quarter. However, adjusted EBITDA margin slipped to 12.7% from 13.4%, and EBITDA fell sequentially from $9.4 million.
The call made a credible case that demand is improving. Same-store sales accelerated to 5.8% from 4.2% in the second quarter. The two-year stack rose for a third straight quarter to 16.6%. More importantly, transactions turned positive at +2.4% after declines of 2.0% in the second quarter and 0.6% in the first. Management now expects positive traffic for the full year and called the fourth quarter its strongest for both comps and transactions. Several initiatives appear to be driving the change. Extended hours are now permanent at about 70% of stores and are described as profitable. Food mix rose to 14.2% from about 13%, and loyalty penetration reached roughly 69%. Management was also candid that the consumer is more challenging than a year ago. That candor makes the traffic inflection more notable, but it also tempers how far investors should extrapolate it.
The cost side is where bears have legitimate ammunition. Store-level margin fell to 28.9% from 30.2% in the second quarter and 29.6% a year earlier. Management attributed the decline to about 110 basis points of labor deleverage from extended hours and grand-opening teams, plus roughly 50 basis points from occupancy, and expects similar margins in the fourth quarter. Pre-opening costs climbed to 2.9% of revenue. Build costs are running near $800,000 per store, compared with a $700,000 to $750,000 plan and about $650,000 in 2025. Capex guidance rose for a second time, to $47 million to $48 million net, up from an initial $40 million to $41 million. Unit guidance also increased again, to 40 openings from 38, and the California pipeline for 2027 expanded to 15 to 20 stores. Together, these changes mean growth is costing more to buy. Liquidity has tightened as a result. Cash fell to $13.6 million from $28.4 million at year-end, and the company drew $4 million on its revolver. Nine-month operating cash flow of $29.1 million has not covered $53 million in investing outflows.
Guidance carries the forward narrative. The reaffirmed $255 million to $257 million revenue range, despite more units, implies a fourth-quarter acceleration to roughly $70 million to $72 million. Management guided fourth-quarter adjusted EBITDA growth above 30% as public-company costs are lapped. Execution on that implied ramp is now the key test.
The market setup is more complicated than the miss implies. Investor sentiment swung from clearly negative at -0.276 after the prior report to slightly positive at 0.032. That is a meaningful repair in expectations, though not exuberance. The stock entered the report at $11.10, up 49.4% from the $7.43 open after the August release. It had also rallied about 65% off its October 5 low of $6.71 to sit just 5.7% below its November 6 inter-earnings high. Shares were trading 7% above their 200-day moving average, and the Earnings Whispers momentum and AVWAP readings are positive. A rally of that size into the print leaves less room for a quarter that missed on both lines and only held guidance.
The bottom line is that Black Rock's demand story genuinely improved this quarter, with positive traffic, accelerating comps and a third unit-guidance raise. The earnings miss, compressed store margins, rising build costs and thinning cash balance show that this growth is getting more expensive. With the stock having already rebuilt much of its sentiment and price, the fourth-quarter EBITDA acceleration management promised now has to show up.
Read our earnings preview for Black Rock Coffee Bar, Inc.: https://www.earningswhispers.com/article/BRCB/22727
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-29 | |
| Oct-23 | |
| Oct-20 | |
| Oct-09 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-21 | |
| Sep-11 | |
| Sep-11 | |
| Sep-01 | |
| Aug-28 |
