Evolv's Raised Outlook Meets A Skeptical Street As Margins And ARR Face Third-Quarter Test
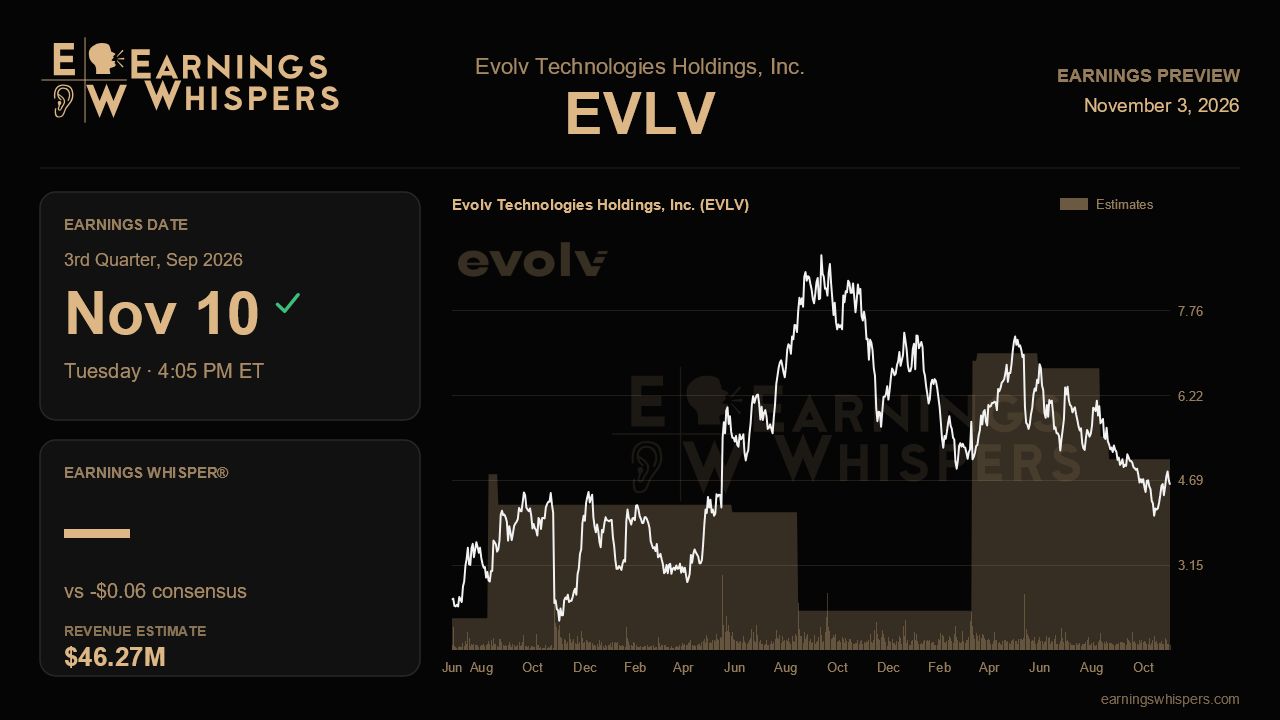
Evolv Technologies heads into its third-quarter report with an unusual disconnect. Management has raised its full-year revenue outlook three times, most recently to $180 million to $185 million, and for the first time put a hard number on adjusted EBITDA at $15 million to $16 million. Yet the stock has fallen almost 24% since the last report, and analysts' full-year revenue estimate of about $177.8 million sits below the bottom of the company's own range. Either the Street knows something about the back half that management does not, or the bar for Evolv to clear is lower than its guidance suggests.
For the quarter ending in September, consensus calls for a loss of $0.06 per share on revenue of roughly $46.3 million. That top-line figure would be up about 8% from the $42.9 million reported a year earlier, a striking slowdown from the 34% growth Evolv posted in the second quarter, when revenue reached $43.8 million. The expected loss is also wider than both the $0.05 loss last quarter and the $0.01 loss a year ago. A revenue print modestly above consensus would do little to close the gap with guidance, so the more meaningful test is whether Evolv delivers results that make the $180 million floor look comfortably achievable and prompts analysts to move their models up toward management's range.
Gross margin is the most likely friction point. Margins slipped to about 51% last quarter, short of the mid-50s level the company had earlier targeted, and management attributed the shortfall to three factors: a heavier mix of purchase subscriptions, now assumed at 60% of annual units; refurbishment, freight and depreciation costs from customers upgrading Gen1 units to Gen2 faster than expected; and component cost pressure tied to semiconductor supply. Management framed these as structural or timing issues rather than signs of softer demand. A stable or improving margin would support that view. Another step down, particularly if supply costs worsen, would suggest the headwinds are more persistent and would put pressure on the newly quantified EBITDA target, after adjusted EBITDA margin climbed to 10.1% in the second quarter.
Recurring revenue quality is the second issue. Annual recurring revenue grew about 20% last quarter while unit growth ran near 30%, a gap explained by lower-priced redeployed Gen1 units and introductory pricing on Expedite, the bag-screening product that has passed 100 customers. Management is implementing an Expedite price increase to narrow that spread, and early evidence that ARR growth is catching up to unit growth would strengthen confidence in the year-end ARR target of $148 million to $150 million. Remaining performance obligations of $312.6 million, up from $299 million the prior quarter, also give a useful read on future revenue, and continued sequential growth would suggest bookings momentum held after a strong quarter of 70 new customers.
The quarter also included part of the short-term FIFA World Cup deployment and Plexus taking over most manufacturing, both of which could affect revenue timing and unit costs. Cash, which turned positive a quarter early to $63 million, could be affected by a possible $2 million to $4 million inventory safety-stock build, and investors should look for an explanation of any decline rather than read it as a reversal.
Sentiment has cooled, with bullish readings slipping to 15.2% from 20.1% before the last report. The stock trades at $4.61, well below its 200-day moving average of $5.64 and closer to its post-earnings low of $4.02 than its $6.10 high, a range set entirely below the prior quarter's trading band. That pessimism leaves room for a positive reaction if Evolv delivers. The central question is whether gross margin and ARR can stabilize enough to show that the growth story management laid out, including its long-term goal of more than $500 million in revenue by 2031, rests on profitable, durable revenue rather than lower-margin unit growth.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-23 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Sep-28 | |
| Sep-23 | |
| Sep-09 | |
| Aug-18 | |
| Aug-14 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 |
