Evolv Misses On GAAP EPS As Growth Slows To 10%, But Cash Flow, RPO And A 20%+ 2027 Outlook Support The Recurring Story
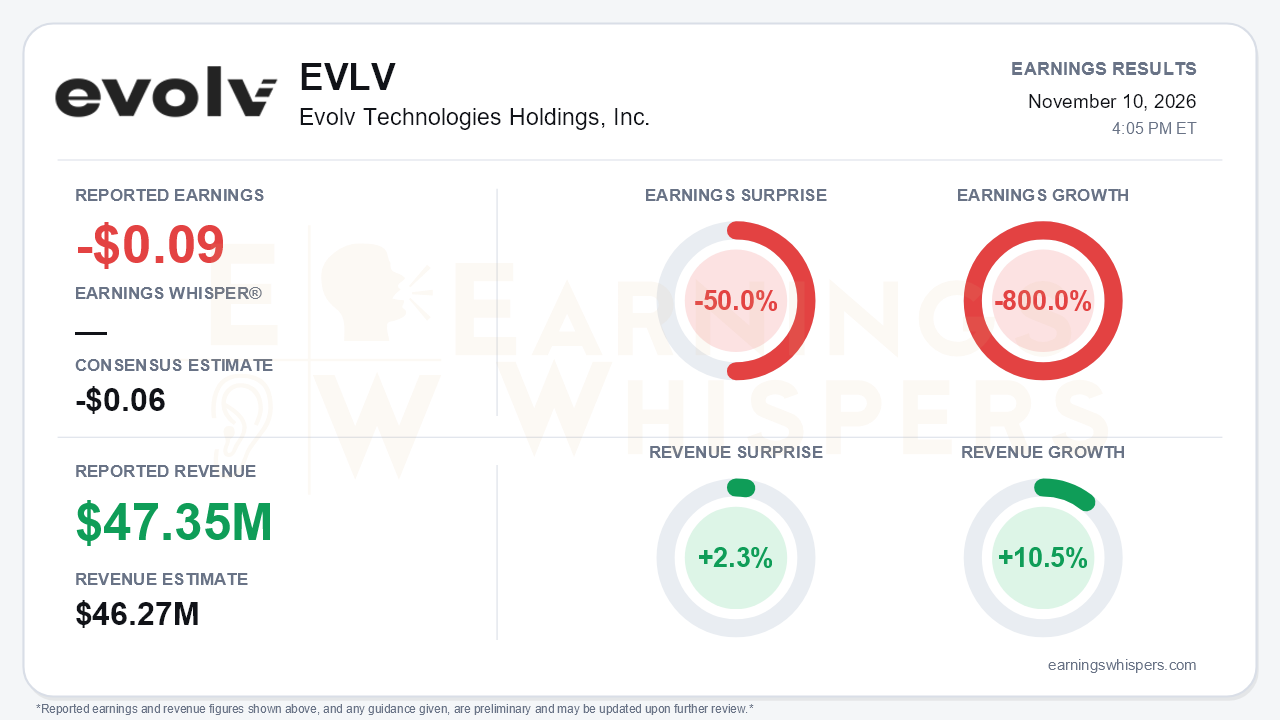
Evolv Technologies (NASDAQ: EVLV) delivered a quarter where the headline result and the underlying business point in different directions. The security-screening company reported a GAAP loss of $0.09 per share for the September quarter. That was well below the consensus estimate of a $0.06 loss, a 50.0% miss, and compares with a $0.01 loss a year ago, an 800.0% decline in earnings. Revenue of $47.35 million beat the $46.27 million consensus by 2.3% and set a quarterly record, but year-over-year growth slowed to 10.5%. That compares with 34% growth in the second quarter and 45% in the first. Revenue growth is decelerating sharply while the recurring base keeps compounding, and that is the central tension.
The quality of the miss deserves scrutiny, because most of it sits below the operating line. The net loss widened to $15.6 million from $1.8 million, but two items drive much of that gap. Last year's quarter benefited from a $7.5 million gain on the contingent earn-out liability, which did not recur. This year's quarter absorbed $4.8 million of non-recurring legal and regulatory costs, which pushed G&A to $18.7 million from $12.6 million. On an adjusted basis, the loss was $0.02 per share, unchanged from a year ago. The cash picture was clearly stronger. Operating cash flow jumped to $18.0 million from $3.5 million, and free cash flow swung to a positive $3.2 million from negative $11.5 million. Cash rose sequentially to $66.9 million, and remaining performance obligations climbed to $325.8 million.
The operating trends were more mixed than either the GAAP loss or the cash flow suggests. Management attributes the revenue slowdown to three factors: lapping direct fulfillment, a pricing-model shift, and the largest contract in company history in the prior-year period. It puts normalized growth at roughly 18% to 19%. ARR growth fits that framing at 20%, reaching $140.5 million. Net revenue retention, disclosed for the first time, was 108%. Margins moved in opposite directions by line. Subscription gross margin rose to 59.8% from 51.8%, but product gross margin compressed to 8.7% from 13.9% under the new pricing structure. Adjusted EBITDA slipped to $4.7 million, or a 10% margin, from $5.1 million and 12%, as R&D, sales and newly cited SOX remediation spending rose. Adjusted gross margin of about 50.8% also remains below the mid-50s level management suggested earlier in the year. New customer additions fell to 51 from 70 in the second quarter, a detail worth watching even as management described demand as broadening.
The forward-looking evidence is what kept the growth story credible. Full-year revenue guidance was narrowed to $182 million to $185 million, the fourth straight increase at the low end. Adjusted EBITDA guidance edged up to $15.5 million to $16.5 million. Management also offered an initial 2027 view of 20%+ revenue growth, despite a 3 to 4 point pricing headwind, with ARR growth expected to outpace revenue and modest EBITDA margin expansion. Demand indicators widened across several fronts:
- Healthcare reached 23% of units booked, ahead of California hospital screening standards due by March 2027.
- Fortune 500 customers now exceed 40.
- Expedite customers grew to 115, with an 88% Express attach rate.
Bears still have legitimate ammunition. ARR growth has held near 20% for three quarters, so the reaffirmed $148 million to $150 million year-end target requires a fourth-quarter step-up. First-half 2027 comparisons are tough, and the return on new sellers skews to late 2027 and 2028.
The market had already priced in considerable doubt before the report. Shares closed at $4.76 the day before the release, down 21.3% from the $6.05 open after the August report. They sat 15.0% below the 200-day moving average and 22.0% beneath the inter-earnings high. The stock set a 52-week low of $4.02 in mid-October before recovering about 18%. Investor sentiment remained positive but weakened modestly, slipping to 0.15 from 0.20. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Evolv's GAAP miss and slowing headline growth are real, but they overstate the deterioration in the core model. Recurring revenue, subscription margins, RPO and cash generation all improved, and guidance moved higher again. The setup now depends on whether ARR accelerates in the fourth quarter and whether investment spending converts into the 20%+ growth management outlined for 2027. Until that happens, the stock's depressed technical position reflects a market that wants proof rather than projections.
Read our earnings preview for Evolv Technologies Holdings, Inc.: https://www.earningswhispers.com/article/EVLV/22735
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-23 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Sep-28 | |
| Sep-23 | |
| Sep-09 | |
| Aug-18 | |
| Aug-14 |
