Evolution Petroleum's First Permian Minerals Quarter Tests Whether Its Recovery Can Outrun Weak Gas
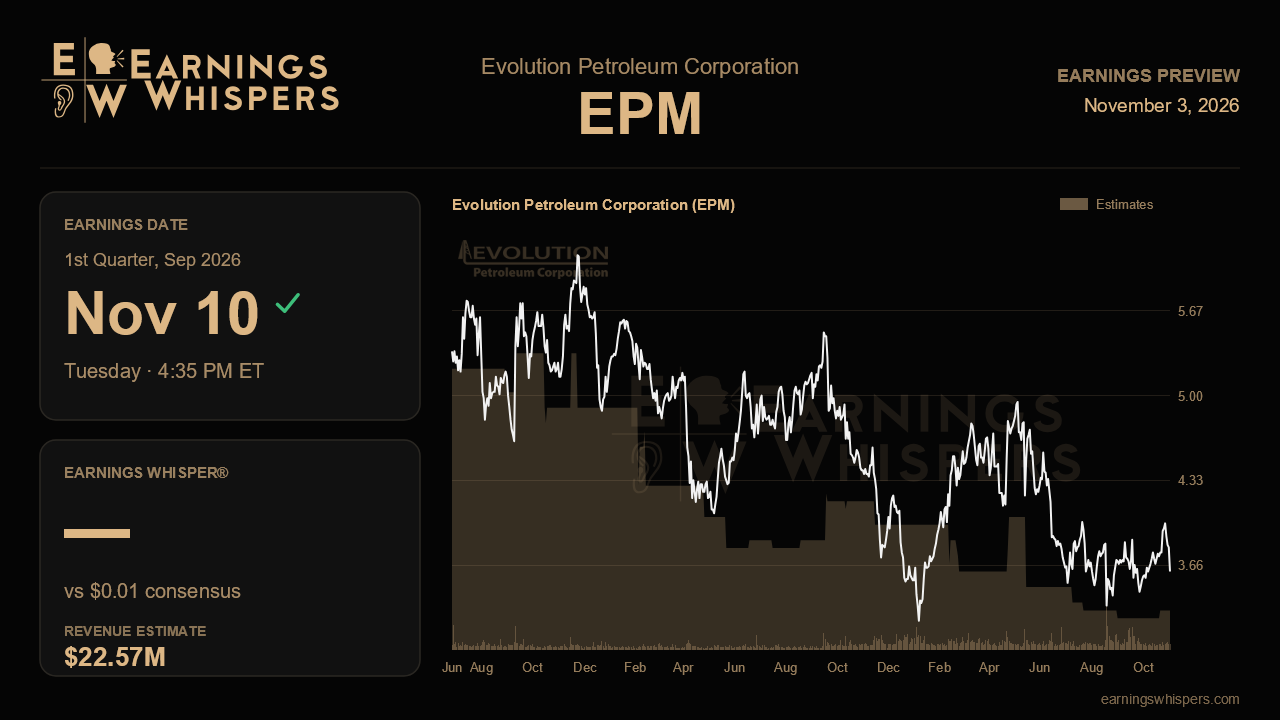
Evolution Petroleum heads into its fiscal first-quarter report with a story that improved on paper last quarter but has not convinced the market. The September call showed the rebound management had promised: revenue jumped 20% sequentially, adjusted EBITDA more than doubled, and the company added a roughly $16 million Permian minerals package. Since then the shares have fallen about 6%, trailing the S&P 500 by more than five points. The November 10 release, due after the close, is the first chance to show the turnaround is a trend rather than a one-quarter bounce.
The bar is low but not trivial. Analysts expect earnings of about a penny a share on revenue of $22.6 million. That would be roughly 6% growth over the year-ago $21.3 million, a modest gain, but it also implies a step down from the $24.2 million reported last quarter. Management again declined to give fiscal 2027 production or operating cost guidance, saying it has limited visibility into non-operated assets, so there is no company range to measure the Street against. Consensus appears to assume some sequential giveback, and how large that turns out to be will shape the reaction more than the penny of EPS. The headline number may also be noisy. Last quarter's $5.8 million unrealized hedge gain reversed a $7.6 million loss the quarter before, so GAAP results can swing on commodity marks as much as on operations.
The most important operating question is whether the Permian deal starts to appear in the numbers. The acreage came with more than 200 barrels of oil equivalent per day of production and no capital spending requirement, and rig activity on it rose from seven to eight. Mineral revenue data can lag by up to 180 days, however, so this quarter may show only part of the contribution. Any update on what has actually been received would help. Production is the related test. Fourth-quarter output of 6,901 BOE per day was down 4% from a year earlier, and the ScoopStack position, up 14% to 1,275 BOE per day, needs to keep growing to offset declines elsewhere.
Pricing works in both directions. Management described a much better liquids picture, with Delhi crude selling at a premium to WTI as Louisiana differentials improved, and said Jonah gas differentials to the West Coast had narrowed meaningfully heading into the new fiscal year. Those improvements would support the recovery story. Natural gas remains the weak point, though. Henry Hub weakness has hurt realizations, and the futures strip was pricing in a warm winter. If gas realizations disappointed again, the sequential revenue decline built into estimates could prove too mild.
The balance sheet deserves more attention than usual. Pro forma liquidity was only about $19 million after the acquisition, and leverage was supported by a temporary borrowing base increase from $65 million to $73 million ahead of an early October redetermination. The result of that review, along with any timing update on the permitted six-well Chavaroo program with PEDEVCO at an estimated $3.6 million to $3.9 million per well, will show how much flexibility remains to fund development and keep paying the $0.12 quarterly dividend, which has now been paid 52 quarters in a row.
Sentiment has softened, moving from slightly bearish before the last report to more clearly bearish now, and the stock at $3.61 sits below its 200-day moving average of $4.05, in the lower half of its post-earnings range of $3.40 to $4.03. That skepticism lowers the hurdle. The key question is whether cash flow can hold near last quarter's improved level, helped by better liquids pricing and early Permian royalties, while gas stays weak. If it does, the improving narrative holds. If EBITDA slides back toward the levels of the spring quarter, investors will likely start questioning the dividend and the leverage again.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-29 | |
| Sep-22 | |
| Sep-21 | |
| Sep-21 | |
| Sep-17 | |
| Sep-15 | |
| Sep-15 | |
| Sep-10 | |
| Sep-08 | |
| Aug-28 | |
| Aug-20 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 |
