Hyliion's Stock Slump Puts Navy-Driven Revenue Ramp And Print-Speed Claims On Trial
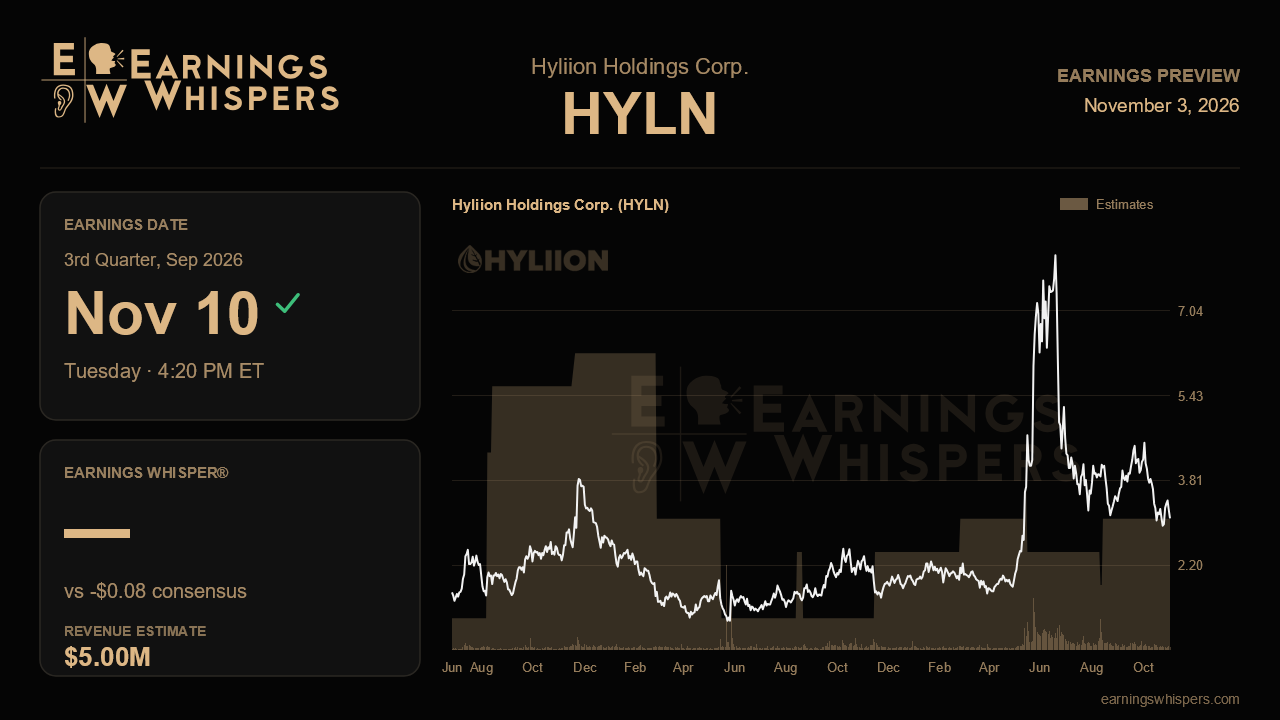
Hyliion arrives at its third-quarter report with an awkward contradiction. Last quarter management raised its full-year revenue outlook by half, booked its largest military contract ever and cut its expected cash burn, yet the stock has fallen about 39% since then while the S&P 500 slipped less than 3%. The results due after the close on November 10 need to show whether that improving story is still on track, or whether the market was right to focus on the delays and the new equity program.
Wall Street expects a loss of $0.08 a share, the same as both last quarter and the year-ago period, on revenue of roughly $5.0 million. That would be up about 559% from $0.8 million a year earlier, but essentially flat with the $4.9 million reported last quarter. The sequential comparison matters more. Management now guides to about $15 million for the full year, and with $7.8 million booked in the first half, the second half only needs about $7.2 million, or around $3.6 million a quarter. Consensus is therefore above the run rate the guidance implies. Analysts appear to be treating the $15 million target as conservative. If revenue comes in near $5 million, it would support the idea of another raise. If it falls back toward $3.5 million to $4 million, the company could still be on track for guidance and the quarter would still look like a stall.
The revenue engine is Navy research and development work, and the $41.7 million award to scale the Carno generator into modules above 2 and 3 megawatts is the backbone of the near-term story. Investors should look for evidence that billing against that contract is ramping as expected. They should also look for an update on the roughly $7 million award from a second service branch that management expected before year-end. That second award would bring military contracts close to $50 million and would show the company is not dependent on a single customer. Gross profit has been negligible, about $366,000 last quarter, so any sign that contract work can carry a real margin would be welcome.
The manufacturing claims are just as important. Management said it had found a way to raise print speed by up to three times. It sized its existing printers at up to 15 megawatts of annual capacity and said each $1.5 million of capital buys roughly a megawatt of capacity worth $2.5 million to $3 million in annual revenue. That claim was still being tested. Confirmation would back the plan to pull printer purchases forward from 2028 to 2027, and progress on the beta agreement with GE Aerospace's Calibrium unit would add credibility. Silence or hedging on the speed gains would weaken the argument that Hyliion can scale without heavy capital spending.
The weaker spots from last quarter remain swing factors. Commercialization of the 200kW module slipped from late 2026 into 2027, and data-center letters of intent stalled at about 750 cores after growing steadily for a year. New letters of intent, or concrete results from the planned deployments at AI test facilities, would help restore the commercial side of the story. Cash is the other test. Quarterly burn fell to $6.9 million from $13.1 million, and the year-end target of $115 million to $120 million depends on staying near that lower pace. Any use of the new at-the-market equity program will be read against the stock's current price.
Expectations have clearly cooled. Sentiment toward the stock has dropped to barely positive from solidly bullish a quarter ago. Shares at $3.09 sit below the 200-day moving average of $3.44, near the bottom of their post-earnings range of $2.92 to $5.45. That lowers the bar for a positive reaction but does not remove it. The central question is whether Hyliion can show that Navy revenue is still ramping, the throughput breakthrough is real and the cash plan is holding. If it can, the selloff looks overdone. If any of those weaken, the market will likely keep pricing in the delays and dilution risk.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 | |
| Sep-16 | |
| Sep-08 | |
| Sep-08 | |
| Sep-03 |
