Hyliion Beats And Raises Again On Navy Work, But Hardware Slips And A Dropped Financing Keep The KARNO Story On A Short Leash
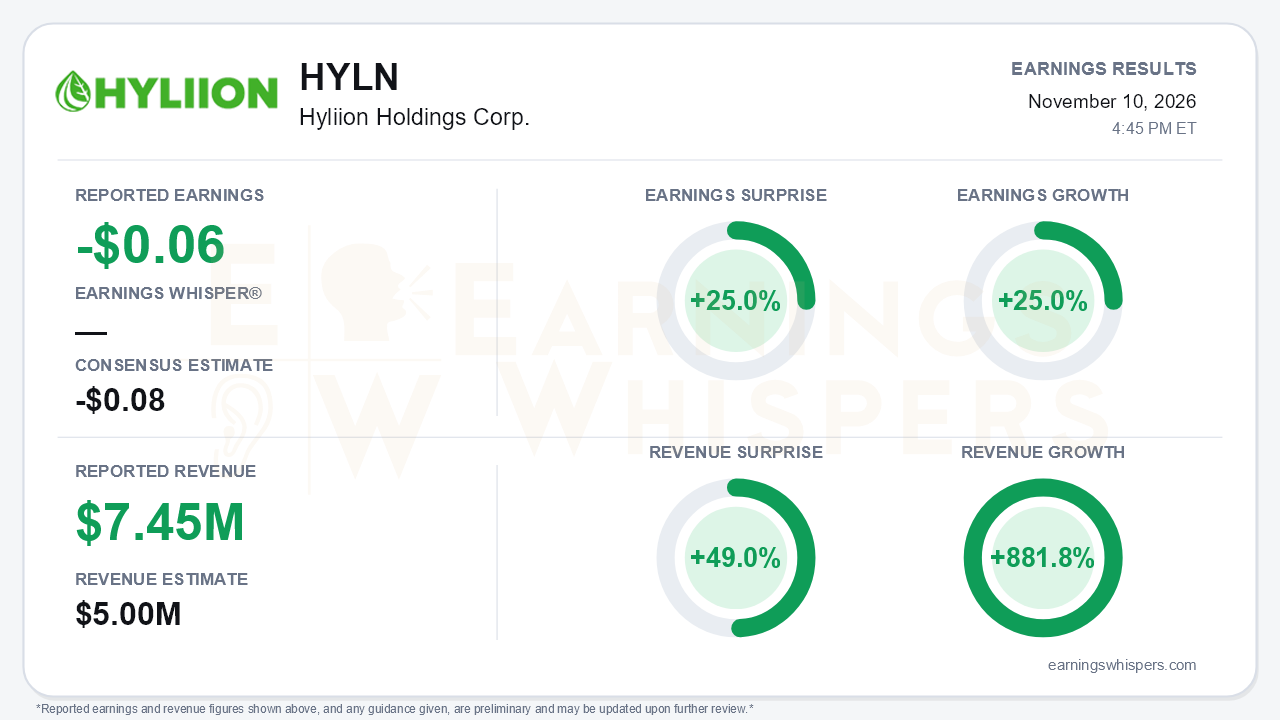
Hyliion delivered another clean beat on paper. The third-quarter loss was $0.06 per share, versus the $0.08 consensus, a 25.0% surprise and a 25.0% improvement from a year ago. Revenue of $7.45 million beat the $5.0 million consensus by 49.0% and rose 881.8% year over year. Management raised full-year 2026 revenue guidance for the second straight quarter, to about $18 million from $15 million. That outlook began the year at $10 million.
That is the central tension: the financial line is improving faster than the product line. Nearly all of the upside came from military research-and-development services rather than KARNO hardware sales. Meanwhile, the call disclosed a thermal-fatigue problem, schedule slips and a scrapped financing plan. Those are exactly the issues a pre-commercial power company cannot afford to accumulate.
The quality of the beat deserves scrutiny. Revenue has climbed steadily:
- $0.7 million in the fourth quarter of 2025
- $2.8 million in the first quarter
- $4.9 million in the second quarter
- $7.5 million in the third quarter
The third-quarter jump was driven largely by accelerated progress and about $3 million of extra Office of Naval Research funding on the 800-kW module for the USX-1 Defiant. That is contract R&D work, and it carries little margin. Gross profit was just $552,000, roughly a 7% gross margin.
The bigger gains came from cost discipline:
- Operating expenses fell 15% to $13.0 million.
- R&D declined 14% as engineers shifted onto billable military work.
- SG&A dropped about 17%.
- Quarterly cash burn fell to $11.0 million from $20.6 million, though mostly because capital spending collapsed.
The trajectory also breaks next quarter. Management guided fourth-quarter revenue to only about $3 million as the 800-kW work winds down. Most of the $41.7 million Navy contract won in July falls in 2027 and 2028, so the raised full-year number largely reflects work already booked.
On the operating side, the call preserved a credible demand story while weakening the execution narrative. Hyliion expects about $8 million of additional military awards before year-end, which would bring 2026 new awards to roughly $50 million, the high end of its original $40-50 million target. It also disclosed $45.5 million of remaining authorized funding under existing contracts. On the commercial side, management cited:
- interest from multiple hyperscalers;
- a three-day on-site evaluation by a large data center company;
- a second commercial unit headed to an AI test facility.
The 750-unit letter-of-intent base, however, has not grown since the first quarter.
The execution news was weaker. A printed reactor component developed micro-cracking from thermal fatigue, forcing a reversion to an earlier design. The 800-kW Navy system and the remaining early adopter deliveries slipped roughly six weeks into about February 2027. The first commercial deployment, which management on the second-quarter call expected to begin over the following quarter, is still described as "weeks" away. Commercialization of the 200-kW unit had already moved into 2027 on the prior call.
There are offsets worth noting:
- The company says it remains on track for 200 kW of output from the KARNO Core by year-end, aided by a denser regenerator mesh.
- An early print-speed proof point showed about a 2.5x improvement on the mixer component.
- Consolidating printers and core assembly into Texas, plus new leadership hires, should support 2027 volumes.
Bears have legitimate ammunition on the balance sheet. Hyliion dropped the $10-15 million equipment financing it had expected in 2026, citing unfavorable market terms. Year-end cash and investments of $115-120 million were reaffirmed, but management signaled the low end is likely. There is no 2027 capacity or printer-purchase guidance yet. An at-the-market equity facility is in place, which leaves dilution as a live possibility once manufacturing spending resumes. Interest income is also shrinking as the cash pile draws down.
The market had already been punishing the stock before this report. Shares fell 41.3% from the $5.09 open after the August report to $2.99. That leaves them 13.6% below the 200-day moving average of $3.46, with Earnings Whispers price and AVWAP trends both negative. Investor sentiment remains positive but weakened meaningfully, sliding to 0.17 from 0.39. The second guidance raise was not enough to keep enthusiasm from fading as hardware timelines stretched.
The bottom line is that Hyliion is executing well as a government-funded R&D contractor, with rising revenue, a growing military pipeline and tighter cost control. Investors are paying for a commercial power-generation business, however, and that business slipped again this quarter. Until the first commercial deployment is completed, the 200-kW target is met and 2027 capacity plans are funded without heavy dilution, the beat-and-raise pattern is unlikely to outweigh the doubts reflected in the stock's slide.
Read our earnings preview for Hyliion Holdings Corp.: https://www.earningswhispers.com/article/HYLN/22744
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-10 | |
| Nov-03 | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 | |
| Sep-16 | |
| Sep-08 |
