LPA Must Prove Its Lima Sur Sale And Mexico Pivot Can Close A Deep Valuation Gap
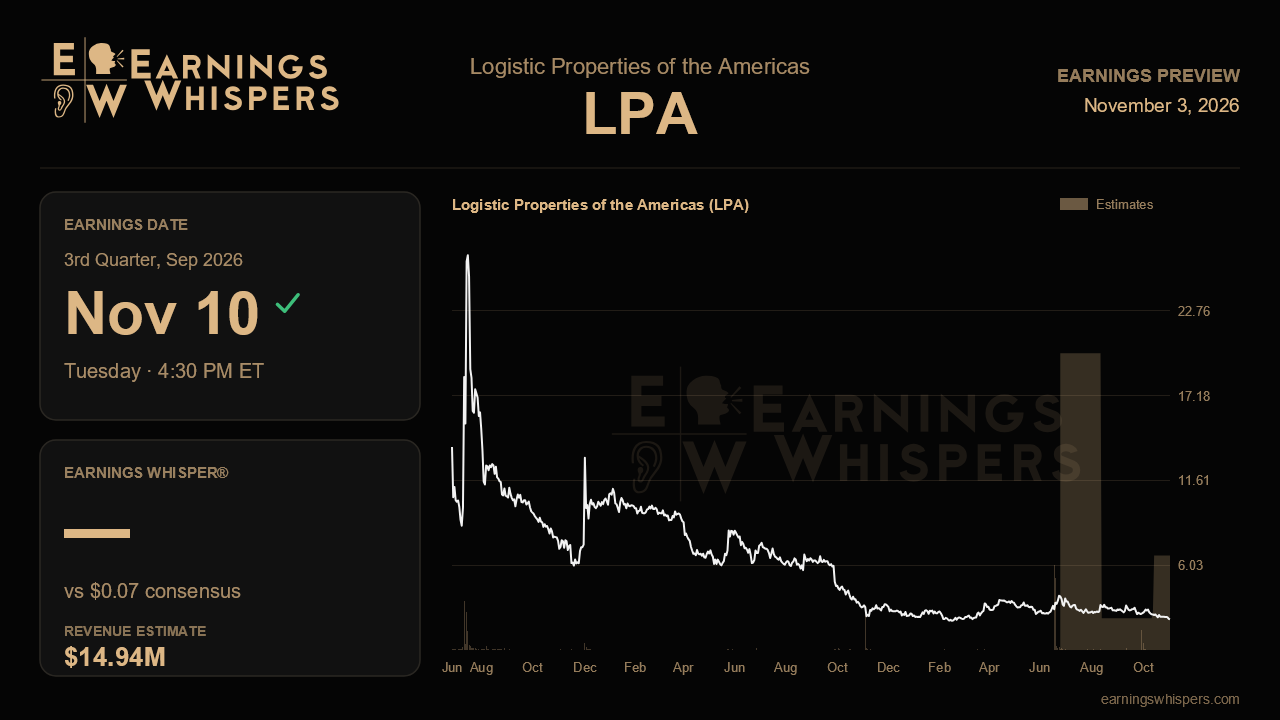
Last quarter, Logistic Properties of the Americas delivered what management framed as a breakthrough: a $145 million sale of Lima Sur Park at roughly a 7% cap rate and about 18% above carrying value, with proceeds earmarked for Mexico. The market has not been impressed. Shares have fallen about 33% since that report while the S&P 500 slipped less than 3%. At $2.47, the stock trades at well under a third of management's stated intrinsic value of $8.62 per share. The third-quarter report, due after the close on November 10, needs to show that the capital recycling story is creating value rather than simply shrinking the portfolio.
The Street expects revenue of about $14.9 million, up 16% from a year ago and only slightly above the $14.7 million reported last quarter. That would be a clear slowdown from the 26.1% growth posted in the second quarter, which had accelerated from 21.6% in the first. Part of that cooling likely reflects the sale of a rent-producing asset before the Mexico money is fully at work. Consensus earnings of $0.07 per share would be down about 53% from $0.15 a year ago. That still marks a swing back to profit after last quarter's $0.10 loss. For a real estate company, per-share earnings can swing with gains, currency moves and transaction costs, so the operating metrics matter more than the headline number. Management has not issued formal guidance to compare with these estimates.
The first test is whether the organic engine keeps running. Same-property NOI growth improved to 14.5% last quarter and average rent per square foot rose 10% to $8.88. Management warned that rent gains would be smaller in the second half because fewer leases are coming up for renewal. A modest slowdown in rent growth would therefore fit the plan. A sharp drop in occupancy or same-property NOI would not. Peru's rental growth of more than 50%, driven by the PepsiCo lease and positive re-leasing spreads, is the benchmark to watch now that Lima Sur is gone. The two Callao buildings, 92% pre-leased at yields near 13%, were expected to add about $1.3 million of NOI this quarter. Seeing that show up would be concrete evidence that development is delivering.
The second test is the Mexico redeployment. Roughly $65 million of net proceeds is meant to fund programmatic purchases at Central Park 57 under a $200 million agreement, at targeted cap rates of 8% to 9%. That would be a solid upgrade over the 7% at which Lima Sur was sold. Investors should look for progress on closings and on the new fee income from managing Lima Sur for Fibra Prime. That fee stream should begin to appear as a recurring line item. The challenge is that management itself flagged softer Mexican demand this year, especially in northern markets clouded by the unresolved USMCA talks. Slow deployment would leave cash idle and earnings diluted for longer.
Currency is a further swing factor. Last quarter, Colombia's reported growth of 29.3% shrank to roughly 11% once the peso's strength was stripped out. With about a fifth of the portfolio unhedged, investors should separate genuine leasing gains from exchange-rate help.
Sentiment has cooled, falling to about 22% bullish from roughly 38% heading into the last report. The stock sits below its 200-day moving average of $3.05 and only about 5% above its post-report low of $2.35. Expectations look subdued, which lowers the bar somewhat. Still, the discount to book value suggests investors doubt that the stated asset values can be realized. That makes the Mexico redeployment the central issue. If management can show proceeds moving into higher-yielding assets while same-property NOI holds up, last quarter's optimism remains intact. If deployment stalls and growth slows faster than the planned easing in rent gains, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-27 | |
| Oct-22 | |
| Oct-05 | |
| Sep-30 | |
| Sep-21 | |
| Sep-14 | |
| Sep-11 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 | |
| Jun-17 | |
| Jun-08 | |
| May-26 |
