LPA Beats On EPS, But Slowing Organic Growth And A Mexico Delay To 2027 Leave Investors Waiting Through An Earnings Gap
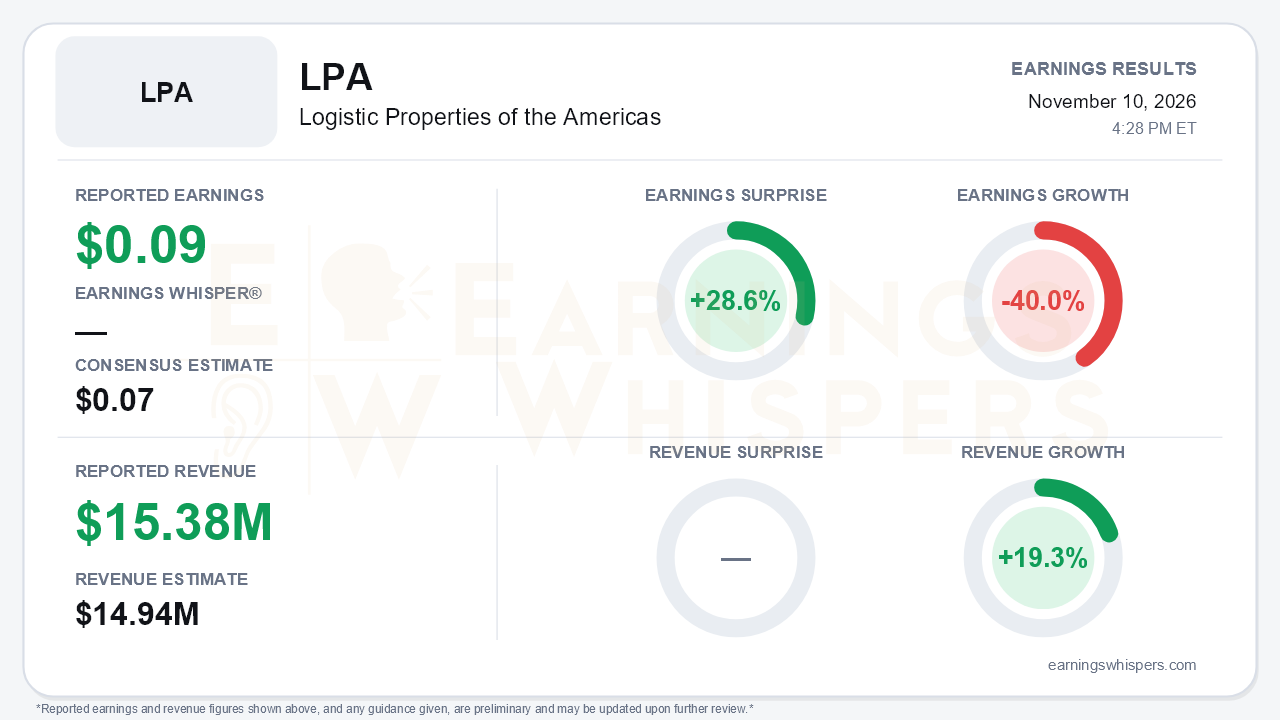
Logistic Properties of the Americas (NYSE American: LPA) cleared a low bar in the third quarter. It reported earnings of $0.09 per share against a $0.07 consensus, a 28.6% surprise. Revenue of $15.38 million topped the $14.94 million estimate by 2.9% and rose 19.3% year over year. The beat, however, is not the real story. Earnings fell 40.0% from a year ago, organic growth is visibly cooling, and the company is in the middle of selling roughly 42% of its gross property value. The proceeds will not be fully redeployed until what management now calls a 'transformational' 2027. That timing gap between monetization and reinvestment is the central tension in the LPA setup.
The quality of the quarter deserves scrutiny. Revenue growth slowed to 19.3% from 26.1% in the second quarter, 21.6% in the first and 23.3% in the fourth quarter of 2025. NOI growth decelerated for a third straight quarter, to 21.1% from 27%, 28.6% and 29.8% across the prior three calls. Excluding currency, NOI growth fell more sharply, to 14.2% from 23% in the second quarter. Same-property NOI growth eased to 11.9% from 14.5%.
Investment property operating expenses jumped 54.6% to $2.8 million as new Callao facilities ramped in Peru. NOI margins in Peru and Colombia slipped modestly from the prior quarter. Below the property line, G&A rose to $4.7 million, partly on one-time professional fees. Financing costs roughly doubled to $10.1 million, including a $1.3 million prepayment penalty. The call also cited a $10.2 million valuation gain from compressed Costa Rica cap rates. Taken together, the bottom line is noisy and should not be read as a clean run-rate.
The underlying assets still look healthy. Stabilized occupancy held at 100% for a fourth consecutive quarter, and average rent reached $9.00 per square foot, up 10.6%. That rent gain extends a steady climb from 9.8% growth in the first quarter and 10% in the second. Colombia's ex-FX revenue growth improved to 16.2% from about 11%. Peru and Colombia each posted rental growth above 45%, though Peru's pace eased from 50.4%, and Costa Rica grew just 4.2%. G&A fell to 30.3% of revenue from 34.9%, and management guided for further dilution in the fourth quarter and 2027. One less-flattering detail is that the weighted average remaining lease term shortened to 4.2 years from 4.7.
The forward story rests on capital recycling.
- **Asset sales:** The Lima Sur sale closed at $145 million, and agreements are in place to sell Aurora for $6.7 million and Calle 80 to Bancolombia for $152 million. The three deals total just over $300 million at a roughly 10–12% premium to appraisal and a blended cap rate of about 7.7%.
- **Debt reduction:** Roughly $115 million of asset-level debt is being retired, including expensive floating-rate COP debt.
- **Redeployment:** About $137 million of net equity proceeds is earmarked mainly for Mexico, starting with the Central Park 57 property.
- **Capital-light development:** The $85 million Panamericana Sur park gives LPA control and fee income for an 11% equity stake.
The credibility issue is timing. Management had pointed to CP57 purchases beginning in the second or third quarter of 2026. That slipped to a 12–18-month window on the second-quarter call and is now framed as a 2027 event. Selling stabilized, income-producing assets before the capital is reinvested implies near-term earnings dilution. Bears also have legitimate ammunition on several other fronts:
- higher-for-longer rates;
- Colombian fiscal reform;
- tariff and USMCA exposure, which management cited in steering away from export-oriented Mexican assets;
- accounting complexity from Lima Sur remaining on the balance sheet as a financing liability.
The market has been unforgiving. Shares at $2.40 are down 35.0% since opening at $3.69 after the August report and sit 20.9% below the 200-day moving average of $3.04. The Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment remains positive but weakened meaningfully, falling from 0.38 to 0.17. The disconnect with management's figures is stark. Management cited book value of roughly $8.86 per share, which it argues is validated by the cash sale prices, and cash of about $3.84 per share. Yet there is still no buyback or dividend to close that discount, leaving investors to fund the wait for Mexico themselves.
The bottom line is that LPA delivered a beat and proved its assets command premium private-market prices, but the operating story is decelerating and the payoff has been pushed into 2027. Management's tone has rarely been more confident, and the balance sheet is materially stronger. Until the proceeds are deployed accretively, or returned to shareholders, the stock's steep discount to stated book value and cash per share is likely to reflect skepticism about execution rather than about asset quality.
Read our earnings preview for Logistic Properties of the Americas: https://www.earningswhispers.com/article/LPA/22749
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-10 | |
| Nov-03 | |
| Oct-27 | |
| Oct-22 | |
| Oct-05 | |
| Sep-30 | |
| Sep-21 | |
| Sep-14 | |
| Sep-11 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 | |
| Jun-17 |
