Mercury Systems Must Prove Record Backlog Can Convert As Stock Slides Toward Lows
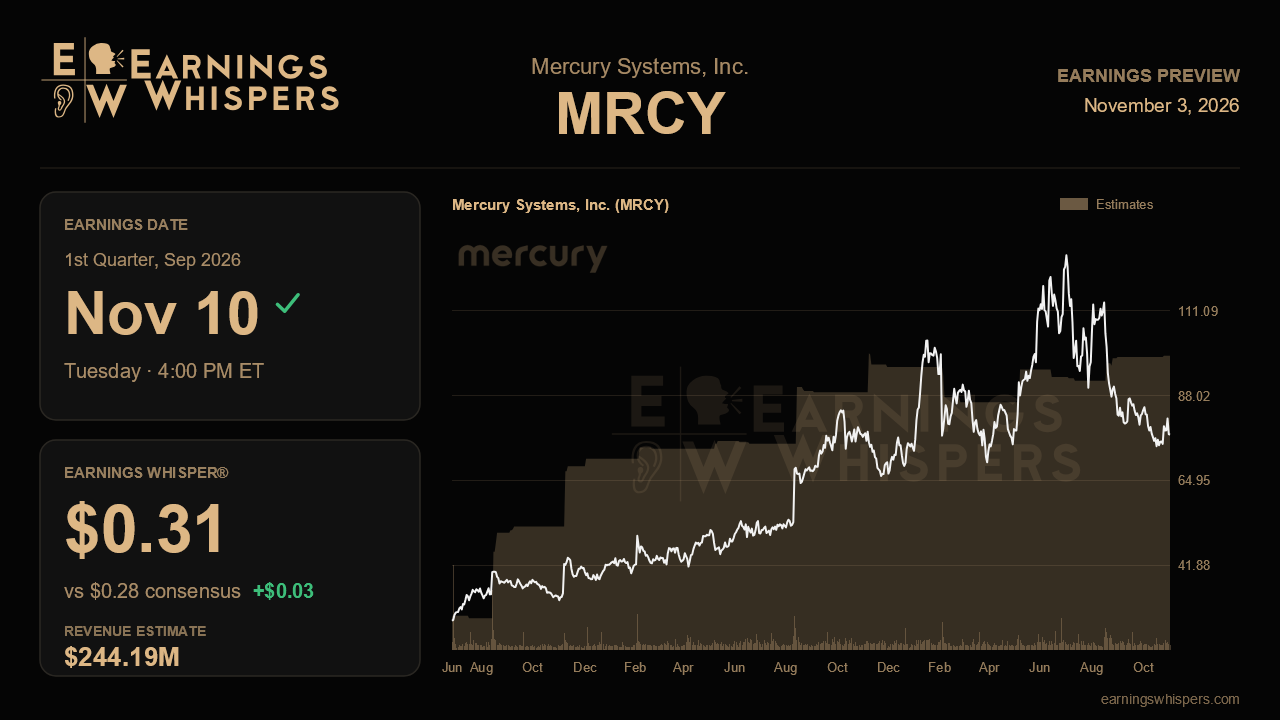
Mercury Systems heads into its fiscal first-quarter report with one of the more striking disconnects in defense electronics. Three months ago, management delivered its most confident call in a year: record bookings, a record backlog, a raised long-term growth target and a first look at fiscal 2027 and 2028. Since then the shares have fallen about 26%, while the S&P 500 slipped only 2.4%. The report due after the close on November 10 is the first chance to show whether that order surge is turning into revenue and profit, or whether the market's doubts were justified.
The Street expects earnings of $0.28 a share on revenue of about $244.2 million. That revenue figure implies growth of roughly 8.4% from the $225.2 million posted a year ago, which is solid but not spectacular, and a meaningful step down from the $289.8 million reported last quarter. The earnings bar looks far more demanding on a percentage basis, since the year-ago quarter produced just $0.05 a share. The whisper number sits at $0.31, a few cents above consensus, suggesting some investors expect the margin story to show up early in the year.
Guidance is where the tension sharpens. Management reaffirmed its target of roughly $1.10 billion in fiscal 2027 revenue, yet consensus sits at about $1.06 billion, below the company's own outlook. Analysts, in other words, are not fully buying the plan. That also means a first quarter running near $244 million leaves the company leaning on a heavier second half to reach $1.1 billion, so commentary on quarterly cadence matters as much as the headline numbers. A clean beat paired with a firm reiteration would help close that gap; anything that sounds hedged would likely validate the skeptics.
The operational test starts with backlog. Mercury exited fiscal 2026 with about $1.9 billion in backlog, up 38% from a year earlier, after booking a record $660 million in the fourth quarter for a book-to-bill of 2.28. Book-to-bill will almost certainly fall from that level, and management itself flagged that large consolidated orders pulled some bookings forward. The more useful signal is whether backlog holds near record territory and whether the roughly $1 billion slated for the next 12 months is converting on schedule. Updates on the Palantir partnership, intended to sharpen material planning and factory throughput, would also matter, since faster conversion is the whole point and it sits outside guidance as potential upside.
Margins and cash are the likely pressure points. Management guided fiscal 2027 adjusted EBITDA approaching $200 million, about 30% growth, but the fourth quarter's EBITDA margin of 16.7% fell short of the prior year's 18.8% on mix and contract estimate effects. Evidence that profitability is trending toward the full-year plan would validate the leverage thesis. Cash will look ugly by design: management warned of an unusually large first-quarter outflow tied to material receipts and full-year free cash flow conversion of only about 35%. Investors should judge that outflow against what was promised rather than in isolation. The international business, hurt by a contract-manufacturer transition, is also due for signs of recovery within a couple of quarters.
Sentiment has nearly evaporated, dropping from about 26% bullish before the last report to essentially neutral now. The stock trades at $77.37, well below its 200-day average near $91.56 and close to the $71.61 low of its post-earnings range, far beneath the $108.56 high. That reset lowers the bar psychologically, but it does not guarantee a rebound. The central question is simple: can Mercury show that record orders are flowing through to revenue and margins at the pace needed for $1.1 billion? If yes, the gap between guidance and consensus becomes an opportunity. If not, the selloff will look like an early warning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-26 | |
| Oct-20 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Sep-16 | |
| Aug-25 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 |
