Mercury Systems Crushes Estimates And Raises FY27 Outlook, But Margin Peak And Cash Burn Temper A Record Quarter
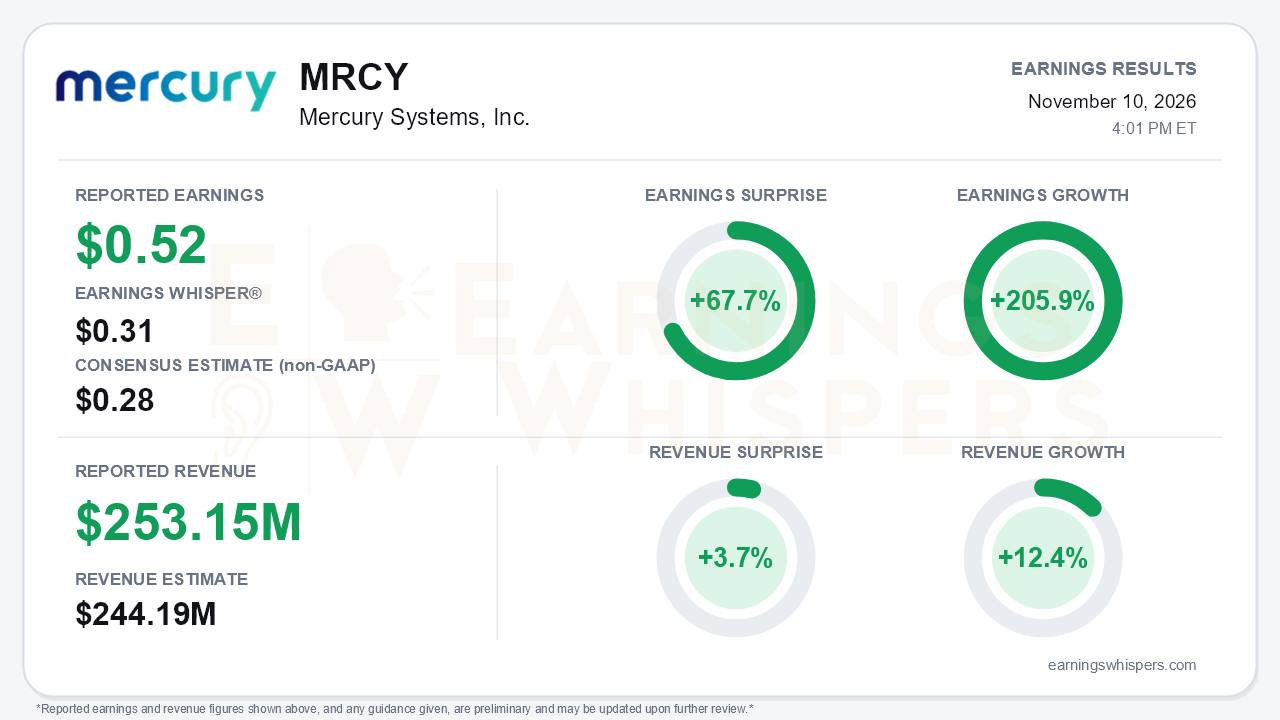
Mercury Systems opened fiscal 2027 with a decisive beat. Adjusted EPS of $0.52 topped the $0.28 consensus by 67.7% and cleared the $0.31 Earnings Whisper number. Revenue of $253.15 million beat the $244.19 million estimate by 3.7%. Earnings grew 205.9% year over year on revenue growth of 12.4%. On a GAAP basis, Mercury earned $0.21 per diluted share, reversing a $0.21 loss a year earlier. That $13 million profit replaced a $13 million loss. The more consequential development was the guidance raise: management lifted its fiscal 2027 outlook for revenue, adjusted EBITDA and free-cash-flow conversion. That marks the third consecutive call with raised targets. The central tension is that the quarter likely represents a near-term margin high and came with a meaningful cash outflow, arriving just as investors had soured on the stock.
The quality of the beat is largely real, with some caveats. Gross margin expanded 730 basis points to 35.2%. Gross profit rose to $89.2 million from $62.9 million on revenue that grew only about $28 million. Cost of revenue was essentially flat. Adjusted EBITDA rose 58.6% to $56 million, a 22.3% margin. Management had guided Q1 margins roughly in line with last year's 15.9%. The sequential trajectory is striking: 12.9% in Q2 FY26, 15.3% in Q3, 16.7% in Q4 and now 22.3%. Below the operating line, lower interest expense after debt paydown helped. An unusually small $220,000 tax provision on $13.3 million of pretax income flattered GAAP net income. Stock-based compensation in SG&A also rose to $9.3 million from $6.3 million. Those adjustments do not undermine the operating story, but they show the bottom-line swing was not purely operational.
Demand is where the quarter looks most durable. Bookings jumped 48% to a record $370 million, a 1.46 book-to-bill. Trailing twelve-month bookings reached a record $1.7 billion, up from $1.23 billion two quarters ago. Backlog approached $2.1 billion, up 44.7% year over year, after climbing from about $1.6 billion in Q3 and more than $1.9 billion in Q4. Next-12-month backlog topped $1 billion. Revenue growth of 12.4% beat management's own high-single-digit guide. Management said defense spending tailwinds are beginning to appear in bookings, including an order that arrived earlier than expected. Wins included:
- a competitive takeaway on F-35 electronic-warfare content;
- an expanded production role on an effector program;
- early Golden Dome-related missile-tracking development funding.
The raised guidance now calls for double-digit revenue growth approaching $1.1 billion. Adjusted EBITDA is guided to roughly $210 million, about 40% growth, up from approaching $200 million. Free-cash-flow conversion is guided to approach 40%, up from about 35%. The tone was notably confident; management said Mercury is "nowhere near our potential." It also stressed that the Palantir automation partnership and prime framework flowdowns remain excluded from the outlook.
Bears still have legitimate ammunition:
- **Margins:** Management attributed part of Q1's margin to favorable mix it expects to normalize. Q2 margin guidance implies only about 500 basis points of year-over-year expansion, so Q1 likely marks a near-term peak.
- **Cash:** Free cash flow was a $24 million outflow versus $4 million a year ago, driven by a roughly $32 million inventory build. Net working capital rose $33 million year over year after declining in earlier periods.
- **Bookings timing:** Continuing-resolution timing could make Q2 bookings lumpy.
- **Supply and growth drivers:** Memory supply constraints were flagged. The broad quantity-increase tailwinds have "not materialized."
- **Longer-term targets:** The FY28 reference points were not updated.
On the balance sheet, Mercury repaid $100 million of revolver debt in the quarter and $250 million over two quarters. Net debt fell to $232 million, with leverage below 1.4x. That improves flexibility, though cash dropped to $110 million from $214 million.
The market setup is more complicated than the surprise implies. Shares fell 23.9% from the $104.67 opening after the August report to $79.62 heading into this release. They touched a 52-week low of $64.37 on November 6 before rebounding nearly 24% in the days just before the print. The stock still sits about 12% below its $90.91 200-day moving average and roughly 27% below its inter-earnings high. Investor sentiment turned meaningfully weaker over the quarter, sliding from moderately positive (0.26) to roughly neutral-to-slightly-negative (-0.02). Expectations had reset lower even as the order book kept compounding. The Earnings Whispers trend readings are mixed, with price and AVWAP trends still negative while momentum has turned positive.
The bottom line is that Mercury delivered the kind of quarter that challenges the skepticism priced into the stock: record bookings and backlog, margins at target levels well ahead of guidance, and a third straight outlook raise. Investors should not extrapolate Q1's 22.3% margin, however. They should watch whether the inventory build converts into the promised cash flow. With sentiment reset and shares well below their 200-day average, the burden now shifts to execution: sustaining margin gains through mix normalization and turning a $2.1 billion backlog into cash.
Read our earnings preview for Mercury Systems, Inc.: https://www.earningswhispers.com/article/MRCY/22753
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Sep-16 | |
| Aug-25 | |
| Aug-19 | |
| Aug-19 |
