Energy Vault's Q3 Is A Waiting Room; Q4 Readiness And 2027 Outlook Matter Most
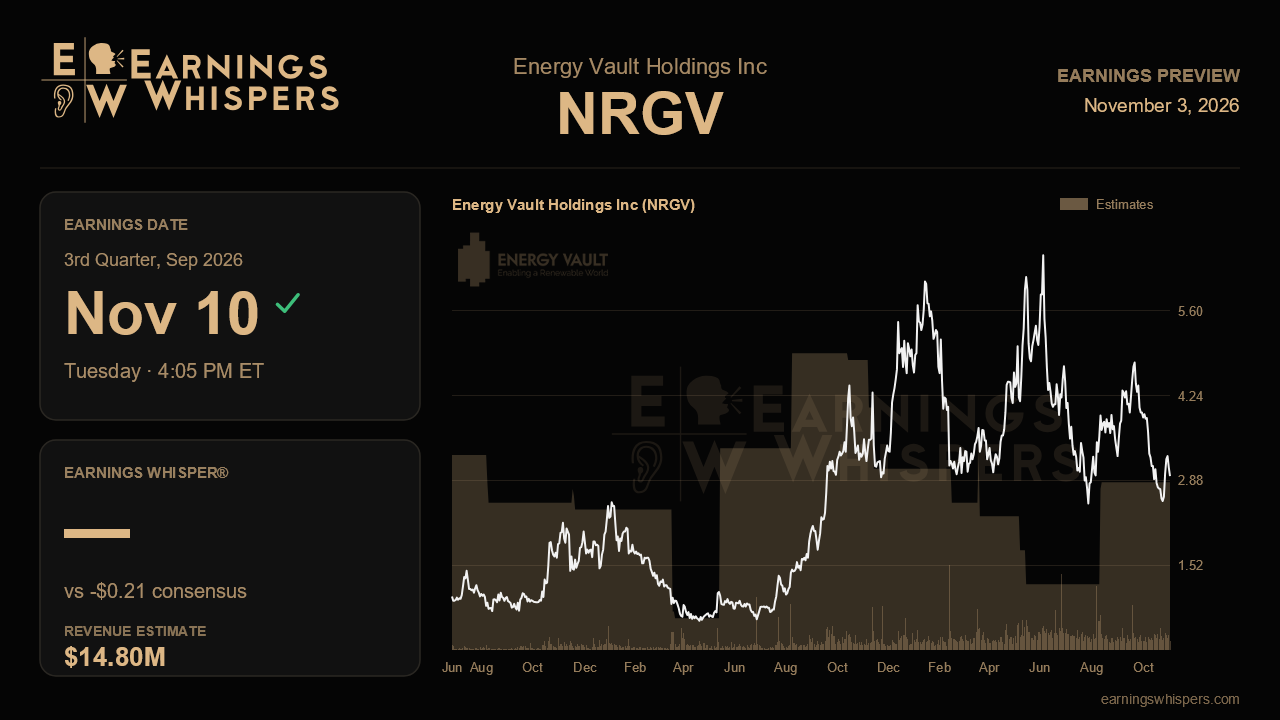
Energy Vault heads into its third-quarter report with an awkward split between what management promised and what the market believes. Last quarter the company signed the largest contract in its history, lifted its backlog by roughly 40% to about $2 billion and raised guidance on revenue, gross margin and year-end cash. Since then the stock has dropped about 29%, trailing the S&P 500 by more than 26 percentage points. The November report is where the company has to show that its headline wins are turning into deliverable revenue.
The quarter itself will look weak. Consensus calls for a loss of $0.21 per share on revenue of $14.8 million, down about 56% from $33.3 million a year ago and below the $17.4 million reported last quarter. The expected loss is also wider than both the prior quarter's $0.17 and the year-ago $0.16. None of that should surprise anyone, because management has said plainly that 2026 revenue is heavily concentrated in the fourth quarter. The second and third quarters combined would come to only about $32 million. That leaves the great majority of the $270 million to $310 million full-year range to be recognized in the final three months, likely well above $200 million in a single quarter.
The Street is not fully on board. Full-year consensus of $269.8 million sits right at the bottom of management's range, which suggests analysts accept the raise only partially. That makes the tone of any guidance update more important than the third-quarter numbers. Reaffirming the range, especially with signs that milestone timing is on track, would support the case that the guidance raise was earned. Narrowing toward the low end, or shifting language about when revenue is recognized, would confirm the market's suspicion that the back-end loading carries real execution risk.
The second test is the 1.25 gigawatt behind-the-meter generation and storage agreement with a hyperscaler. Management valued it at roughly $500 million to $600 million, with a portion landing in the fourth quarter and most of it in 2027. The partner remains unnamed, so progress toward a definitive contract, firm delivery schedules or further disclosure would add credibility. Management also said backlog could approach $3 billion by year-end and promised a detailed 2027 outlook on this call. An outlook that turns that backlog into a concrete revenue path would carry more weight than anything in the September quarter. Updates on the Crusoe campus in Snyder, which management said could expand to as much as 500 megawatts, and on the Mesa del Sol plant in New Mexico would help show whether the pipeline is growing as described. Investors should also listen for any change in the company's view that the behind-the-meter design shields it from the Texas data center moratorium.
The balance sheet deserves equal scrutiny. Cash rose to $148 million last quarter, the sixth straight quarterly increase, but the company drew on a receivables facility and issued a $150 million convertible note to fund working capital ahead of the fourth-quarter ramp. A build in inventory and receivables would be normal at this stage. Investors will want to know whether that build is consistent with the raised $160 million to $200 million year-end cash target. Adjusted operating expenses climbed to $23.7 million last quarter, and further increases without matching visibility on revenue would draw attention.
Sentiment has turned from slightly bullish before the last report to moderately bearish now. The shares trade at $2.95, well below the 200-day moving average near $3.92 and closer to the post-earnings low of $2.46 than the $4.90 high. That setup lowers the bar in one respect, since skepticism is already priced in. The decisive question is whether Energy Vault can show that its fourth-quarter delivery machine and 2027 roadmap are as real as last quarter's contract announcements implied.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-14 | |
| Sep-29 | |
| Sep-23 | |
| Sep-22 | |
| Sep-10 | |
| Sep-04 | |
| Sep-03 | |
| Sep-01 | |
| Aug-20 | |
| Aug-12 | |
| Aug-11 | |
| Aug-07 | |
| Jul-27 | |
| Jul-22 |
