Energy Vault Beats On EPS, But A $13 Million Quarter Leaves Its Year Riding On Q4 Deliveries And A Bold 2027 Outlook
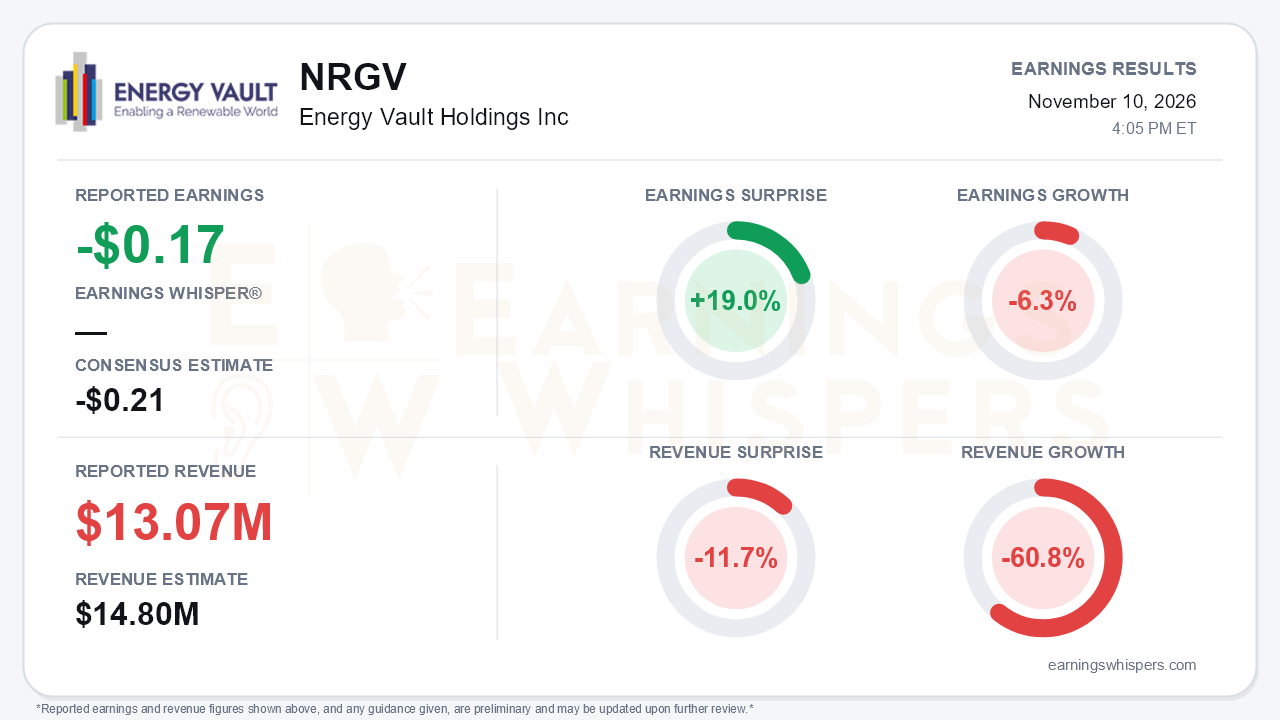
Energy Vault reported a third-quarter loss of $0.17 per share, 19.0% better than the -$0.21 consensus. That is the only clean beat in the print. Revenue of $13.07 million missed the $14.8 million consensus by 11.7% and fell 60.8% from a year ago. On a per-share basis, earnings fell 6.3% year over year as the GAAP loss widened from $0.16. Management described revenue as in line with consensus and with its planned delivery schedule, a framing that conflicts with the Street figure Earnings Whispers tracks. The central tension is that the quarter was among the company's weakest, while the forward story became considerably more ambitious. Management affirmed 2026 revenue of $290 million to $310 million and introduced preliminary 2027 guidance of $600 million to $700 million in revenue with $40 million to $50 million of positive adjusted EBITDA.
The quality of the beat deserves scrutiny. GAAP gross margin printed at 71.0%, but that figure includes a $4.3 million tariff refund. Without the refund, gross margin was 37.9%. Adjusted operating expenses rose 56% year over year to $25.2 million, and the adjusted EBITDA loss widened to $14.7 million from $6.0 million. Adjusted net loss per share was $0.14, versus $0.10 a year earlier. Revenue has now declined for two straight quarters, from $21.9 million in Q1 to $17.4 million in Q2 to $13.1 million in Q3. Nine-month revenue totals just $52.3 million, so roughly $250 million, or 75% to 80% of the full-year guide, must land in the fourth quarter. The company also trimmed the top of its 2026 GAAP gross margin outlook to 20%-22% from 20%-25%.
The balance sheet tells a more nuanced story than the headline cash figure. Total cash, including restricted cash, rose to $236 million, up from $148 million in Q2 and $103 million at year-end 2025. Much of that cash came from two sources:
- **Customer money:** contract liabilities jumped to $245.5 million from $6.6 million in December.
- **Borrowing:** long-term debt climbed to $210.7 million from $38.0 million.
Much of that cash is already committed. Advances to suppliers swelled to roughly $264 million, and stockholders' equity turned negative at $12.4 million. Management guided year-end cash to $170 million to $200 million, which implies a drawdown from Q3 levels even as the company reduced corporate recourse debt by $12 million to $221 million. Non-recourse debt is rising alongside the asset base, including the Rolls-Royce MTU engine financing and the Goshe development facility.
The call preserved a credible growth narrative built around backlog and owned assets. Backlog reached $2.3 billion as of November 10, up from about $2.0 billion in Q2 and $1.3 billion at the start of the year. Management still targets about $3 billion by year-end. Of the current backlog:
- About $800 million is build-and-transfer work.
- About $1.5 billion is build, own and operate.
Roughly 85% of the 2027 revenue midpoint appears covered by build-and-transfer backlog. Investors should note, however, that backlog includes contingent option amounts and probability-weighted variable payments. Management also raised its owned-portfolio run-rate EBITDA target to more than $200 million exiting 2028, up from $180 million.
The operating milestones that support that target include:
- Closing the 2.3 GW Goshe acquisition, which includes 350 MW ready to build.
- Formal grid interconnection approval for the 1 GWh Stoney Creek project in Australia.
- A strategic-interest designation from the Italian government for the Sulcis AI project in Sardinia.
- The start of deliveries on a 1.25 GW hybrid gas-and-storage prime-power project supporting AI compute in Texas.
Bears have legitimate ammunition here. The Texas deal introduces customer concentration, and an analyst noted that contracted build-and-transfer MWh declined sequentially.
The market was skeptical heading into the report. Earnings Whispers investor sentiment slipped from roughly neutral at 0.02 to a modestly negative -0.15. The stock was trading at $3.62 ahead of the release, down 13.4% from the $4.18 open following the August report and about 6% below its 200-day moving average of $3.86. The inter-earnings period was violent. Shares peaked at $4.90 on September 22, then collapsed to a 52-week low of $2.46 on October 23, before recovering 47% off that low. The Earnings Whispers price, sequential-growth and AVWAP trend readings are negative, consistent with a stock still repairing damage rather than one trading on the strength of its outlook.
The bottom line is that Energy Vault delivered a narrower-than-expected loss but little else in the reported quarter. Thin revenue, a refund-aided margin and widening operating losses make this a show-me setup. The bull case now rests almost entirely on forward commitments: a fourth quarter that must generate roughly five times the revenue of the first nine months combined, and a first-ever positive-EBITDA year in 2027. If the Q4 deliveries arrive on schedule, the steadily raised guidance and expanding backlog gain real credibility. If they slip, the leveraged, customer-funded balance sheet leaves little room for error.
Read our earnings preview for Energy Vault Holdings Inc: https://www.earningswhispers.com/article/NRGV/22758
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-14 | |
| Sep-29 | |
| Sep-23 | |
| Sep-22 | |
| Sep-10 | |
| Sep-04 | |
| Sep-03 | |
| Sep-01 | |
| Aug-20 | |
| Aug-12 | |
| Aug-11 | |
| Aug-07 |
