PetMed Express Faces Cash And Sales Test As Stock Trades Far Below $3 Bid
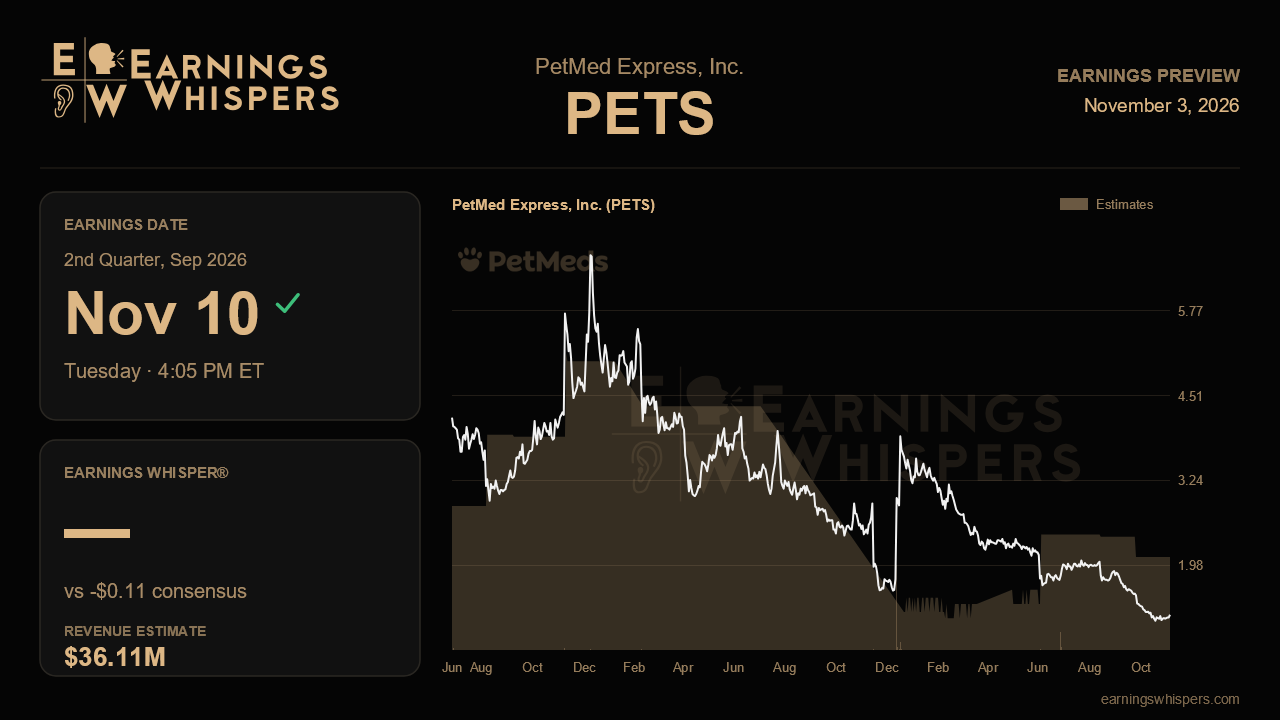
PetMed Express heads into its September-quarter report with a stock that tells a harsher story than its own operating metrics. Shares have fallen 37% since the last report, to about $1.20, which is less than half the $3.00 per share unsolicited cash proposal Silver Cape floated at the end of June. When a stock trades this far below a standing offer, the market is saying it doubts the deal will close and doubts the standalone business can stem its sales erosion before the cash runs thin. This report needs to address both doubts.
The Street is looking for a loss of $0.11 per share on revenue of $36.1 million. That would be a big improvement from the $0.41 loss a year ago and the $0.28 loss last quarter, but revenue would fall 18.6% from $44.4 million and drop about $5 million from the June quarter. The pattern is unusual. Analysts expect a much narrower loss on meaningfully lower sales, which puts heavy weight on cost cuts and on any accounting effects from the $37 million headquarters sale-leaseback announced in July. Investors should check whether a beat comes from operations or from one-time items. Management does not issue formal guidance, so the only explicit framing is its familiar promise of a path back to profitability.
The last call offered two narratives at once. The efficiency story was real. Customer acquisition cost fell to $60 from $71, about 70,000 new customers came aboard, and management said that figure had been rising for several quarters. Recurring autoship and membership revenue climbed to 61.5% of gross sales. Advertising fell 30% and G&A fell 13.5%. Against that, net sales dropped 19.9%, a worse decline than the prior quarter's 15.6%. That undercut earlier talk of green shoots. Gross margin slipped to 27.6% on lower manufacturer rebates, and the adjusted EBITDA loss widened to $3.4 million. For the cleanup narrative to hold, the decline rate needs to keep easing, and consensus already assumes slight moderation. A drop worse than 20% would suggest the cheaper customers being acquired are not offsetting weaker prescription demand.
The new catalysts deserve scrutiny because this is the first full quarter they can show up. The Rural King white-label pharmacy, launched in July across more than 150 stores in 17 states, is the company's first large-scale B2B test. Even a modest early contribution, or evidence of order volume and customer sign-ups, would matter more than its dollar size because it points to a growth channel beyond direct consumer marketing. The SAP system and new call center platform should start yielding efficiencies rather than transition costs. The faster West Coast freight deal could support retention. Gross margin is the swing factor. A rebound toward 30% would suggest the rebate pressure was temporary, while another reading near 27% would make profitability far harder to reach at shrinking volume.
Cash may be the most important single number. The balance fell to $13.1 million in June from $21.4 million in March, a burn rate that clearly drove the decision to sell the headquarters. The sale-leaseback should restore liquidity, but investors will want to see underlying burn slow, because a 10-year lease adds a fixed cost to a smaller business. Any update on the Silver Cape proposal or the still-unfinished permanent CEO search will also weigh heavily.
Sentiment has soured, with bearish readings deeper than ahead of the prior report. The stock is sitting just above its post-earnings low of $1.15 and far below its 200-day average of $2.11. That sets a low bar, but credibility is thin. The core question is whether improving unit economics and new channels can finally slow the revenue slide before the balance sheet forces harder choices. Narrower losses alone will not answer it. Steadier sales, firmer margins and slower cash burn would.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| Nov-09 | |
| Nov-03 | |
| Oct-27 | |
| Oct-02 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Jul-30 | |
| Jul-23 |
