PetMed Express Misses As Cost Cuts Narrow The Loss But Sales Stabilization Breaks
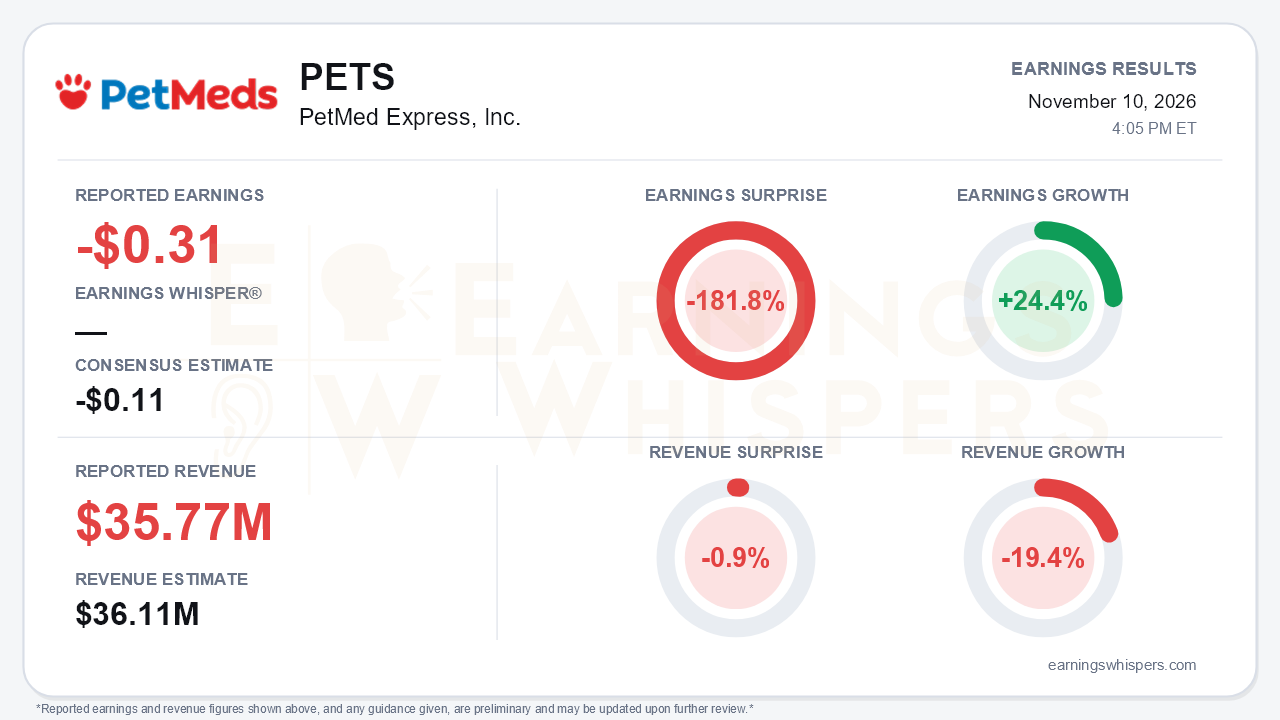
PetMed Express (NASDAQ: PETS) posted a fiscal second-quarter loss of $0.31 per share, far worse than the consensus estimate for a $0.11 loss, a negative surprise of 181.8%. Revenue of $35.77 million missed the $36.11 million consensus by 0.9% and fell 19.4% year over year. On paper, earnings improved 24.4% from a year earlier as the net loss narrowed from $0.41 per share. That improvement is the least important part of the quarter. Its premise was that the business had stabilized, and that premise did not survive the quarter. Sales dropped roughly 13% sequentially from $41.0 million in the first quarter, ending a three-quarter run above $40 million that management had held up as evidence of a floor.
The narrower GAAP loss deserves scrutiny. The $2.1 million improvement in net loss came almost entirely from cutting spending. G&A fell 15.6% to $12.0 million, and advertising was cut 52% to $2.1 million. The prior-year period also carried about $3.3 million of investigation-related professional fees and severance that did not recur. Strip those items out and the operating picture worsened. Adjusted EBITDA slipped to a $3.6 million loss from a $2.3 million loss a year ago and $3.4 million in the first quarter. Gross profit fell to $9.8 million as margin eased to 27.4% from 28.0% a year ago, pressured by unfavorable mix, lower manufacturer rebates and heavier promotional usage. The company is shrinking its losses on the expense line while the gross-profit engine keeps contracting.
The call made clear that the advertising cuts removed volume, not just waste. New customer additions fell to roughly 41,000 from about 70,000 in the first quarter, a figure previously described as trending upward. Marketing efficiency did improve. Customer acquisition cost dropped to $51 from $60 last quarter and $71 a year ago, a 32% annual decline that CEO Jeff Willard highlighted. But cheaper customers do little good if far fewer of them arrive, and a pharmacy whose revenue base is eroding cannot cost-cut its way to sustainable profitability. The tone shift was notable. The interim leadership's talk of stabilization and green shoots gave way to Willard's blunter admission that too few customers are choosing PetMeds. He framed the recovery as a multi-year effort that puts profitability before growth. No formal guidance was offered.
There are real catalysts in the new plan. A permanent CEO with a turnaround background replaces the interim period. The strategy has four fronts: brand repositioning, marketing efficiency, website conversion and retention. Generics are framed as a margin lever, and the company is pruning its food and accessories assortment. The white-label pharmacy channel also widened, adding Pet Supermarket after the July Rural King launch, and management promised new KPIs in coming quarters. These are credible building blocks, but they are plans, not results.
The balance sheet is where bears have their strongest ammunition. Cash fell to $11.4 million from $13.1 million in the first quarter and $21.4 million at fiscal year-end. Operations used $8.7 million in six months, and that figure was flattered by a $7.3 million inventory drawdown that cannot repeat indefinitely. Current liabilities of $42.4 million, including $18.9 million of sales tax payable, now exceed current assets of $25.3 million. That makes the Delray Beach sale-leaseback critical. A $37 million transaction described as a definitive agreement last quarter is now characterized only as "working towards a transaction... on terms that reflect the asset's value," a softening that suggests the deal is being reworked or is at risk. The SilverCape $3-per-share proposal also went unaddressed on the call.
The market had been pricing deterioration well before the report. Shares fell 34.6% from the $1.91 opening after the August release to $1.25. That leaves the stock about 39% below its 200-day moving average of $2.06 and only 8.7% above the October 16 52-week low of $1.15. Investor sentiment, already negative, deteriorated further from -0.12 to -0.26, a meaningful but not extreme shift. The Earnings Whispers trend signals are mostly negative, with price, sequential growth and AVWAP all pointing lower.
The bottom line is that PetMed delivered a narrower loss built on spending cuts while the metrics that matter moved the wrong way. Revenue, customer additions, gross margin, adjusted EBITDA and cash all weakened sequentially. The new CEO's plan is coherent, but by his own description it is a multi-year project, and a shrinking cash cushion paired with an uncertain sale-leaseback gives the company limited time to prove that leaner can also mean viable.
Read our earnings preview for PetMed Express, Inc.: https://www.earningswhispers.com/article/PETS/22759
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| Nov-09 | |
| Nov-03 | |
| Oct-27 | |
| Oct-02 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Jul-30 | |
| Jul-23 |
