Amneal Beats And Raises Again, But Cash Flow, Leverage, And A Pulled-Forward Quarter Temper The Story
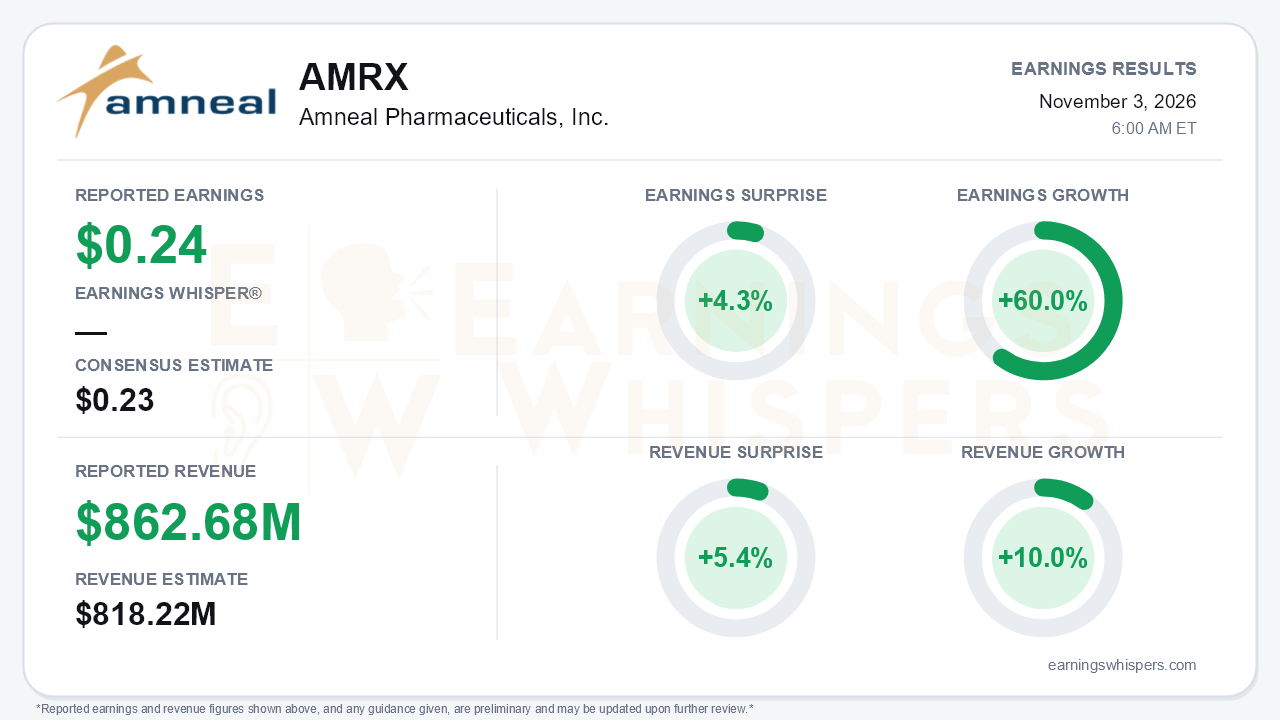
Amneal Pharmaceuticals delivered its strongest quarter of 2026 and raised full-year guidance for a third straight time. The quality of the beat still deserves scrutiny. On Earnings Whispers' normalized basis, the company earned $0.24 per share, topping the $0.23 consensus by 4.3% and growing 60.0% from a year ago. Revenue of $862.68 million beat the $818.22 million consensus by 5.4% and rose 10.0%. Amneal's own adjusted EPS was $0.26, up 53%. On a GAAP basis, the company swung to a $0.06 loss from a $0.01 profit. That loss reflects Kashiv acquisition and integration costs, a $14 million accretion charge on redeemable non-controlling interests, a tax receivable agreement swing, and a higher post-deal share count. The central tension is clear: earnings power is accelerating, while cash generation and the balance sheet are moving the other way.
The operating improvement is real. Adjusted EBITDA rose 30% to $207 million, accelerating from 12% growth in Q2 and 19% in Q1. Affordable Medicines grew 19% to $547 million, a sharp step up from 13% in Q2 and 2% in Q1, with new launches contributing $54 million. Specialty grew 20% to $150 million, driven by CREXONT, the BREKIYA autoinjector, and UNITHROID. That growth stands out because the original 2026 plan assumed flat Specialty revenue. The segment's adjusted gross margin reached 81.8%. AvKARE fell 17% against a non-recurring launch in the prior-year quarter, which management had flagged in advance.
The headline growth flatters the run rate, however. Management acknowledged that roughly $40 million of Affordable Medicines revenue came from favorable biosimilar order timing, about half of that segment's year-over-year dollar gain. Consolidated adjusted gross margin also slipped to 43.2% from 46.2% in Q2, even as the company lifted its full-year margin outlook to about 46.5%. The guidance math reinforces the point. The new ranges imply fourth-quarter revenue near $820 million and adjusted EBITDA around $190 million, both below Q3 levels, despite a lanreotide launch. Investors should read Q3 as partly borrowed from the future rather than a clean new baseline.
The guidance raise itself was substantive. Full-year revenue moved to $3.15–$3.25 billion, adjusted EBITDA to $800–$815 million, and adjusted EPS to $1.04–$1.08. EBITDA guidance has now climbed from an original $720–$760 million. The catalyst list also lengthened. Lanreotide launched in late September with about $7 million of revenue, and management expects that figure to multiply in Q4 as it targets 30–40% share. Because Kashiv originated the product, Amneal keeps all of the economics. BREKIYA is running at double internal expectations and is expected to nearly double again in 2027. Amneal also secured $60 million in New Jersey tax credits to support its Kashiv synergy target.
Bears have legitimate ammunition on the cash and timing side. Operating cash flow guidance was the only metric cut, lowered $25 million at the midpoint to $325–$375 million on inventory builds and collections slipping into 2027. Nine-month operating cash flow was just $50 million, versus $210 million a year earlier. Cash fell to $157 million, and the company drew $180 million on its revolver. Net leverage rose to 3.9x from 3.5x at year-end, against a 3.6x year-end target and a reaffirmed goal of below 3x by 2028. The Kashiv deal also added $383 million of related-party contingent consideration. Separately, the Xolair biosimilar has drifted from a hoped-for very early 2027 launch to late in the second half of 2027, pending a patent settlement.
The market had largely priced in the improving trajectory before the report. Shares entered earnings at $20.44, up 10.4% since the open after the July report. That was about 30% above the 200-day moving average and only 5.7% below a 52-week high of $21.68 set the day before the release. The stock had rallied more than 23% off its September low. The Earnings Whispers trend signals were uniformly positive. Investor sentiment, however, remained positive but weakened, slipping from 0.22 to 0.11. That suggests enthusiasm was cooling even as the price climbed, and expectations were elevated enough that an "in-line" guidance raise offered little cushion.
The bottom line is that Amneal's operating story got better this quarter. Growth across Affordable Medicines and Specialty is accelerating, margins are expanding for the year, and Kashiv has added a fully owned injectable franchise. The quarter was still not as clean as the beat implies. Order timing inflated revenue, implied Q4 guidance steps down, and cash flow and leverage worsened. With the stock already near its highs, the next leg depends on lanreotide and the 2027 launch wave turning EBITDA gains into cash.
Read our earnings preview for Amneal Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/AMRX/21455
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 7 hours | |
| Oct-26 | |
| Oct-08 | |
| Sep-21 | |
| Sep-18 | |
| Aug-10 | |
| Jul-30 | |
| Jul-30 | |
| Jul-17 | |
| Jul-09 | |
| Jun-29 | |
| Jun-10 | |
| Jun-05 |
