Satellogic Must Prove Its First Profitable Quarter Was No Fluke As Stock Slumps
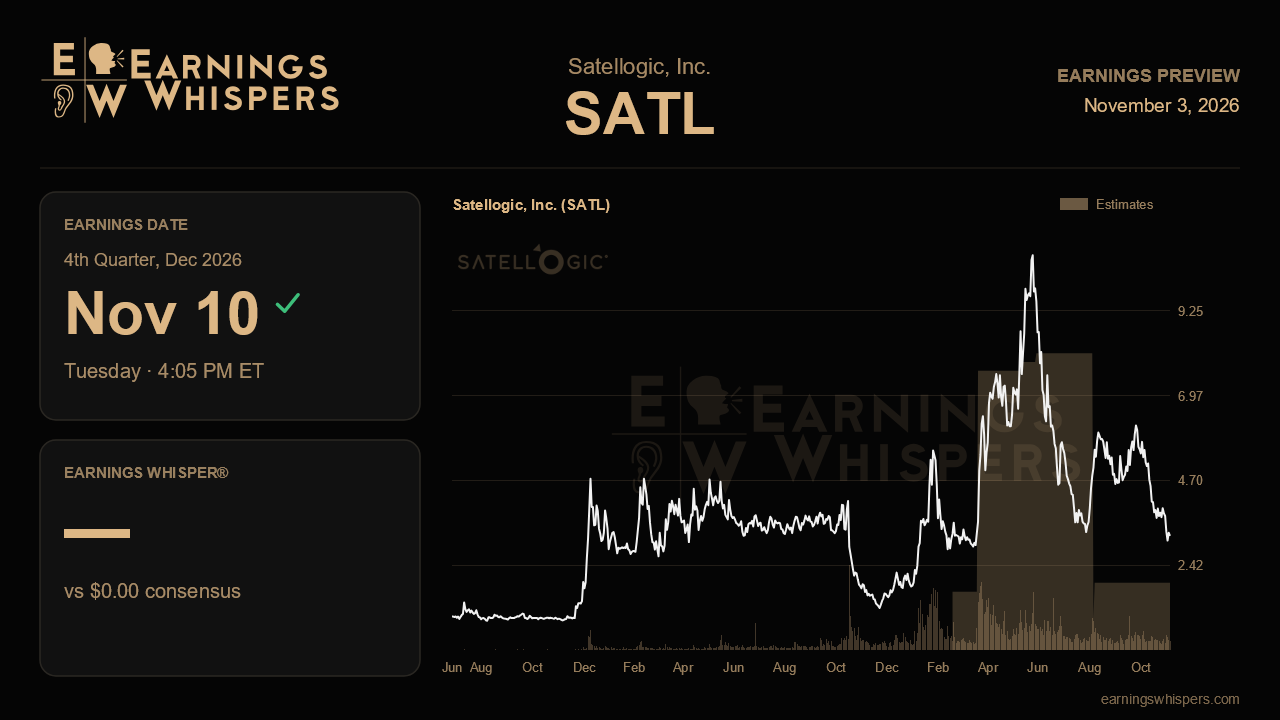
Satellogic delivered the best quarter in its history last time out, posting its first positive operating income and adjusted EBITDA, and the market responded by cutting the stock by more than a third. That disconnect is the story heading into the third-quarter report on November 10 after the close. The company now has to show that the inflection was structural, driven by recurring subscription revenue and a fattening backlog, rather than a one-time windfall from lumpy satellite sales.
The Street is not asking for a repeat of the second quarter. Consensus calls for revenue of about $14.0 million, down from $15.9 million last quarter but up roughly 286% from the $3.6 million reported a year ago. The expected loss is a penny per share, a meaningful improvement from the 13-cent loss last quarter, though that figure was inflated by a $19.7 million non-cash fair-value remeasurement tied to the share price. The modest sequential revenue step-down is a sensible acknowledgment that the prior period benefited from hardware events such as the delivery of the first satellite in Portugal's $18 million program and the closing of a $12 million in-orbit transaction. No formal quarterly guidance is on the table, so the burden falls on management's broader framing: 2026 as a major step toward sustained profitability, with positive free cash flow targeted for 2027 once the Merlin satellite enters service.
The most telling number may be data and analytics revenue, which jumped 54% sequentially to $7.1 million as the Aleph Observer platform turned one-off imagery buyers into multi-quarter subscribers. If that line holds or grows, it would confirm that the business is shifting toward recurring revenue that can carry its 82% gross margin even in quarters without big satellite deliveries. Backlog is the second test. Remaining performance obligations rose to $80.7 million, with the next-twelve-month portion climbing to $45.8 million, which on its own implies more than $11 million of revenue per quarter. Further growth there, ideally with more defense deals following the more than $18 million agreement that moved from trial to full deployment in under six months, would validate management's claim that sovereign sales cycles are shortening. A shrinking backlog alongside weaker revenue would challenge it.
Profitability and cash are the swing factors. Keeping adjusted EBITDA positive on lower revenue would demonstrate genuine operating leverage, while a slide back into losses would suggest the second quarter leaned heavily on mix. Cash fell from $121.9 million to $112.8 million on Merlin spending, and GAAP operating cash flow turned negative at $8.6 million, so the pace of burn matters. Merlin itself was slated for an October launch, and any update on its status and early performance will weigh heavily given how central it is to the 2027 cash flow target. The company is also operating under an interim CFO following Rick Dunn's August departure, and progress on a permanent hire would ease one governance concern.
Sentiment has cooled sharply, with bullish readings slipping from 23.5% before the last report to just 5.5% now. The stock, at $3.08, sits essentially at its post-earnings low of $3.06 and far below its 200-day moving average of $5.30, having traded as high as $6.45 since the last report. Expectations, in other words, look depressed relative to the operating trend management described.
That sets up a clear question. If recurring revenue keeps climbing, backlog expands and EBITDA stays near breakeven or better without the boost of a large hardware sale, the profitability narrative survives and the selloff looks overdone. If the second quarter proves to have been a spike powered by one-time deliveries, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 | |
| Sep-25 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 |
