Satellogic Beats On Revenue But Misses On EPS As Q2's Profit Inflection Fades And Backlog Draws Down
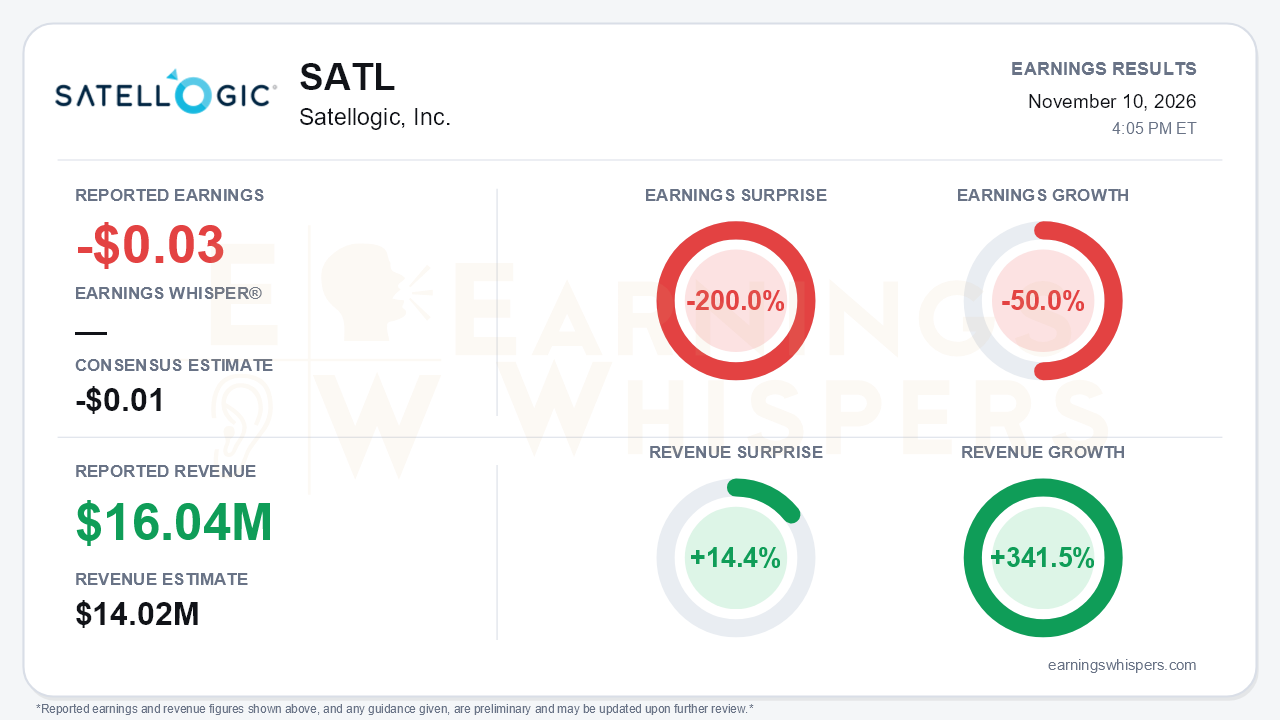
Satellogic (NASDAQ: SATL) delivered the top line bulls wanted and little of the operating leverage they had begun to expect. Third-quarter revenue of $16.04 million beat the $14.02 million consensus by 14.4% and grew 341.5% year over year, a record for the company. On Earnings Whispers' normalized basis, however, Satellogic lost $0.03 per share against a consensus loss of $0.01. That is a 200.0% miss, and earnings fell 50.0% from a year ago. Reported GAAP figures point the other way: net income of $28.3 million, or $0.14 per diluted share. That result was driven entirely by a $30.0 million non-cash gain from remeasuring warrant and earnout liabilities, which management itself called not indicative of operating performance. Strip that out and the central tension is clear. Revenue scale has arrived, but the profitability inflection Satellogic showed in the second quarter partially reversed.
The quality of the quarter deserves scrutiny. Revenue rose only from $15.9 million in Q2 to $16.0 million, so sequential growth essentially stalled after the jump from $6.1 million in Q1. The mix remains lumpy. Space Systems contributed $9.5 million, or roughly 59% of revenue, largely from delivering the second satellite under the $18 million CEiiA contract. Data & Analytics revenue more than doubled year over year to $6.6 million but slipped from $7.1 million in Q2 on lower non-cash revenue from the Palantir agreement. Costs rose $2.7 million sequentially to $18.3 million, mostly compensation and commercial build-out. As a result, Adjusted EBITDA fell to $1.2 million from $2.8 million. The operating result swung from a $0.3 million profit to a $2.3 million loss, and gross margin excluding depreciation compressed to 78% from 82%. Year over year the improvement is real: the operating loss narrowed 72% and nine-month Adjusted EBITDA is near breakeven at a $0.2 million loss versus a $15.0 million loss. Sequentially, though, the trend went backward.
Backlog and cash add to the caution. Remaining performance obligations fell to $66.9 million from $80.7 million as the CEiiA delivery was recognized. Next-12-month RPO dropped to $33.4 million from $45.8 million. Free cash flow was negative $11.7 million, and GAAP operating cash burn of $10.4 million was inflated by higher receivables. Capital spending climbed to $6.2 million as Merlin and NewSat production ramped. Cash has drifted from $121.9 million in Q1 to $106.5 million, still a solid cushion but a declining one.
The call preserved a credible growth story, and the forward catalysts are substantive. After quarter-end, Satellogic signed a roughly $37 million agreement to transfer three in-orbit satellites. It is the company's largest sovereign deal and lifts announced sovereign satellite contracts to about $67 million over the past year. Management said sovereign demand is exceeding what it expected at the start of the year. That deal is excluded from September RPO, so it should substantially refill the backlog in Q4, with transfers targeted by mid-2027. Merlin.01 launched October 1 on schedule and on budget and is in payload commissioning. Other wins include:
- a new three-year HEO imaging agreement with seven-figure annual minimums;
- an expanded Slingshot III role adding six Mark VI satellites;
- SynMax's selection as a maritime channel for Merlin data;
- launch slots booked through the first half of 2029.
The hire of former NGA director Frank Whitworth as President strengthens the defense positioning.
Bears still have legitimate ammunition. The Palantir agreement expires in November with no extension confirmed, putting part of Data & Analytics revenue at risk. Management framed Merlin revenue in the second half of 2027 as modest, with the real impact pushed to 2028 and beyond. The CFO seat remains filled on an interim basis. The pipeline language also shifted from "just under $1 billion" in Space Systems to a "greater than $550 million" qualified pipeline, with definitions that are not clearly comparable.
The market had already turned skeptical before the print. Shares stood at $3.97 in the pre-report snapshot, down 17.9% since the open following the August report and about 25% below the $5.29 200-day moving average. The stock peaked at $6.45 on September 25, then slid to a $2.76 low on November 5 before rebounding about 44% into earnings. Investor sentiment swung meaningfully, from a positive 0.235 to a negative 0.117. The Earnings Whispers trend signals lean negative on price and AVWAP, with only momentum positive, consistent with that recent bounce.
The bottom line is that Satellogic is executing on the things that build long-term value: sovereign satellite sales, Merlin's on-time launch and a deepening defense customer base. The near-term financial profile, however, softened. Flat sequential revenue, slipping margins, a shrinking backlog before the new deal and continued cash burn explain why investors are no longer giving the company the benefit of the doubt. The fourth quarter's RPO rebuild and the Palantir decision are the next tests of whether Q2's inflection was a trend or a peak.
Read our earnings preview for Satellogic, Inc.: https://www.earningswhispers.com/article/SATL/22764
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 | |
| Sep-25 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 |
