Resideo's First Standalone Quarter Tests Margins As Input Costs Hit Hardest
Resideo heads into its first report as a pure-play building technologies company with a strange combination of a low bar and a hard quarter. Management already told investors that the September quarter would absorb the worst of a sharp jump in input costs, and the stock has been marked down accordingly. The open question is whether the new team can show that the margin story built over thirteen straight quarters is bending rather than breaking.
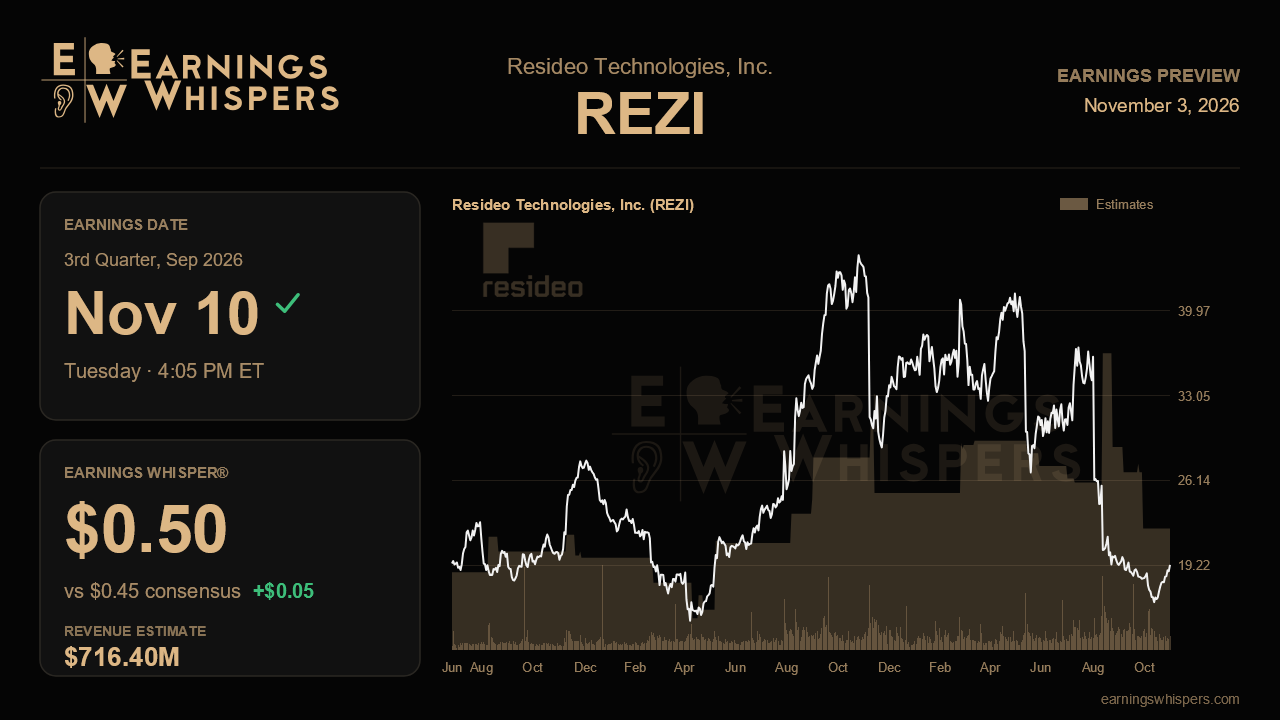
The Street expects non-GAAP earnings of $0.45 a share on revenue of about $716.4 million when results arrive after the close on November 10. The headline revenue decline of roughly 62% looks alarming, but it mostly reflects the August 3 spin-off of the ADI distribution business, not a collapse in demand. The more useful yardstick is management's own outlook: the company guided third-quarter revenue to $705 million to $730 million, and consensus sits almost exactly in the middle. The Earnings Whisper of $0.50 is a meaningful notch above consensus, suggesting some investors think cost pressures were already priced conservatively and that the remaining products and solutions business can clear the published number.
The previous call explains why this quarter matters so much. Products and solutions gross margin reached 43.6% in the second quarter, the thirteenth consecutive year-over-year gain, yet new CEO Tom Surran effectively retired that streak as a priority. Memory prices have roughly quadrupled, metals are up about 35%, and circuit board materials are in short supply, while pricing actions are not expected to fully offset the damage. A modest dip in gross margin would validate management's framing that this is a timing problem; a steep decline, or signs that pricing is falling further behind costs, would challenge the idea that the segment's margin profile is structurally intact. Investors also lose the help of tariff refunds, which flattered the prior quarter and are not expected to recur this year.
The top line carries its own tests. The standalone full-year guide of $2.9 billion to $2.95 billion implies only low-single-digit growth, which drew pushback on the last call for falling short of earlier framing. Part of that gap is a large OEM security customer bringing production in-house, a loss management sized at $40 million to $50 million for the back half. The offsets need to show up: the HVAC distribution channel just returned to growth after a long slump, and products such as the Elite Pro thermostat, combination smoke and CO detectors, and water filtration were running ahead of plan. Evidence that HVAC growth held and that the second-half launch slate, including the new smoke and CO platform and new video and intrusion products, is gaining traction would make the cautious guide look beatable. Progress on the additional $200 million or so of debt paydown targeted for the quarter would reinforce the balance-sheet narrative.
Sentiment has swung hard. Going into the prior report, bearish readings were modest at about 16%; today they stand near 81%. The shares have fallen 13.5% since the last report, trailing the S&P 500 by about ten and a half points, and at $19.25 they sit well below the 200-day average near $30, though the spin distorts that comparison. The stock trades in the upper half of its post-report range of $15.90 to $22.59, not near a breakout.
With a new CFO arriving September 1 and a fully turned-over leadership team, the report is essentially a credibility check. If gross margin pressure lands within the range management signaled and the full-year standalone EBITDA outlook of $605 million to $625 million holds, the pessimism looks overdone. If costs bite deeper or the guide slips, the market will conclude that the margin expansion era ended with the spin.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-02 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Sep-28 | |
| Sep-28 | |
| Sep-18 | |
| Aug-31 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-07 | |
| Aug-04 | |
| Aug-04 |
