QuickLogic's Flat Third Quarter Matters Less Than Proof Its Crowded Fourth Quarter Will Land
QuickLogic heads into its third-quarter report with an awkward setup. The quarter itself is supposed to be uneventful, but almost everything the company promised for 2026 now depends on what comes after it. Last quarter, management lifted the floor of its full-year growth outlook to 70% to 80% while pulling two meaningful revenue items into 2027. That left a plan unusually dependent on the fourth quarter, and the stock has been sold hard as investors weigh whether that plan is realistic.
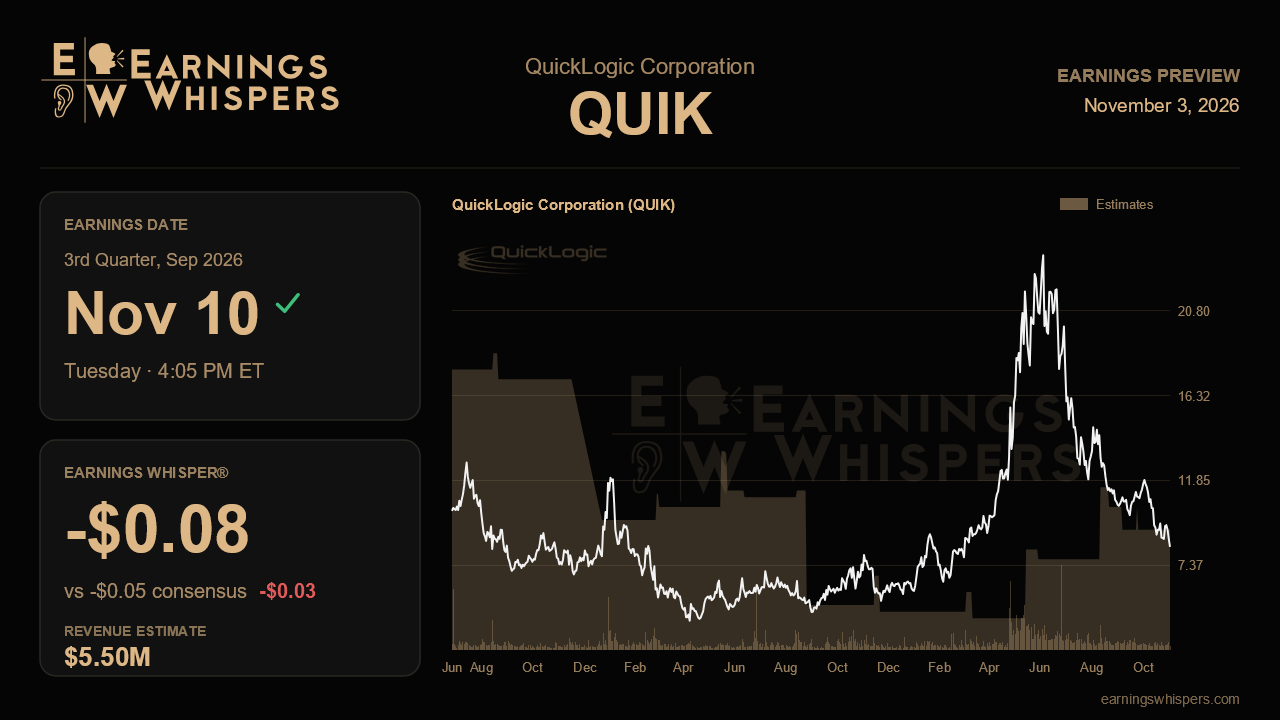
The near-term bar is clear. Wall Street expects revenue of $5.5 million, squarely at the midpoint of the $4.95 million to $6.05 million range management recently reaffirmed. That would be flat with the second quarter but about 171% above the $2.0 million trough of a year ago, a reminder of how far the business has climbed. Consensus calls for a non-GAAP loss of 5 cents a share. The whisper number is a wider 8-cent loss, which signals that the more skeptical crowd is bracing for a weaker bottom line. With such a low revenue base, that gap reflects real doubt about how quickly QuickLogic can cover its expenses. Even a modest miss on the quarter would not be the real story, though. The outlook will be.
The stall in the third quarter has a specific cause. A seven-figure contract extension with an existing customer was pushed out of 2026 entirely, because that customer is rethinking how much of its design to keep in eFPGA versus fixed logic. A commercial ASIC on Intel's 18A process was also removed from the second-half forecast. Any update suggesting those projects are back on track, or that the customer has decided in QuickLogic's favor, would ease concerns that design partners are hedging away from embedded FPGA. On the other side, the 18A to 18AP transition remains a timing wildcard. A follow-on $1 million LUT contract is targeted for fourth-quarter delivery on the newer node.
Margins are one place where the company can show progress now. Gross margin hit 46.8% last quarter, well ahead of guidance, and the third quarter is guided to roughly 47%. Delivering that figure while operating expenses rise toward the newly raised $13.7 million to $13.9 million full-year range would support management's repeated promise of non-GAAP profitability and positive cash flow in the second half. Since the full-year margin model was already cut to about 51% from 57%, the third quarter does not need to be spectacular. It does need to avoid further erosion.
The bigger question is the fourth quarter. Management said a new tranche of its U.S. government contract, which carries an $89 million ceiling, should make up a significant share of fourth-quarter revenue. The report should show whether that award is in hand or still pending. The same goes for the late-stage automotive and robotics and LEO satellite ASIC negotiations, a possible second-ever architectural IP license, the small-package mature-product qualification, and the 12LP eval kit due in the fourth quarter. Signed deals would validate the plan. Vague timelines would challenge it.
Sentiment has drifted slightly more bearish than before the last report, and the share price tells the story more forcefully. The stock has fallen about 39% since the last report while the S&P 500 slipped about 3%. At $8.33, it sits essentially at its post-earnings low and far below its 200-day moving average near $12.64, after trading as high as $24 the prior quarter. That collapse means a lot of skepticism is already priced in. A reaffirmed full-year outlook backed by a confirmed government tranche could therefore carry outsized weight. If the 70% to 80% growth target slips, however, the narrative that 2026 is QuickLogic's breakout year would be badly damaged, regardless of how the quarter itself shakes out.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 16 hours | |
| Nov-03 | |
| Oct-27 | |
| Oct-13 | |
| Oct-06 | |
| Sep-29 | |
| Sep-25 | |
| Sep-21 | |
| Sep-02 | |
| Aug-14 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-28 |
