QuickLogic Misses On Revenue A Third Straight Time And Stakes Its Year On An $8 Million Fourth Quarter
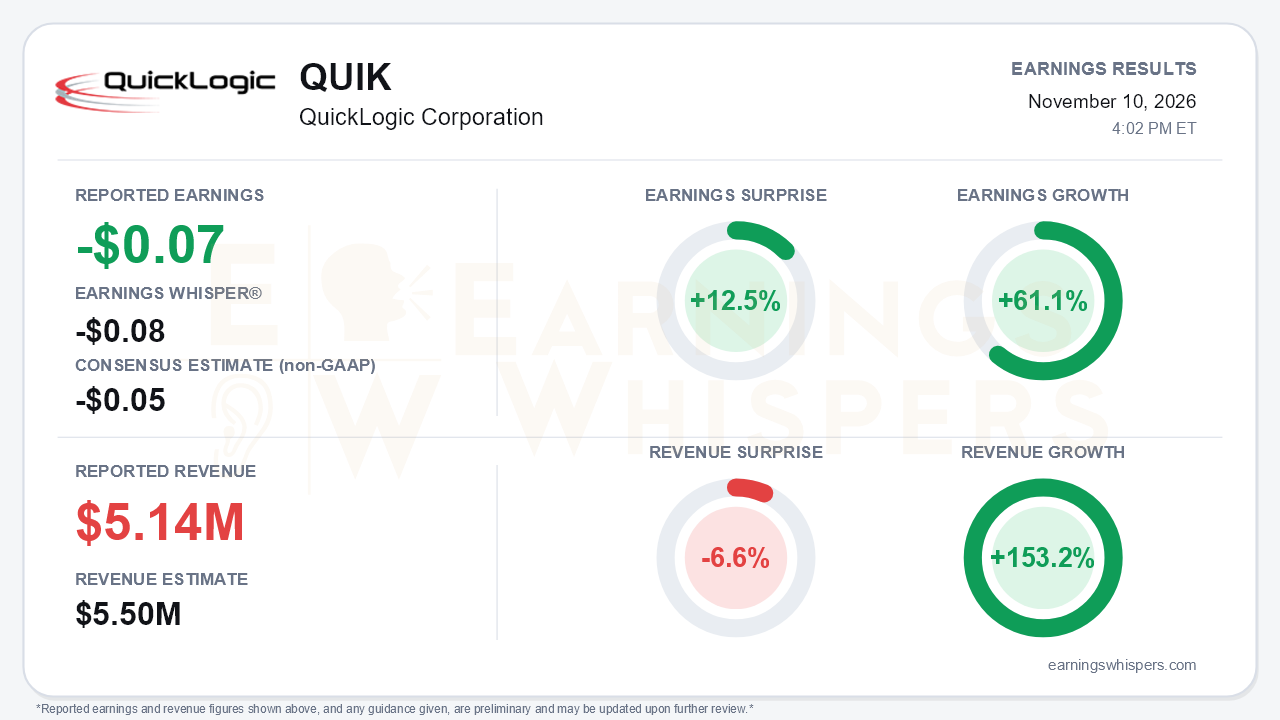
QuickLogic's fiscal third quarter produced a headline that needs unpacking. The company posted a non-GAAP loss of $0.07 per share on revenue of $5.14 million. That counts as a 12.5% beat against the Earnings Whisper number of -$0.08, but the loss was wider than the -$0.05 consensus. Revenue missed the $5.5 million consensus by 6.6%. On a year-over-year basis the comparisons look strong: earnings improved 61.1% as the loss narrowed from $0.19 a share, and revenue grew 153.2%. The central tension is that the trends that matter most right now are sequential, and they moved the wrong way. Revenue fell 6.3% from the second quarter, margins compressed, and management again asked investors to wait for a back-end-loaded finish.
The quality of the quarter deserves scrutiny. New product revenue, which drives the eFPGA and radiation-hardened story, fell 13.2% sequentially to about $4.0 million. A rebound in mature products to $1.1 million cushioned the decline. Non-GAAP gross margin slid to 41.0% from 46.8% in the second quarter, well short of the roughly 47% outlook. Management blamed fixed-cost absorption and the allocation of R&D costs into cost of goods sold. The GAAP loss more than doubled sequentially to $0.12 a share, although the second quarter had been flattered by a $950,000 gain on extinguishment of a vendor payable. Concentration remains a structural issue. The U.S. government contract contributed roughly $3.4 to $3.5 million of the quarter's $5.1 million in revenue, so contract timing still dictates the income statement.
The conference call confirmed a pattern bears will not ignore. This was the third consecutive quarter below the guidance midpoint:
- Q1: $5.1 million against a $5.5 million guide.
- Q2: $5.5 million against a $6 million guide.
- Q3: $5.1 million against a $5.5 million guide.
Management attributed each shortfall to contract-signing delays. The full-year non-GAAP gross margin target has also been cut for a second straight call, falling from 57% to about 51% to 47% ±5%. Implied full-year revenue growth of about 72% now sits below the 75% midpoint of the 70-80% range set last quarter, a range that originally spanned 50-100%. The architectural eFPGA license once expected in late 2026 has slipped to early 2027.
Against that, the pipeline clearly broadened, and the call preserved a credible growth story. QuickLogic landed its first automotive and industrial eFPGA Hard IP design win, a 16nm SoC for battery management, motor control and robotics, with ratable revenue starting in the fourth quarter. Other pipeline developments include:
- A follow-on 1M LUT Intel 18AP contract, now expanded with a storefront provision.
- A pending award from a major U.S. fabless company for a biomedical/physical-AI chip.
- A second customer win-back from FlexLogix, which is now captive to ADI.
- Small-package antifuse devices now sampling, which management's internal models suggest could lift mature revenue toward roughly $10 million a year, versus about $3.3 million in 2026.
On cost and cash, full-year non-GAAP opex was trimmed to $13.3-13.4 million, Q3 net cash of $14.2 million beat the $13 million projection, and full-year cash flow is now targeted to be positive. The balance sheet is sturdier than a year ago. The revolver was cut to $5 million from $15 million, helped by equity issuance.
Everything now hinges on the fourth-quarter guide. Management called for $8 million ±10%, a 55% sequential jump, with roughly $1.3 million, or $0.07 a share, in non-GAAP net income. That would finally deliver the second-half profitability first modeled a year ago. It also depends on about five contracts closing plus a government tranche whose timing management itself described as opaque. Fourth-quarter cash flow is guided only to breakeven after favorable payment timing helped Q3.
The market had already lost patience before the report. Shares fell 38.4% from the $13.75 open after the August release to $8.47. They sit 32.9% below the 200-day moving average and only about 20% above the inter-earnings low of $7.04 set on November 5. Price and AVWAP trend readings remain negative. Investor sentiment, already negative, slipped slightly further, from -0.33 to -0.35. That modest change suggests skeptics were already positioned for disappointment rather than newly converted by this print.
The bottom line is that QuickLogic delivered a narrower year-over-year loss and a broader opportunity set, but not the execution credibility the stock needed. Sequential revenue and margins weakened, guidance targets keep drifting lower, and the full-year narrative now rests on an unusually concentrated fourth quarter. If the contracts and government tranche land on schedule, the $8 million guide would validate the profitability thesis. Another slip would make it the fourth straight shortfall.
Read our earnings preview for QuickLogic Corporation: https://www.earningswhispers.com/article/QUIK/22761
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-13 | |
| Oct-06 | |
| Sep-29 | |
| Sep-25 | |
| Sep-21 | |
| Sep-02 | |
| Aug-14 | |
| Aug-12 | |
| Aug-11 |
