Stereotaxis Must Prove Its Lowered Catheter-Led Plan Holds As Cash Thins
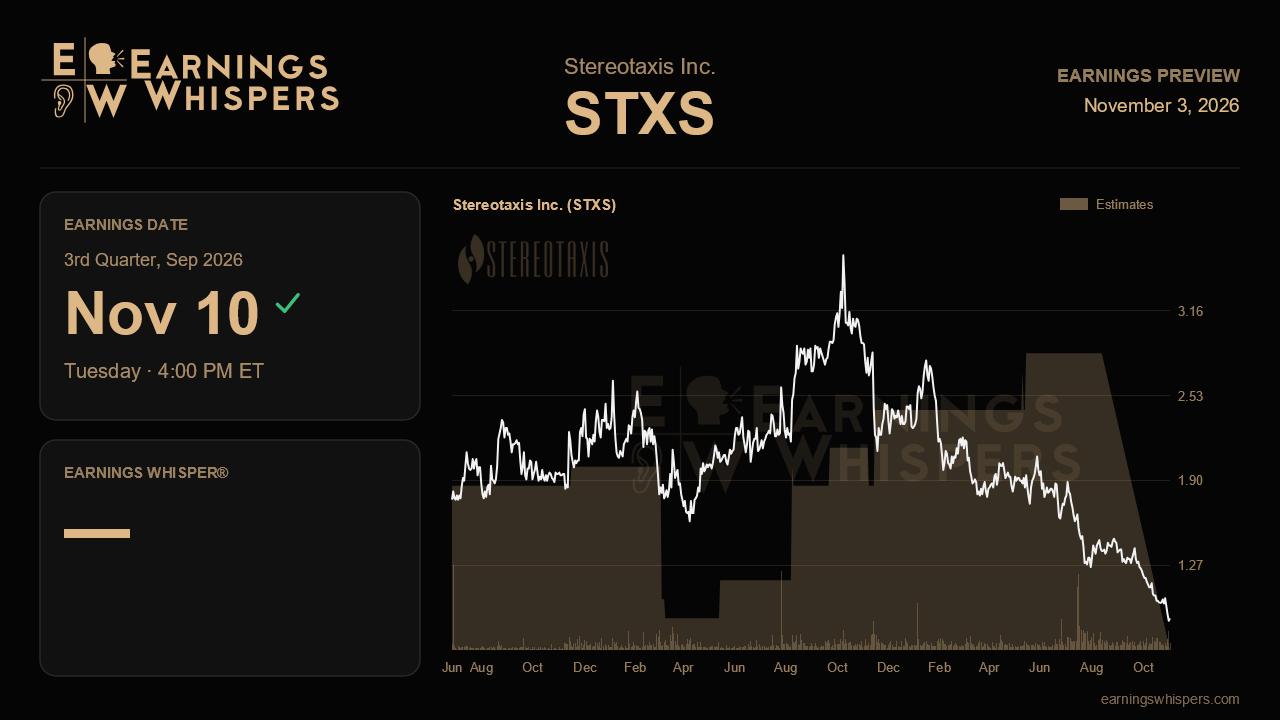
Three months ago Stereotaxis asked investors to accept a trade: a smaller revenue number for the year in exchange for evidence that its proprietary catheter business is finally taking off. The market has not been in a forgiving mood. Shares have fallen about 41% since that report, trailing the S&P 500 by roughly 38 percentage points, and at $0.88 they sit near the bottom of their post-earnings range and about half their 200-day moving average. The third-quarter report due after the close on November 10 is the first real check on whether management's reset plan was conservative enough to hit.
There is no usable published consensus for the quarter, so the most meaningful yardstick is the company's own quarterly build. Management framed the third quarter around roughly $7 million of recurring revenue and about $3 million from systems, implying a top line near $10 million. That compares with $7.5 million in the year-ago quarter and $7.7 million last quarter, so delivering it would mark a genuine step change rather than incremental progress. The context matters, though. For several quarters the company had promised more than $10 million in each of the third and fourth quarters and over $40 million for the full year. The latest build points closer to $35 million, which means even a clean hit simply confirms a lower target. A miss against a bar that has already been cut would be far more damaging than a miss against an ambitious one.
Recurring revenue is the line that carries the bull case. It reached a multi-year high of $6.2 million last quarter as robotic catheter sales topped $1 million, growing several times over from a year earlier, and management described roughly $1 million of added catheter revenue each quarter from here. Reaching about $7 million would show that the MAGIC family is replacing lost Johnson & Johnson volume rather than just offsetting it. The complication is supply: catheter demand has been running ahead of what contract manufacturer Osipka can produce, and only about a dozen U.S. sites were cleared to buy MAGIC. Any commentary that output has caught up with backlog, or that more hospitals have been approved, would strengthen the story. Synchrony, which management suggested could contribute more than $1 million a quarter, offers another check on whether the recurring ramp is broadening.
The system line is where last quarter disappointed. No robotic system shipped, system revenue fell by half from the prior year, and system gross margin slid to 29% from 39%. The first U.S. Genesis X order, from an academic medical center planning a fall installation on unmodified x-ray equipment, and the European installation that management said was back on schedule for year end are the proof points here. Confirmation that the U.S. install happened, along with the promised x-ray compatibility statement, would address one of the key barriers to wider Genesis X adoption. Recurring gross margin of 66% is worth tracking too, since the mid-70s target has already been pushed into 2027 and 2028.
Cash may be the most closely scrutinized figure of all. The company ended last quarter with $10.5 million and no debt while burning around $3.7 million a quarter, a pace that would leave a noticeably thinner cushion by September if unchanged. The newly set target of cash-flow profitability in the first half of 2027, along with the RoboCath integration and first-in-human pulsed field ablation work with MAGIC, all have to be funded in the meantime. Sentiment has turned from essentially neutral before the last report to modestly bearish now, reflecting that skepticism.
The central question is simple: does the revised plan hold? A quarter near $10 million with recurring revenue at or above $7 million and a burn rate that is clearly narrowing would suggest the guidance cut was a one-time reset. Another shortfall, especially paired with faster cash consumption, would make the 2027 profitability goal look like the next target due for revision.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-02 | |
| Oct-30 | |
| Oct-22 | |
| Oct-20 | |
| Sep-16 | |
| Sep-03 | |
| Aug-11 | |
| Jul-21 | |
| Jul-20 | |
| Jul-09 | |
| Jul-09 | |
| May-13 | |
| May-12 | |
| Apr-22 |
