Stereotaxis' Capital-System Momentum Is Overshadowed By Catheter Supply Shortfalls, Margin Compression, And A Forced Convertible Raise
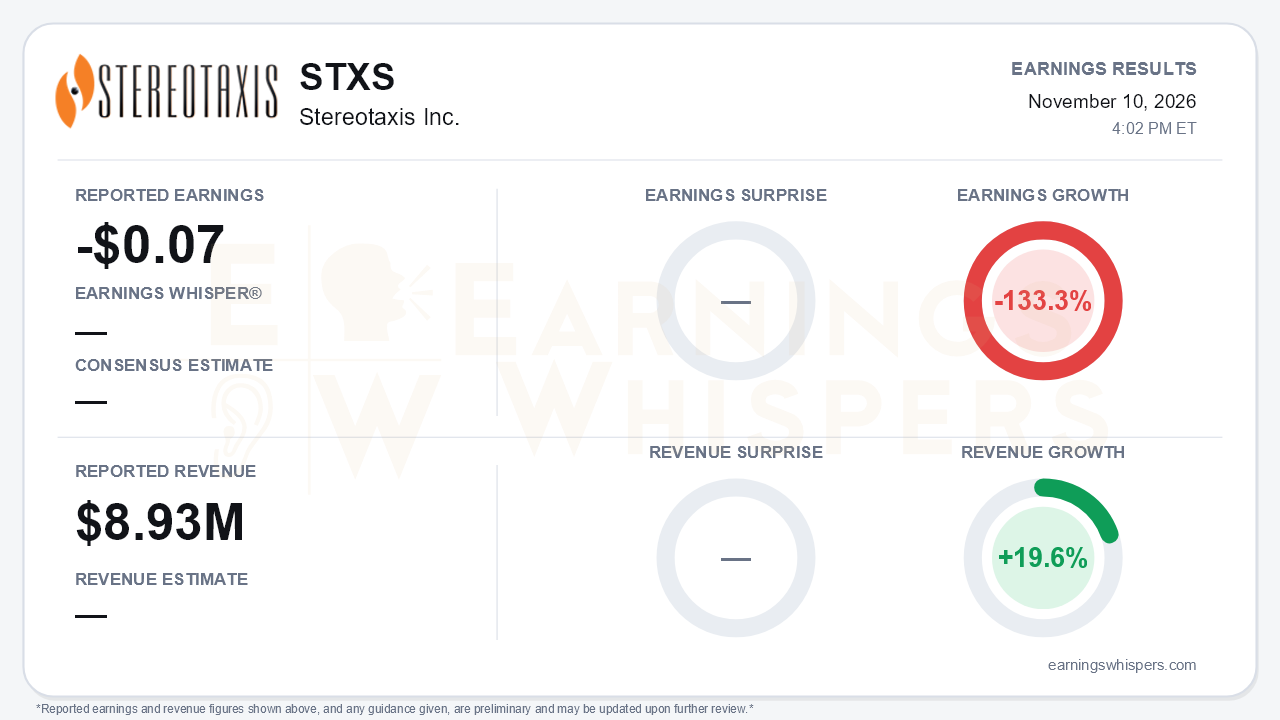
Stereotaxis (NYSE American: STXS) reported a third-quarter loss of $0.07 per share on revenue of $8.93 million. Revenue grew 19.6% year over year and 16% sequentially, the third straight quarter of improvement from $6.3 million in Q1 and $7.7 million in Q2. No consensus estimate was available, so there is no surprise to measure. That leaves the quarter to be judged against management's own targets, and on that test it fell short. On Earnings Whispers' normalized basis, earnings fell 133.3% year over year. GAAP net loss per share was flat at $0.07. The deterioration shows up instead in the adjusted figures: adjusted net loss more than doubled to $5.2 million from $2.4 million. The central tension is that the capital-equipment story improved meaningfully while the recurring, high-margin engine that is supposed to fund the company stalled.
The composition of revenue deserves scrutiny. System revenue rose 60% to $3.0 million, in line with the roughly $3 million management had guided. It included partial recognition on the first U.S. GenesisX, the first Genesis sold in China, and the first full quarter of Synchrony sales. Recurring revenue, however, was $5.9 million. That was up only 6% year over year, down 4% sequentially, and well below the roughly $7 million management had pointed to on the Q2 call. The mix shift toward systems helped drive gross margin down to 45%, from 58% in Q2 and 60% in Q1. System gross margin was just 15%, and management attributed weakness in both segments to fixed overhead spread over low production volume. Adjusted operating expenses climbed to $9.1 million from $6.6 million a year earlier, driven by one-time Robocath transaction costs and the absorption of Robocath's spending.
The call explained where the recurring shortfall came from: catheter supply. Production of the MAGiC catheter at the manufacturing partner was flat from Q2 to Q3. That makes the 500-per-month year-end target, repeated on earlier calls, effectively unattainable. Stereotaxis exited the quarter with about $1.9 million of unfilled disposable orders, and management expects only about half to clear in Q4. A full fix now hinges on a redundant in-house supply source awaiting a regulatory milestone in early 2027. Demand itself does not look like the problem. Robotic catheter revenue rose more than 20% sequentially and more than 400% year over year. In Europe, the company pivoted to two exclusively distributed alternative catheters so that MAGiC supply can be preserved for the U.S.
Guidance credibility took the biggest hit. Earlier calls had set a full-year revenue target above $40 million, with more than $10 million per quarter in the second half. Those targets were not reiterated. The prior $8 million Q4 recurring figure was softened to a 'high watermark,' and the 58% gross-margin expectation was missed. Cash-flow profitability moved from 'first half of 2027' to 'within the next year.' Management did offer real catalysts:
- **GenesisX access:** An August FDA clearance allows GenesisX to work with any non-modified X-ray system. A Canon collaboration accompanies the first U.S. install this month, with Europe to follow soon after.
- **GenesisX pipeline:** Another major X-ray OEM install is visible for early 2027, and the pipeline includes a couple dozen GenesisX opportunities.
- **Synchrony:** Abbott Northwestern became the first multi-lab Synchrony standardization. The Synchrony pipeline is about 50 systems, and management now sees possible quarters of a couple million dollars.
- **Robocath:** First-in-human R-Star data were presented at TCT.
These catalysts preserve a credible long-term platform story, but they are mostly capital sales that carry thin margins today.
The balance sheet is where bears have the most legitimate ammunition. Cash fell to $4.0 million from $10.5 million at Q2 and $14.6 million at Q1. Q3 burn was $6.5 million, of which $3.9 million was Robocath-related payments and $2.6 million came from the core business. Stereotaxis paired the report with a convertible note of up to $24 million: $12 million upfront, plus $12 million available at the company's option after the supply-related regulatory milestone. That lifts pro forma cash to $16 million. The raise comes after the Q2 call had suggested the strategy could be funded within the existing budget. Long-term contingent consideration also jumped to $14.9 million from $4.7 million at year-end, adding future obligations. Management's own tone turned defensive, acknowledging that progress 'may not feel like it' from the capital markets' vantage point.
Investors were already braced for trouble heading into the release. Earnings Whispers sentiment fell sharply, from roughly neutral at 0.0038 to -0.5694, a genuinely large swing. In the snapshot taken the day before the report, shares stood at $1.14. That was 24% below the $1.50 open following the August report and about 31.5% under the 200-day moving average of $1.66. The stock hit a 52-week low of $0.80 on November 3 before rebounding 42.5% off that level. Price, momentum, and AVWAP trend readings all remain negative.
The bottom line is that Stereotaxis delivered genuine progress on making its robots easier to sell, yet it missed nearly every recurring-revenue, margin, and timing marker it had set. It also had to raise dilutive capital to bridge the gap. Until the redundant catheter supply clears its early-2027 milestone and recurring revenue resumes growing at healthy margins, the capital-system wins are unlikely to outweigh the funding and execution questions this quarter raised.
Read our earnings preview for Stereotaxis Inc.: https://www.earningswhispers.com/article/STXS/22768
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Oct-22 | |
| Oct-20 | |
| Sep-16 | |
| Sep-03 | |
| Aug-11 | |
| Jul-21 | |
| Jul-20 | |
| Jul-09 | |
| Jul-09 |
