StubHub Faces Post-World Cup Hangover Test With Shares Near Their Lows
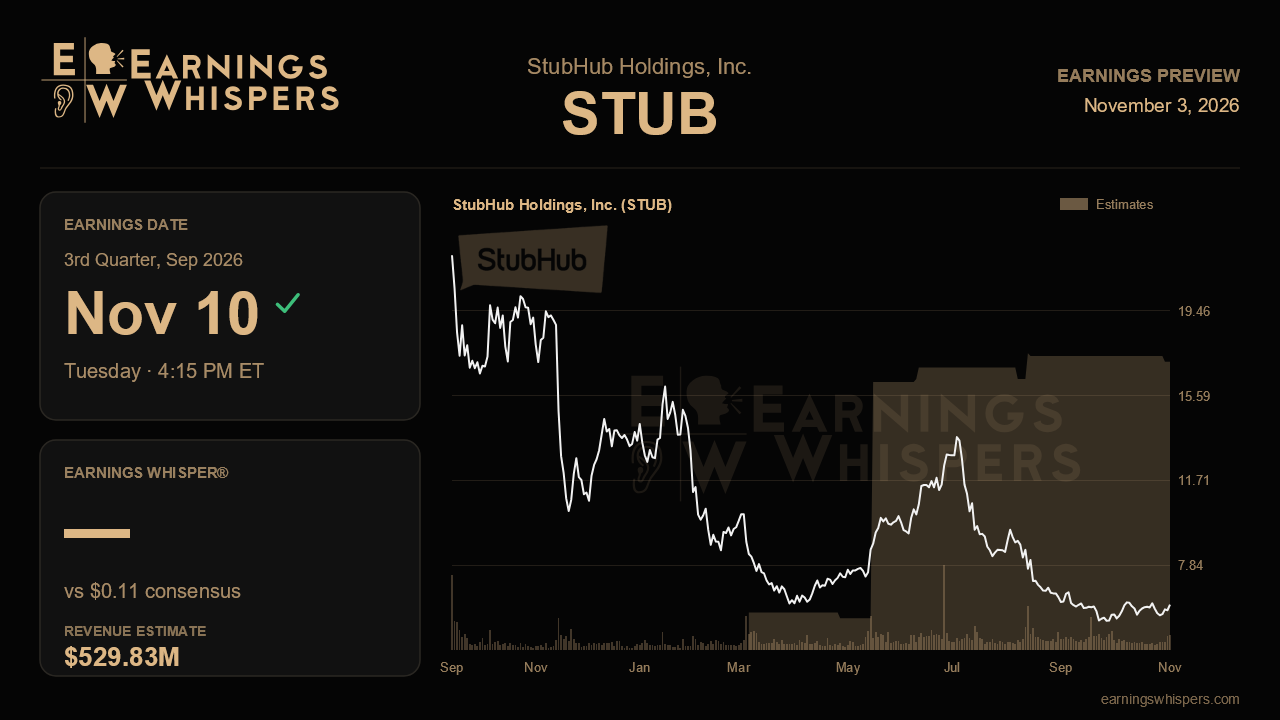
StubHub delivered the kind of quarter last time that usually lifts a young public company's stock. Gross merchandise sales jumped 34%, margins widened and the full-year sales outlook went up. The market shrugged anyway. Shares have fallen 14.3% since that report, trailing the S&P 500 by more than 11 percentage points. The third-quarter results due after the close on November 10 now carry a narrower question: was the World Cup surge a one-off, or does the marketplace hold its momentum once the tournament fades?
Wall Street expects earnings of $0.11 per share on revenue of $529.8 million. That would be a sharp swing from a loss of $0.60 a year ago and revenue growth of about 13% from $468.1 million. Revenue is expected to dip from the prior quarter's $573.1 million, which is normal for a business whose second quarter was inflated by a global event. The growth figure is the more revealing number. Management's raised full-year gross merchandise sales target of $10.1 billion to $10.3 billion, or 10% to 12% growth, implies second-half growth in only the low single digits. A 13% revenue gain against that backdrop asks a lot. It requires either a better share of each ticket dollar turning into revenue or a third quarter that carries most of the second half's growth.
That makes conversion a key swing factor. Last quarter, the share of sales turning into revenue held near 19%, below the near-20% full-year level management had pointed to a quarter earlier. Gross margin also slipped to about 82% from 85%, as World Cup payment, fulfillment and customer-support costs ate into profitability. If those were truly one-time costs, both metrics should recover this quarter. If conversion stays stuck and gross margin does not rebound, the Street's revenue and earnings math starts to look stretched.
Profitability is the second test. Adjusted EBITDA margin climbed from 14% to 16% to 18% over three straight quarters. Sales and marketing efficiency improved by roughly 800 basis points year over year, which supports the argument that a large marketplace gets more profitable as it grows. Yet management left its $400 million to $420 million adjusted EBITDA outlook unchanged even after raising the sales target. The gap was explained by World Cup costs and legal and regulatory professional fees. A steady or higher margin as those costs fall away would support the operating-leverage story. A softer margin, together with still-elevated G&A and stock compensation of about $69 million a quarter, would suggest those costs are more persistent than management described.
Management also signaled caution for the second half. It warned that World Cup spending may have pulled forward some consumer entertainment budgets. Any early read on fourth-quarter demand will matter, along with updates on newer growth sources such as the American Athletic Conference and NCAA distribution deals and the self-serve Distribution Manager tool. The balance sheet has been a quiet strength. Net leverage fell to 3.0x, and trailing free cash flow reached $598 million. Further debt paydown would ease concerns for a stock that sentiment has turned against, with bearish readings rising to 41.7% from 12% a quarter ago.
The chart reflects that mood. At $6.04, the stock sits well below its 200-day moving average of $8.48. It trades closer to the bottom than the top of its post-earnings range of $5.22 to $8.08, and that entire range sits below the prior quarter's $8.06 to $14.02. Expectations for the shares have clearly reset lower, even though the operating results have not yet shown a slowdown. In the end, the report needs to show that StubHub can grow without the World Cup: conversion moving back toward 20%, gross margin rebounding and EBITDA margins holding their gains while sales growth cools as expected. Clear evidence on those points would ease concerns about a post-tournament slump. Weakness on them would suggest the selloff was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-15 | |
| Oct-14 | |
| Sep-24 | |
| Sep-18 | |
| Sep-18 | |
| Sep-02 | |
| Aug-21 |
US Open's pricey tickets are getting major backlash: 'The wealth effect is real'
STUB
Yahoo Finance Video
|
| Aug-21 |
US Open's pricy tickets are getting major backlash: 'The wealth effect is real'
STUB
Yahoo Finance Video
|
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 |
World Cup Ticket Fiasco Erases StubHub Profits, Sending Stock Down
STUB -10.07%
The Wall Street Journal
|
