StubHub Misses On EPS And Revenue, But A Record 25% EBITDA Margin And Third GMS Raise Leave Margin Durability And Q4 Growth As The Open Questions
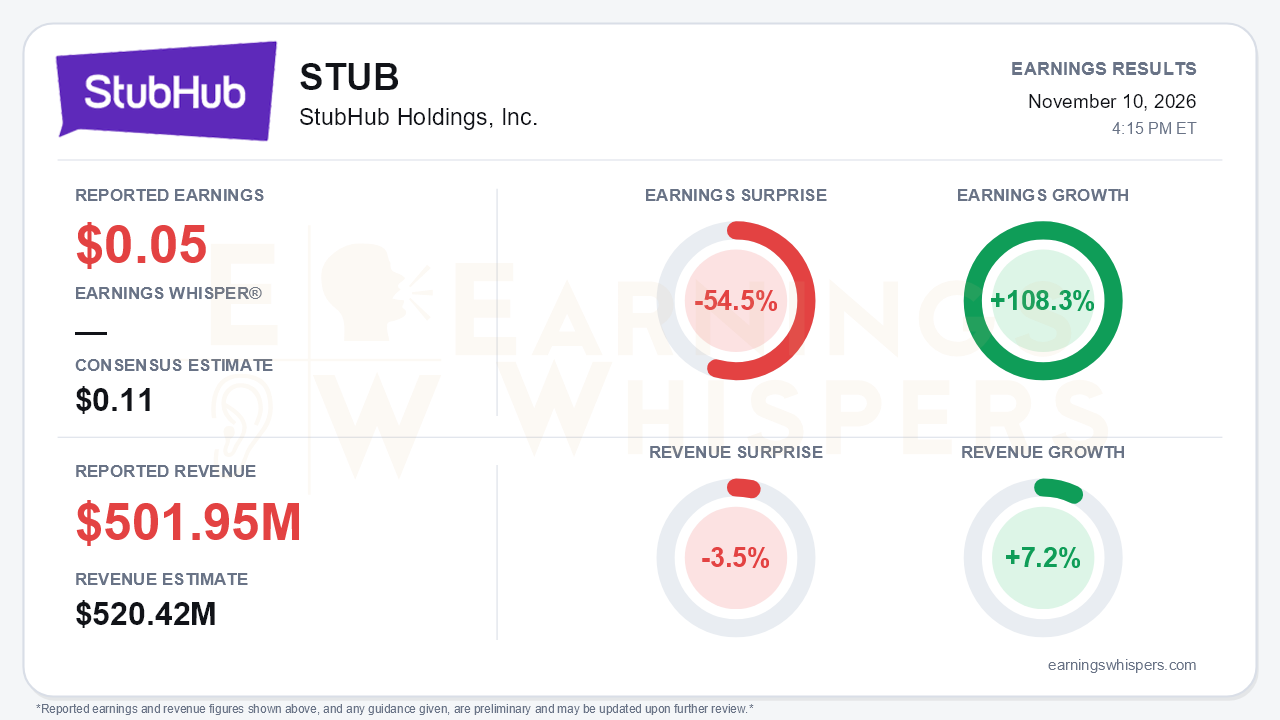
StubHub's third quarter missed on both lines. GAAP earnings of $0.05 per share fell 54.5% short of the $0.11 consensus, and revenue of $501.95 million missed the $520.42 million estimate by 3.5%. Even so, the report showed the strongest operating profitability since the company went public. Adjusted EBITDA rose 84% to $124.1 million, and the adjusted EBITDA margin reached a record 25%, up from 14% a year ago. Management also raised its full-year GMS outlook for the third consecutive quarter. Earnings grew 108.3% year over year, a swing from a $4.27 per-share loss that was swollen by $1.4 billion of IPO-related stock compensation. Revenue grew 7.2%. That is the central tension: profitability is clearly improving, while top-line growth has cooled sharply now that the World Cup boost has passed.
The gap between the GAAP miss and the strong adjusted results deserves scrutiny, because much of it comes from items investors cannot fully dismiss.
- **Litigation reserves** jumped to $19.0 million from $3.4 million in Q2.
- **Indirect tax contingency costs** climbed to $11.5 million.
- **Stock compensation** still ran $42.5 million.
- **Preferred stock** cut income available to common holders roughly in half, from $33.6 million of net income to $18.6 million.
The underlying cost structure, by contrast, looks genuinely better.
- Adjusted gross margin improved to 85% from 82% in Q2.
- Take rate moved above 19% from roughly 18.5%, and management is guiding toward about 20%.
- Sales and marketing fell to 45% of revenue, down from 47% in Q2, 50% in Q1 and 52% in Q4 2025.
- Adjusted G&A rose to $64.2 million from $52.2 million a year ago, which partly offsets those gains.
The growth picture is weaker. GMS growth slowed to 7% from 34% in Q2, and revenue fell sequentially from $573 million. Management guided full-year GMS to $10.175 billion to $10.375 billion, or 11% to 13% growth. That compares with 10% to 12% three months ago and 8% to 10% at the start of the year. However, the call made clear that underlying fourth-quarter growth is only high-single-digit, held back by two headwinds:
- lapping the December 2025 World Cup general on-sale;
- a short, small-market World Series.
Uncertainty over when 2027 concert on-sales will occur also widened the Q4 range.
The EBITDA outlook was reiterated at $400 million to $420 million rather than raised, despite the higher GMS outlook. With $301.8 million earned through nine months, that implies Q4 adjusted EBITDA of roughly $98 million to $118 million. That would still be well above the $62.7 million in last year's fourth quarter, but it also suggests the 25% third-quarter margin is not a new run rate.
Cash flow and the balance sheet tell a split story. Third-quarter free cash flow was negative $410 million as World Cup seller payables unwound by $447 million. Trailing-12-month free cash flow fell to $192 million from $598 million. Management's underlying figure of roughly $280 million is steadier, but net cash after seller obligations still slipped to $417 million from $490 million. Leverage tells a better story:
- **Debt reduction:** StubHub repaid $100 million of debt in July.
- **Refinancing:** In October it extended its term loan maturities 3.5 years to 2033 at a 25 basis point lower borrowing cost.
- **Net leverage** fell to 2.5x from 4.5x at year-end, which has management openly discussing buybacks.
On the business side, the Big 12 open-distribution deal adds credibility to StubHub's primary-ticketing ambitions, and failed price-cap bills in California and New York lowered regulatory risk. Bears still have legitimate ammunition:
- the NFL adopted open distribution for season-ticket holders without StubHub;
- CFO Connie James is departing, with TripAdvisor's Mike Noonan arriving in January.
The market had been skeptical well before the print. Shares opened at $7.05 after the August report, briefly peaked at $8.08, then slid to a 52-week low of $5.22 on September 29. At $5.85 heading into this report, the stock was down 17% since the last release, 29.2% below its $8.26 200-day moving average, and only about 12% above that low. Earnings Whispers investor sentiment deteriorated meaningfully, from -0.12 to -0.29, so expectations were already guarded. The trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that StubHub delivered a messy headline but a cleaner operating story than the miss suggests. Rising take rates, lower marketing intensity and rapid deleveraging are real improvements, and the third GMS raise signals confidence in demand. Against that, revenue growth has decelerated to the high single digits, GAAP earnings are being eroded by litigation and tax charges, and the unchanged EBITDA outlook implies margins will cool in Q4. For a stock trading near its lows with souring sentiment, the burden of proof now rests on showing that growth can reaccelerate once the World Cup comparisons fade.
Read our earnings preview for StubHub Holdings, Inc.: https://www.earningswhispers.com/article/STUB/22767
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-15 | |
| Oct-14 | |
| Sep-24 | |
| Sep-18 | |
| Sep-18 | |
| Sep-02 | |
| Aug-21 |
US Open's pricey tickets are getting major backlash: 'The wealth effect is real'
STUB
Yahoo Finance Video
|
| Aug-21 |
US Open's pricy tickets are getting major backlash: 'The wealth effect is real'
STUB
Yahoo Finance Video
|
