Ranger Energy Must Prove Its $100 Million EBITDA Pace Survives Wireline's Fade
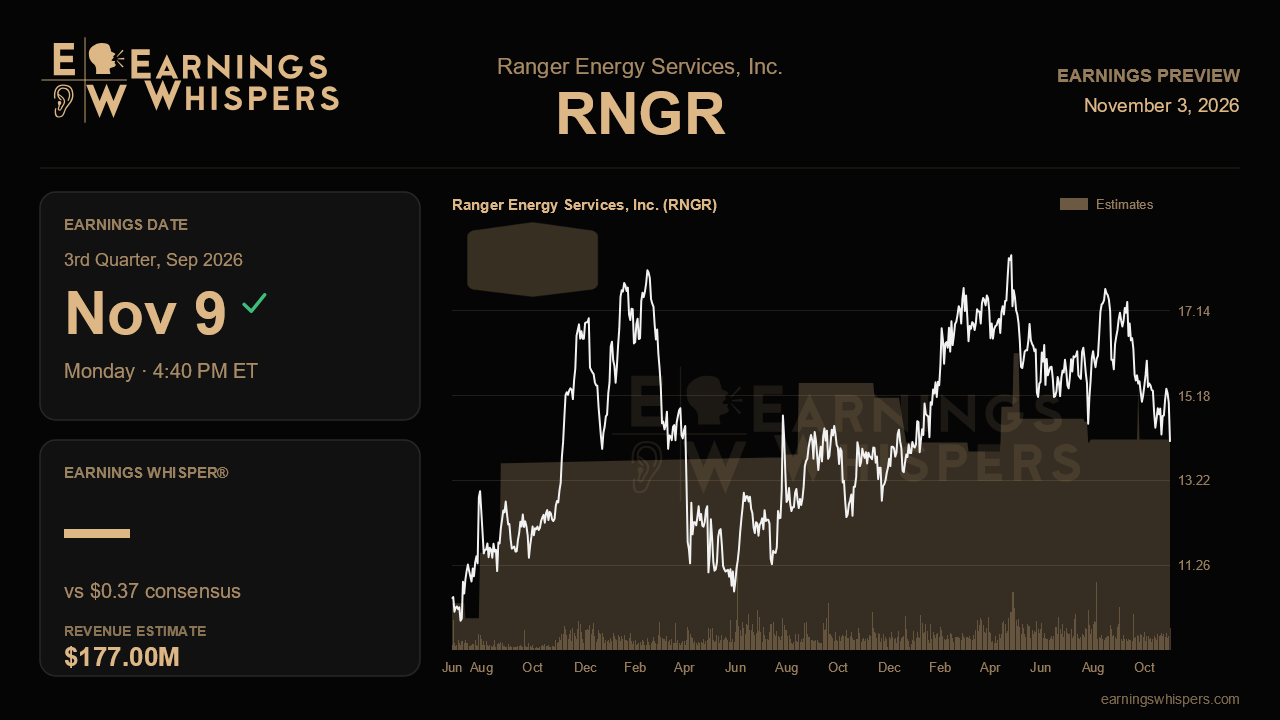
Ranger Energy Services heads into its third-quarter report with an unusual problem: the business has rarely looked better on paper, yet the stock has been treated as if the good news is already behind it. Last quarter the well services provider crossed the annualized adjusted EBITDA run-rate of more than $100 million that it had been building toward since its acquisition push began, and margins climbed above 15% for the first time in the recent series. The catch is that a meaningful slice of that strength came from a wireline contract that management openly said would not repeat. This report, due after the close on November 9, is the first real test of whether Ranger's earnings power holds up once that one-time lift disappears.
Wall Street is looking for earnings of $0.37 per share on revenue of about $177.0 million. That revenue figure would represent growth of roughly 37% from the year-ago quarter's $128.9 million, and the profit estimate implies a more than sixfold jump from the $0.05 earned a year earlier. Sequentially, though, the picture is essentially flat, since the second quarter delivered $176.5 million in sales. That lines up neatly with management's outlook, which reaffirmed full-year adjusted EBITDA above $100 million and called for the third quarter to look similar to the second before the usual fourth-quarter softening from holidays and weather. The Street, in other words, is sitting squarely inside what the company signaled rather than reaching for upside.
The arithmetic behind a flat quarter is more demanding than it looks. Wireline produced $18.6 million in revenue and $3.6 million of EBITDA last quarter at a 19% margin, and management guided that business back to single-digit margins on a softer top line for the rest of the year. Matching the prior quarter's $28.6 million in adjusted EBITDA therefore requires the high-spec rig segment and ancillary lines to absorb several million dollars of lost wireline profit. High-spec segment EBITDA actually slipped to $20.6 million last quarter as a state sales tax audit and make-ready costs for the ECHO rig program weighed on margins. A rebound back above 19% in that segment, with the tax issue fading and ECHO costs shifting from preparation to revenue, would be the cleanest validation of the story.
ECHO is the catalyst with the longest runway. Contracts reached 20 rigs after Chevron added three, the first two units were slated to be operational by the end of the quarter, and management described a deployment pace of about one rig per month along with growing confidence that the rigs are additive rather than replacing existing work. Evidence that those rigs are earning revenue on schedule, plus any hint of the additional contracts management expects over the next nine to twelve months, would strengthen the case that growth extends well beyond this year. Coil tubing, plugging and abandonment, and the Torrent gas processing business each grew more than 20% last quarter, so continued momentum there would help counter management's own description of ancillary results as inconsistent. Cash flow also deserves attention after free cash flow swung to a positive $20 million; further progress collecting receivables delayed by June billing issues would show that turnaround was not a timing quirk.
The market's mood has cooled noticeably. Sentiment has slipped from moderately bullish ahead of the last report to slightly bearish now, and the shares have fallen 7.5% since that release while the S&P 500 gained 1.8%. At $14.11, the stock sits well below its 200-day moving average of $16.21 and barely above its post-earnings low of $13.99, with a trading range that has shifted lower than the prior quarter's.
That setup lowers the emotional bar but not the operational one. If Ranger can show third-quarter EBITDA holding near second-quarter levels without wireline's help, the $100 million narrative stays intact and the recent selloff starts to look overdone. If the wireline fade shows up as a visible earnings step down, the skeptics will have their proof.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Aug-31 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-20 | |
| Jul-14 | |
| Jul-14 | |
| May-28 | |
| Apr-29 | |
| Apr-27 | |
| Apr-27 | |
| Apr-22 |
