Ranger Energy Misses Sharply As Margin Squeeze And A Dropped $100M EBITDA Target Overshadow Coil And ECHO Expansion
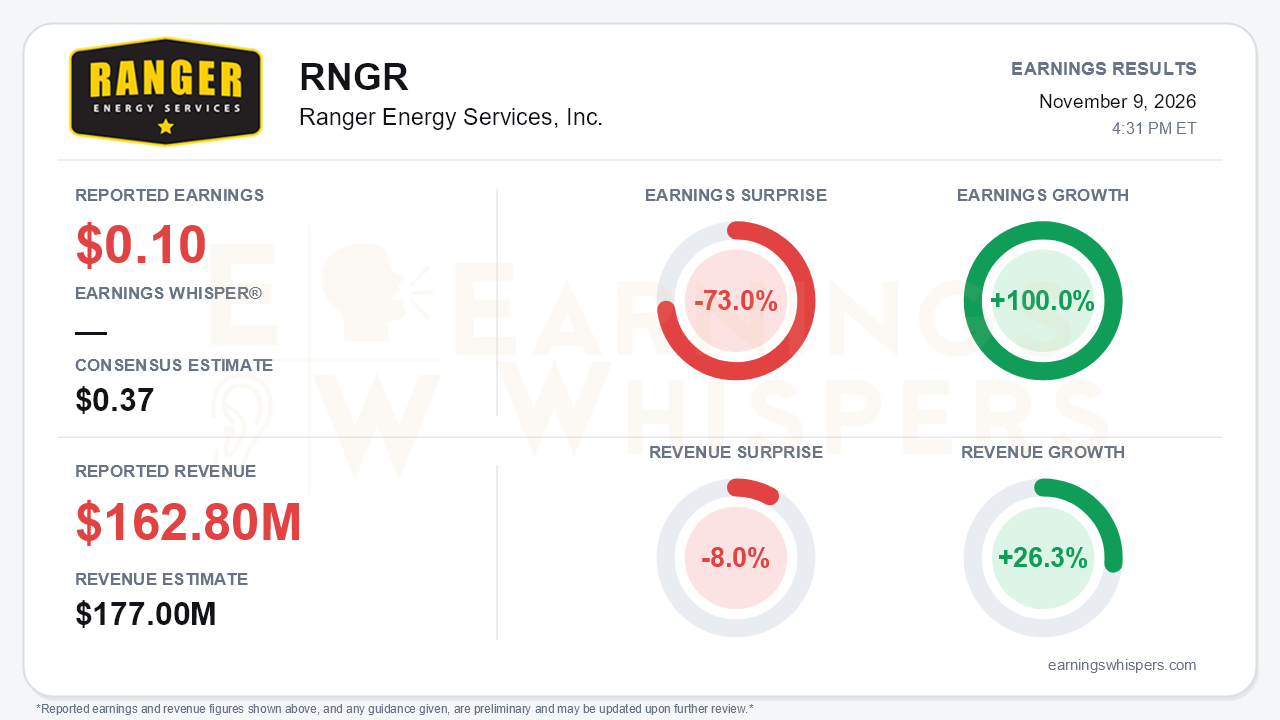
Ranger Energy Services delivered a quarter that fell well short of what both Wall Street and its own management had signaled. Third-quarter earnings of $0.10 per share missed the $0.37 consensus by 73.0%, and revenue of $162.8 million came in 8.0% below the $177.0 million estimate. On a year-over-year basis the numbers look healthy: earnings grew 100.0% and revenue rose 26.3%. That growth is almost entirely acquisition-driven, though, from last year's AWS deal. The more telling comparison is sequential. EPS fell from $0.29 in the second quarter, revenue dropped 7.8%, and Adjusted EBITDA slid from $28.6 million to $20.1 million, with margin compressing from 16.2% to 12.3%. That is the central tension. Ranger is adding strategic scale faster than ever while its existing base is losing earnings power.
The quality of the quarter also deserves scrutiny. GAAP operating income of $4.8 million included a $3.0 million non-cash gain from a change in the fair value of contingent consideration, which flattered the bottom line. Cost of services rose to 85% of revenue from roughly 81% as utilization softened and costs climbed, led by an incremental $1.5 million in employee medical expenses plus higher wages and diesel. The miss was broad. High Specification Rigs margin fell to 16.7% from about 18.2%, against second-quarter guidance pointing toward roughly 20%. Rig hours declined 2% and the hourly rate was flat at $770. Ancillary margin dropped to 17% from 22.5%. Several AWS-acquired lines underperformed, including Transportation, Mixing Plants and Tubing Inspection, and Torrent absorbed one-time charges. Wireline EBITDA collapsed to $0.2 million from $3.6 million, the one decline management had actually flagged in advance.
The call made clear that the problems were not purely seasonal. Customers exhausted budgets and left white space across the rig fleet. Smaller competitors displaced by industry consolidation cut prices in the Permian to win back share, and Ranger chose not to follow. Management argues that pricing discipline will pay off when budgets reset in 2027, but in the near term it cost activity. The tone shifted noticeably from the 'increasingly optimistic' posture of the second-quarter call to an acknowledgment that 'this quarter tested us.' More consequentially, the >$100 million fiscal 2026 EBITDA target was not reaffirmed. That target was set at year-end 2025 and reiterated last quarter, and it is now framed as an annualized goal. With roughly $72 million earned year to date, that reframing is effectively a cut. No 2027 outlook was offered.
The call preserved a credible growth story. The STEP coiled tubing acquisition closed October 8 for about $27.5 million. It makes Ranger the second-largest lower-48 coil provider and is expected to contribute more than $10 million of EBITDA in 2027. Chevron committed to four more ECHO hybrid-electric rigs, lifting the contracted fleet to 24 by end-2027, up from 20 last quarter and 17 at year-end 2025. Five rigs have been delivered, the build program is running slightly ahead of schedule, and interest is broadening to other operators. AWS synergies reached $5.2 million annualized, ahead of the $5 million target. Third-quarter free cash flow of $20.0 million allowed Ranger to repay the revolver to zero and lift liquidity to $76.2 million.
Bears have legitimate ammunition on the balance sheet, however. Year-to-date free cash flow of $18.3 million trails last year's $25.8 million. Receivables jumped to $113.5 million from $77.9 million after a customer moved to 90-day payment terms. The zero-debt position is also a snapshot, since the revolver was tapped again to fund STEP. On top of that, management expects labor tightening, partly driven by data center construction, to persist into 2027, while AWS reorganization and STEP integration add execution risk.
The market had already been leaning against the stock. Shares opened at $15.25 after the July report and now sit at $12.47, down 18.2%. That leaves them 22.9% below the 200-day moving average of $16.17. Investor sentiment flipped from modestly positive (0.17) to slightly negative (-0.04), a meaningful deterioration rather than a collapse. The Earnings Whispers trend readings lean negative on price and AVWAP, though momentum is positive.
The bottom line is that Ranger's strategic platform got bigger and better funded this quarter while its core earnings power got weaker. The sharp miss, margin erosion across every segment, and the quiet retreat from the $100 million EBITDA target undermine management's credibility on near-term guidance. The ECHO and coil catalysts are real, but they are 2027 stories. Until pricing pressure eases and costs stabilize, investors are being asked to look through a deteriorating present toward a promised but unquantified recovery.
Read our earnings preview for Ranger Energy Services, Inc.: https://www.earningswhispers.com/article/RNGR/22788
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Aug-31 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-20 | |
| Jul-14 | |
| Jul-14 | |
| May-28 | |
| Apr-29 |
